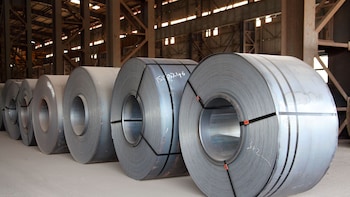
Tata Steel's September quarter earnings beat Street estimates, with strong India volumes offsetting higher coking coal costs. Most analysts remain bullish on the stock amid expectations of resilient India operations, supported by higher realizations and incremental volumes.
The Tata group steelmaker posted consolidated net profit of Rs 3,666 crore in the second quarter of FY27, registering a growth of 58% from Rs 2,318 crore in the preceding quarter.
-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
The company's revenue in Q2FY27 grew 8% to Rs 65,436 crore from Rs 60,794 crore, quarter-on-quarter (QoQ).
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Earnings before interest, taxes, depreciation and amortisation (EBITDA) rose 14% to Rs 10,533 crore from Rs 9,264 crore, while EBITDA margin improved to 16.1% from 15.2%, QoQ.
ALSO READ: Tata Steel Q2 Results: Net Profit Up 58%, Beats Estimates; Noel Tata To Retire As Vice Chairman
Here's what brokerages said on Tata Steel Q2 results:
Goldman Sachs on Tata Steel
- Maintain Neutral; hike target price to Rs 215 from Rs 210
- Management guides for Rs 3,500 per tonne improvement in domestic steel realisations, offsetting higher coking coal costs
- Downstream and value-added products expected to drive India profitability until NINL expansion in FY30
- Hikes FY27–29 EBITDA estimates by 1–4%; European operations remain a key risk
HSBC on Tata Steel
- Maintain Buy; Target Price at Rs 260
- Management guides for Rs 3,500–3,600 per tonne improvement in India steel realisations in Q3FY27
- UK operations expected to approach EBITDA breakeven by Q4FY27 as excess inventories clear
- Targets around Rs 70 bn FY27 cost savings; NINL expansion remains on track for FY30
Jefferies on Tata Steel
- Maintain Buy; Target Price at Rs 240
- Expects 7% India volume growth in FY27, followed by slower expansion until FY31
- Higher steel prices expected to lift India EBITDA per tonne to Rs 19,500–19,900 through FY29
- Hikes FY27–29 EPS estimates by 2–5%; prefers JSW Steel amid Tata Steel's limited volume growth
JP Morgan on Tata Steel
- Maintain Neutral; Target Price at Rs 200
- India realisations expected to rise Rs 3,500 per tonne in Q3FY27, supporting stronger second-half profitability
- UK EBITDA breakeven delayed to Q1FY28; Netherlands recovery expected as volumes improve
- Netherlands decarbonisation investment decision expected by March 2027
ALSO READ: Five Stocks To Buy Today, November 9: Alkem Labs, MTNL, Wockhardt And More
Disclaimer: The views and opinions expressed by the investment advisers on NDTV Profit are of their own and not of NDTV Profit. NDTV Profit advises users to consult with their own financial or investment adviser before taking any investment decision.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.