Dividend TDS is not necessarily the final tax liability. The 10% deducted can be claimed as credit, with excess refunded or additional tax payable based on total income.
Taxes
 Got Rs 1 Lakh Dividend Income? When Can TDS Be Refunded And When It Becomes A Tax Bill?
 Missed Your June Advance Tax Payment? How Much Should You Pay By Sept 15?
Taxpayers liable to pay advance tax must ensure that 45% of their estimated annual liability has been paid cumulatively by September 15 to avoid interest.
 Advance Tax Due Today: Sold Stocks, Earned FD Interest Or Got A Bonus? Check Your Tax Before Paying
Any taxpayer whose estimated tax liability for a financial year, after accounting for TDS/TCS, exceeds Rs 10,000, has to pay advance tax.
 Salary + Stock Profit + FD Interest: Do You Need To Pay Advance Tax By Sept 15?
Taxpayers earning income from salary along with FD interest, capital gains, stocks or other sources may need to pay advance tax if their net tax liability after TDS and TCS exceeds Rs 10,000.
 Taxing A Promise: The Unsettled Story Of GST On Corporate Guarantees
These concerns are particularly relevant for businesses in the infrastructure, real estate, power and EPC sectors, where guarantees run for several years over the duration of the project and involve substantial amounts.
 ITR Deadline 2026: Tax Audit Due Sept 30, Return Filing Due Oct 31 — Process Explained
Taxpayers subject to a tax audit must submit their audit report by Sept. 30 and file their ITR by Oct. 31 for Assessment Year 2026-27.
 Missed EPF Contributions For Years? Here's What Happens To Your PF And Pension Benefits
The missing money can affect your EPF balance, the interest you earn and, in some cases, it can affect both your retirement savings and pension benefits.
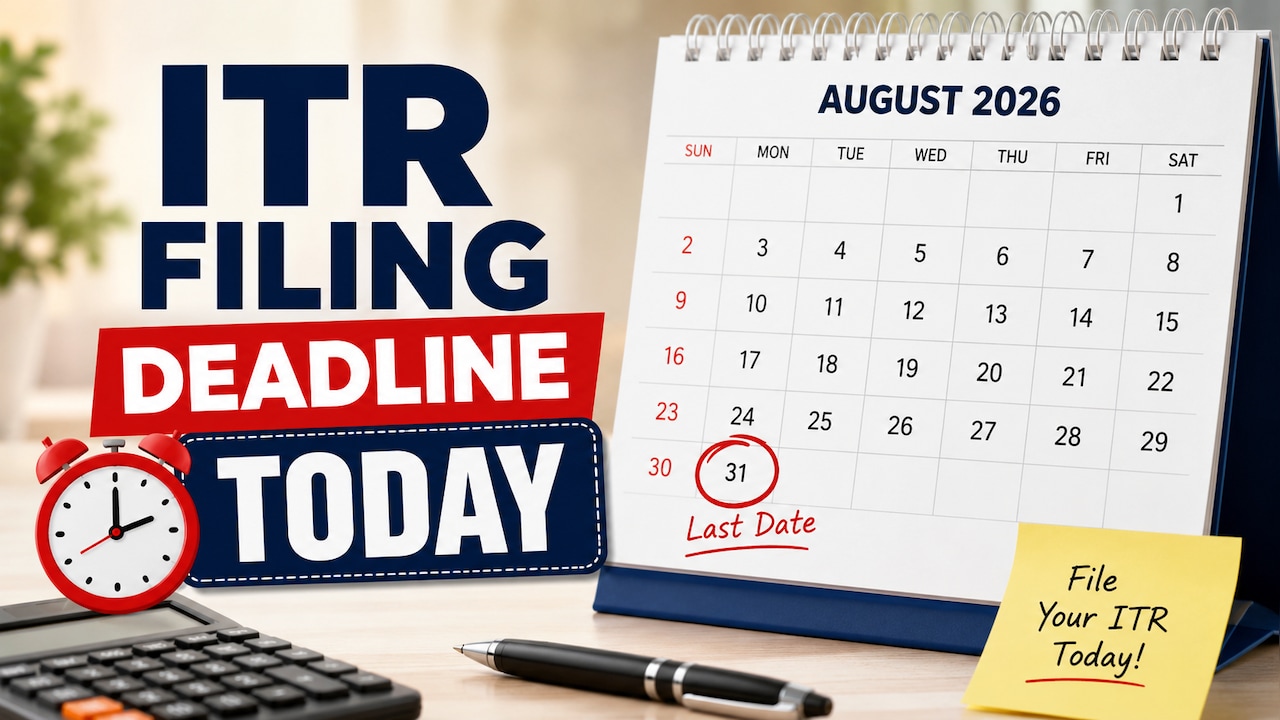 ITR Filing Deadline Today: What Happens If You Miss Aug. 31 Due Date? Common Mistakes To Avoid
August 31 is the deadline for eligible taxpayers to file ITRs for AY 2026-27. Know the consequences of missing the deadline and the common mistakes to avoid while filing ITR-3 or ITR-4.
 Filing ITR With GST Registration? Check Turnover, GST And ITR Form Before Submitting
In non-audit cases, the GST registration does not determine the ITR form that must be filled by taxpayers with business or professional income.
 Forgot To Report Foreign Income? Updated ITR Or FAST-DS — Which Is Better?
Taxpayers seeking to rectify earlier omissions currently have two routes: file an Updated Income-tax Return (ITR-U) or use the Foreign Assets of Small Taxpayers - Disclosure Scheme, 2026 (FAST-DS).
 ITR Filing Deadline 2026: Check If You Need To File By Aug. 31, Oct. 31 Or Nov. 30
The July 31, 2026 deadline applied to salaried individuals and those eligible to file ITR-1 or ITR-2, while several other taxpayer groups now have important filing dates approaching.
 Filed Wrong ITR Form? Here's How To Refile Before August 31 - Step-By-Step Guide
You may have submitted ITR-1 or ITR-2 in haste, only to realise later that your tax return also included intraday trading, F&O losses or income from freelance consulting. Such income can call for ITR-3 or ITR-4 instead.