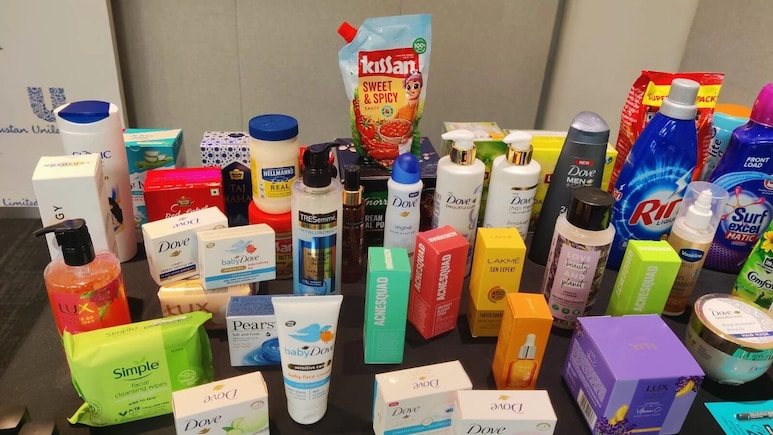
Hindustan Unilever Ltd. (HUL) is expected to report higher revenue for the September quarter of fiscal 2027, supported by price increases and a recovery in sales volumes, although elevated input costs could limit operating profit growth.
Consensus estimates by Bloomberg suggest HUL's revenue will rise 8.2% year-on-year to Rs 17,582 crore from Rs 16,241 crore in the year-ago quarter. Net profit is expected to increase 3.6% to Rs 2,784 crore from Rs 2,685 crore. Earnings before interest, taxes, depreciation and amortisation (Ebitda) are projected to grow 7.7% to Rs 4,018 crore from Rs 3,729 crore. The Ebitda margin is estimated at 23.12%, compared with 23% a year earlier.

-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 Silver Is Now Down From Rs 4.2 Lakh To Rs 1.9 Lakh: Where It Goes From Here
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Brokerages, however, have offered a more optimistic outlook for revenue growth, with some expecting double-digit expansion on a like-to-like basis, excluding the impact of the ice cream business demerger.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
HUL Q2 Results: What To Expect
Pricing is expected to remain a key driver of HUL's revenue growth, as earlier price increases flow through to reported numbers. Volume growth is also expected to improve, with estimates ranging from mid-single digits to around 7%. The combination of higher pricing and a recovery in volumes could support the company's top line. However, the extent to which consumers absorb price increases without cutting back on purchases will remain important for the outlook.
READ | HUL Continues Hikes In Detergent Prices Across Wheel, Surf Excel, Rin In October
Input cost inflation is likely to remain a key concern. While revenue and Ebitda are expected to grow, higher raw material costs could weigh on profitability and limit margin expansion. Investors will also track rural and urban demand trends, the pace of volume recovery and management's assessment of the consumer environment. The balance between pricing-led growth and underlying volume growth will be particularly important in assessing the sustainability of the recovery.
HSBC
HSBC expects HUL's year-on-year revenue growth to improve to around 12% in the September quarter from 10% in the June quarter, partly supported by a favourable base. The brokerage expects volume growth of around 7%, although the two-year compound annual growth rate is projected at 3.5%, similar to the June quarter.
HSBC expects the Home Care and Beauty & Wellbeing businesses to report low-to-mid-teens growth as price increases continue to flow through and volumes recover on a low base. The soaps and tea businesses could continue to see varying effects from palm oil and tea pricing, respectively.
The brokerage estimates consolidated revenue growth of around 12% and Ebitda of Rs 4,070 crore, up 7% year-on-year. The Ebitda margin is projected at 22.8%, broadly similar to the June quarter.
UBS
UBS also expects HUL to deliver double-digit revenue growth in the September quarter, supported by price increases and improving volumes. The brokerage estimates volume growth of nearly 6%, with pricing contributing 4%-5% following price hikes taken by the company.
However, UBS expects Ebitda growth to lag revenue growth because of higher input costs. This could limit the extent to which stronger sales translate into improved operating profitability.
Nuvama
Nuvama expects HUL's consolidated revenue to grow around 13% year-on-year on a like-to-like basis, excluding the ice cream business from both the September 2025 and September 2026 quarters. The growth is expected to be driven by volume growth of 7% and pricing growth of around 6%. The brokerage estimates Ebitda to rise around 8% year-on-year, while net profit is expected to increase 8.5%. It has revised its headline revenue and Ebitda estimates downward by around 2%.
READ | HUL Q2 Results: Date, Time, Dividend News, Earnings Call Schedule And More
Nuvama expects gross margin to decline 221 basis points year-on-year to 48.3%, while remaining broadly flat sequentially. Ebitda margin is projected at 23.1%, down 112 basis points year-on-year but up 27 basis points from the June quarter.
The brokerage noted that HUL had taken a price hike of around 5% in the June quarter and expects a further increase of around 2% in the September quarter, supporting pricing growth. Tea volumes could remain muted, according to Nuvama. The brokerage cited weakness in the early part of the quarter due to LPG availability issues affecting out-of-home consumption, alongside some impact from delayed monsoons.
Key Factors To Watch
The September-quarter performance will offer clues on whether HUL's recovery is broadening beyond price increases. Investors will watch the split between volume and pricing growth, particularly as higher prices can support revenue but may also affect consumer demand. Raw material inflation and its impact on gross and Ebitda margins will be another focus. Management commentary on rural demand, urban consumption, further pricing actions and the outlook for input costs could shape expectations for the coming quarters.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.