BQ Prime's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer BQ Prime's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Motilal Oswal Report
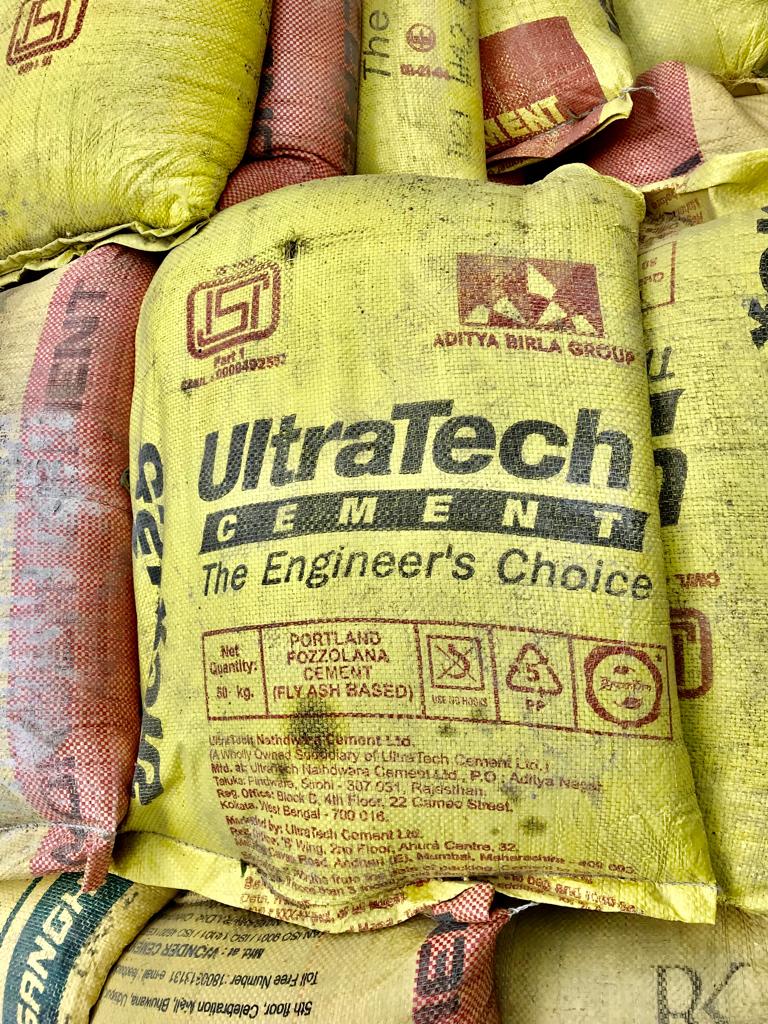
Earnings for UltraTech Cement Ltd. as well as the cement sector is expected to remain under pressure in H1 FY23 and lower than our earlier estimate due to:
sustained cost pressures (we expect a Rs 300-350/tonne increase in energy costs in H1 FY23),
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
recent decline in cement prices, which came under pressure in June 2022,
lower than our estimated growth in cement demand in Q1 FY23, and
tendency to increase capacities by different players (UltraTech Cement and Shree Cement Ltd. recently announced capacity expansions).
Earnings recovery for UltraTech Cement in FY21 and H1 FY22 was driven by fixed cost controls as well as a better pricing scenario.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. BQ Prime does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of BQ Prime.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.