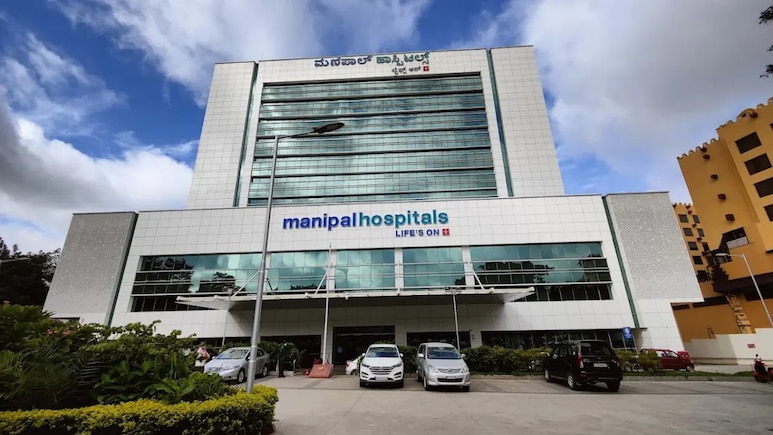
Brokerages turned more constructive on Manipal Health following its second-quarter performance, with JPMorgan upgrading the stock and several others raising earnings estimates and target prices amid confidence in the hospital operator's growth trajectory.
JPMorgan upgraded Manipal Health to 'Overweight' from 'Neutral' and raised its target price to Rs 820 from Rs 800. The brokerage said faster-than-expected integration of Sahyadri Hospitals and improving occupancy levels are supporting stronger profitability and operating leverage. It highlighted that the company's newer Bengaluru hospitals are already approaching EBITDA margins of 24-25%, reinforcing confidence in its greenfield expansion strategy.
The brokerage increased its FY27-FY29 EBITDA estimates by 5%, citing stronger execution across core operations and the benefits of acquisition synergies.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
HSBC maintained its 'Buy' rating with a target price of Rs 880. The brokerage expects sustained volume-led growth, supported by the expansion of clinical teams and improving profitability at Sahyadri. It noted that Manipal plans to add 550-600 beds through FY28 and is also evaluating a new 500-bed hospital in Gurugram.
HSBC raised its FY27, FY28 and FY29 earnings estimates by 6.9%, 1.8% and 1.1%, respectively, saying capacity ramp-up and cost efficiencies remain key growth catalysts.
Jefferies also reiterated its 'Buy' recommendation and increased its target price to Rs 900 from Rs 870. The brokerage said volume-led growth remained strong during the September quarter, with Karnataka continuing to be a key contributor. Revenue and EBITDA growth were driven by higher patient volumes, better performance in core clusters and the scaling up of new facilities.
The brokerage highlighted that Sahyadri's margins improved by 200 basis points sequentially as integration efforts progressed, while the company's expansion pipeline remains on track. Reflecting the stronger outlook, Jefferies raised its FY27-FY29 EBITDA estimates by 2-3%.
Kotak Institutional Equities maintained its 'Add' rating and increased its target price to Rs 760 from Rs 730. The brokerage described the quarter as a solid volume-led performance, supported by continued improvement in Manipal's CONGO-R mix, which now stands at around 64%, helping lift average revenue per occupied bed.
Kotak expects approximately 2,400 new beds to be added in the coming years, with nearly 40% of the additions concentrated in core markets. The brokerage also expects profitability improvements at acquired hospital networks, including AMRI, Medica and Sahyadri.
The brokerage forecasts revenue and EBITDA compound annual growth rates of about 17% and 20%, respectively, over FY26-FY29. It also noted that Manipal's relatively low oncology mix limits the impact of the government's 30% trade-margin cap on oncology drugs, though any future expansion of the cap to medical consumables remains a monitorable risk.
Overall, brokerages remain positive on Manipal Health's ability to sustain growth through capacity additions, improving occupancy levels and the successful integration of recent acquisitions, making it one of the preferred plays in India's hospital sector.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.