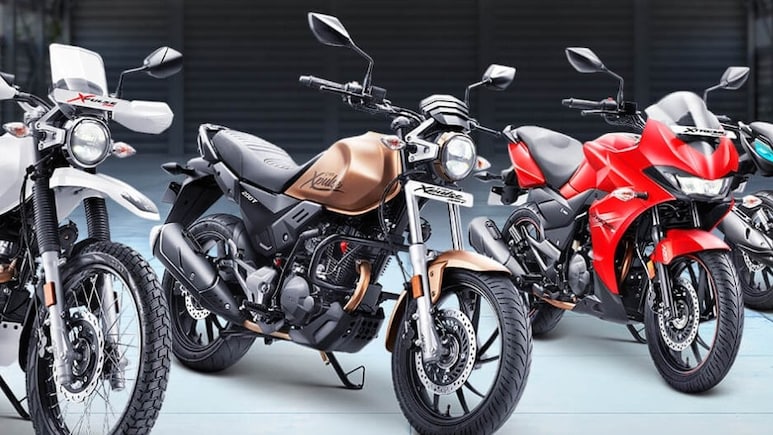
Hero MotoCorp Ltd. is expected to report double-digit revenue growth for the September quarter of fiscal 2027, supported by higher sales volumes. However, rising commodity costs could weigh on profitability and limit earnings growth, despite improving demand for two-wheelers.
Consensus Bloomberg estimates project standalone revenue to increase 19% year-on-year to Rs 14,481 crore from Rs 12,126 crore in the corresponding quarter last year. Net profit is expected to rise 7% to Rs 1,493 crore from Rs 1,393 crore.

-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 Silver Is Now Down From Rs 4.2 Lakh To Rs 1.9 Lakh: Where It Goes From Here
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Earnings before interest, taxes, depreciation and amortisation (Ebitda) are estimated to grow 6% to Rs 1,929 crore from Rs 1,823 crore. The Ebitda margin is expected to contract 170 basis points to 13.3% from 15% a year earlier.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The earnings estimates indicate that revenue growth may outpace operating profit growth as higher input costs offset some of the benefits from stronger volumes.
Hero MotoCorp's total sales increased 10% year-on-year to 18.6 lakh units in the July-September quarter, providing support to its revenue outlook. The volume growth is expected to help the company benefit from operating leverage, as higher sales can improve the absorption of fixed costs. However, the extent of this benefit will depend on the product mix, pricing and input cost movements.
Sequentially, margins are expected to remain broadly flat, according to the estimates provided. This would suggest that any operating leverage from higher volumes could be offset by commodity cost pressures.
READ | Bajaj Auto Q2 Results: Net Profit Up 35%; Revenue Beats Estimates
Hero MotoCorp had maintained its margin guidance of 14%-16% after its first-quarter results, despite input cost pressures. The company had indicated an approximate 4.5% impact from net commodity inflation and expected a marginal increase in input cost inflation in the second quarter of fiscal 2027.
The key question for investors is whether stronger volumes and favourable currency movements can offset the impact of higher commodity prices. Export-related foreign exchange benefits could provide some relief, although the overall effect will depend on the scale of cost increases during the quarter.
Management commentary on the pace of commodity inflation, pricing actions and the sustainability of demand will be important in assessing whether the company can maintain its full-year margin guidance.
BofA
Bank of America (BofA) sees scope for modest earnings upgrades for Hero MotoCorp, supported by volume strength in the two-wheeler market.
The brokerage expects two-wheeler industry growth of around 6%-7%, with some of the commodity cost headwinds potentially offset by currency benefits from exports. However, BofA highlighted several downside risks, including a lack of recovery in the entry-level segment, which could weigh on market share and disappoint if investor expectations continue to rise. A faster transition towards electric vehicles and an adverse outcome from the income tax investigation were also identified as risks.
On the upside, faster-than-expected growth in the two-wheeler industry and improved traction in newer product categories could support performance.
BofA's estimates indicate revenue growth of around 35% year-on-year, Ebitda growth of 6% and net profit growth of 12%. These projections are stronger than the broader consensus estimates for revenue and profit, highlighting differences in brokerage assumptions.
Citi
Citi expects Hero MotoCorp's gross margin to decline around 100 basis points sequentially because of higher commodity costs. At the same time, sustained volume growth could provide operating leverage and partly cushion the impact of input cost inflation.
READ | Ather Energy Sets Issue Price For Raising Rs 1,200-Crore From Hero MotoCorp, India-Japan Fund
The brokerage will also watch management's commentary on rural demand, which remains an important factor for two-wheeler sales. A sustained improvement in rural consumption could support demand, particularly in the entry-level segment.
What Investors Should Watch
Hero MotoCorp's September-quarter results will be assessed against the backdrop of stronger sales volumes and continued cost pressures. Investors will focus on whether the company can translate higher sales into improved operating earnings, despite the expected year-on-year contraction in margins.
The pace of recovery in entry-level motorcycles, rural demand trends, commodity prices and export-related currency benefits will be key factors. Management's assessment of the 14%-16% margin guidance and the outlook for the second half of fiscal 2027 could also influence expectations for the company's earnings trajectory.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.