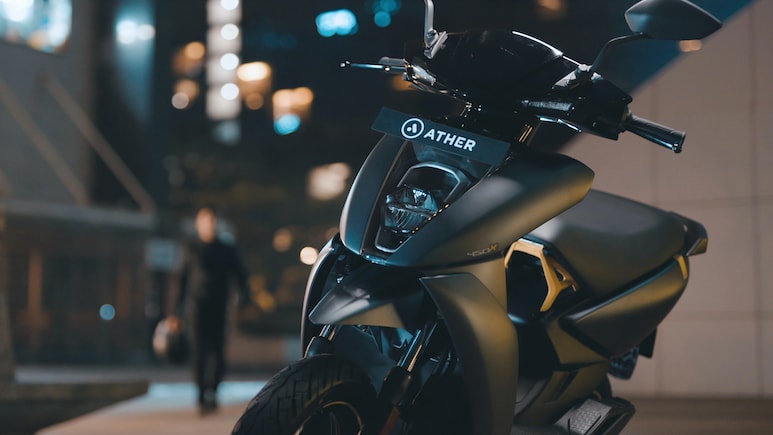
Ather Energy Ltd.'s Q2FY27 performance prompted Nomura and HSBC to raise their target prices while retaining buy ratings on the stock. Nomura threw the spotlight on better-than-expected average selling prices and margins, stronger bookings and greater growth visibility from Konarc while HSBC pointed to the company's surprise Ebitda break-even despite commodity headwinds and now expects profit-after-tax break-even in FY27.
Nomura increased its target price to Rs 2,070 from Rs 1,926 and reaffirmed Ather as its top pick in the two-wheeler sector. The brokerage said Konarc had improved visibility on growth, while stronger bookings were a key positive. The current market price is 1,674.00 and Nomura's target price implies an upside of 23.66%.

-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 Silver Is Now Down From Rs 4.2 Lakh To Rs 1.9 Lakh: Where It Goes From Here
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Ather's Q2 average selling prices and margins exceeded consensus estimates, according to Nomura. The brokerage said the drivers for an inflection in electric vehicle adoption were in place.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Nomura also said future stock returns were likely to depend increasingly on the salience of electric vehicles within original equipment manufacturers' businesses. Its assessment places Ather's growth prospects and exposure to electric vehicles at the centre of its investment view.
What Is HSBC saying?
HSBC raised its target price to Rs 1,800 from Rs 1,600, describing the second quarter as another positive surprise. At the current market price of 1,674.00, the target price implies an upside of 7.53%.The brokerage said Ather's unexpected break-even at the earnings before interest, tax, depreciation and amortisation level, despite demanding commodity headwinds.
That operational resilience should further improve market confidence in Ather's ability to scale over the long term, HSBC said. It now expects the company to break even at the profit-after-tax level in the financial year 2027.
However, HSBC identified a muted response to Konarc as a near-term risk, placing the product's reception among the factors to watch.
The two brokerages' assessments put Konarc in focus from different perspectives: Nomura cited it as a source of greater growth visibility, while HSBC flagged the risk of a muted response. Both retained positive recommendations after the quarterly performance, although Nomura's revised target points to a larger potential gain than HSBC's at the stated market price.
Ather Q2FY27 Results
Ather Energy Ltd. reported its first-ever positive earnings before interest, tax, depreciation and amortisation (Ebita) and net profit in the September quarter, marking a significant milestone for the electric two-wheeler maker as revenue growth strengthened.
The company's consolidated revenue rose 62.8% year on year to Rs 1,464 crore in Q2, compared with Rs 899 crore in the corresponding quarter last year. Net profit stood at Rs 1.3 crore against a loss of Rs 154 crore a year earlier.
Ebitda came in at Rs 11 crore, compared with an Ebitda loss of Rs 132 crore in the year-ago quarter. The Ebitda margin stood at 0.75% in quarter ended September.
ALSO READ | Vijay Shekhar Sharma Calls Ather's Lethal' Scooter Testing Idea Brilliant: Wonder If Buyers Know It Yet'
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.