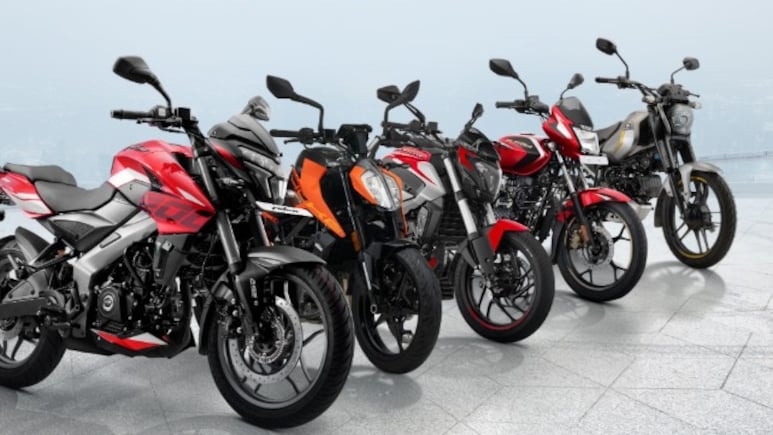
Bajaj Auto Ltd.'s Q2 FY27 performance demonstrates the strength of its export franchise, premium motorcycle portfolio and three-wheeler leadership, while the EV business is progressing towards stronger profitability, says Systematix. Near-term earnings resilience has been supported by pricing, favorable currency realisations, operating leverage and PLI income despite unusually high input-cost inflation. Looking ahead, sustaining export momentum, converting capacity additions into higher volumes and reducing EV costs ahead of PLI expiry will be critical to sustaining earnings growth.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.

-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 Silver Is Now Down From Rs 4.2 Lakh To Rs 1.9 Lakh: Where It Goes From Here
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Motilal Oswal Report
According to Systematix, Bajaj Auto Ltd.'s Q2 FY27 performance demonstrates the strength of its export franchise, premium motorcycle portfolio and three-wheeler leadership, while the EV business is progressing towards stronger profitability.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Near-term earnings resilience has been supported by pricing, favorable currency realisations, operating leverage and PLI income despite unusually high input-cost inflation.
Looking ahead, sustaining export momentum, converting capacity additions into higher volumes and reducing EV costs ahead of PLI expiry will be critical to sustaining earnings growth.
Post Q2 FY27 result, the brokerage broadly maintains its earnings estimate for FY27E/FY28E and retain Buy rating on the stock with target price of Rs 12,498 from earlier Rs 12,425.
A slight change in price target is attributed to change in valuation of its strategic investments in Bajaj Mobility AG.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.