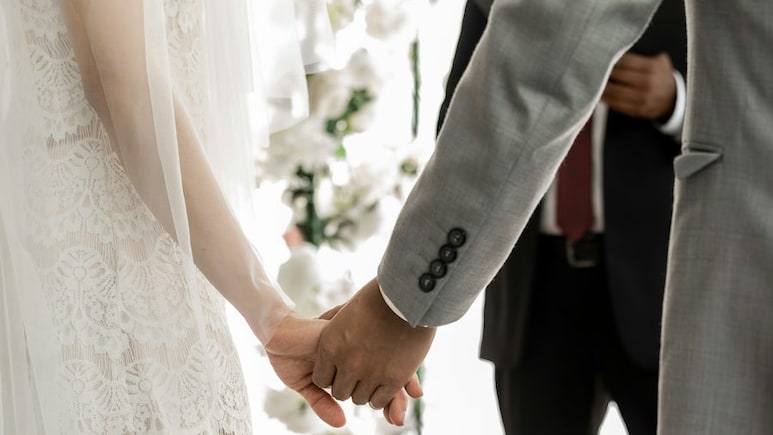
An investor has sparked discussion on social media after jokingly suggesting that he was looking to marry someone with more than $150,000 in capital gains to offset an equivalent amount of capital losses and potentially reduce their tax liability.
In a post on X, the investor wrote, "Does anybody with $150K in capital gains want to get married this year? I have $150K in capital losses and we can offset them and keep the gains tax free."

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
The post highlights the US federal tax system, under which married couples filing jointly can combine their income, capital gains and capital losses on a single tax return. Accordingly, tax-saving opportunities for married taxpayers depend heavily on their filing status.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Does anybody with $150K in capital gains want to get married this year? I have $150K in capital losses and we can offset them and keep the gains tax free.
— UnstructuredCap (@UnstructuredCap) November 5, 2026
Can Married Couples Offset Each Other's Capital Gains and Losses?
In cases involving joint tax returns, one spouse's capital losses can offset the other spouse's capital gains for the same tax year.
For instance, if one spouse records $150,000 in capital gains while the other reports $150,000 in capital losses, the combined figures could potentially cancel each other out, leaving no net capital gain from those transactions.
However, couples who choose to file separately generally cannot combine their individual capital gains and losses in the same way. Each spouse must report their individual financial transactions on a separate tax return.
What Happens When Capital Losses Exceed Gains?
The US tax system also allows taxpayers to use excess capital losses to offset up to $3,000 of ordinary income annually, or $1,500 for married individuals filing separately.
Any remaining unused capital losses can generally be carried forward to future tax years, subject to applicable tax rules.
Why Marriage for Tax Benefits Is Not That Simple
Although the investor's post appears to suggest an interest in marriage driven more by financial considerations than emotional bonding, marrying someone solely to benefit from a tax offset involves several legal and financial considerations.
ALSO READ | Protein Shakes At Theatres? At Select PVR INOX Cinemas, They'll Cost Less Than Cold Drinks
Filing jointly combines a couple's financial reporting, potentially making both partners liable for shared tax debts and triggering a so-called "marriage penalty".
While this allows one spouse's capital losses to offset the other's gains, marriage alone does not make investments tax-free. Actual tax savings depend on individual circumstances and applicable federal tax rules.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.