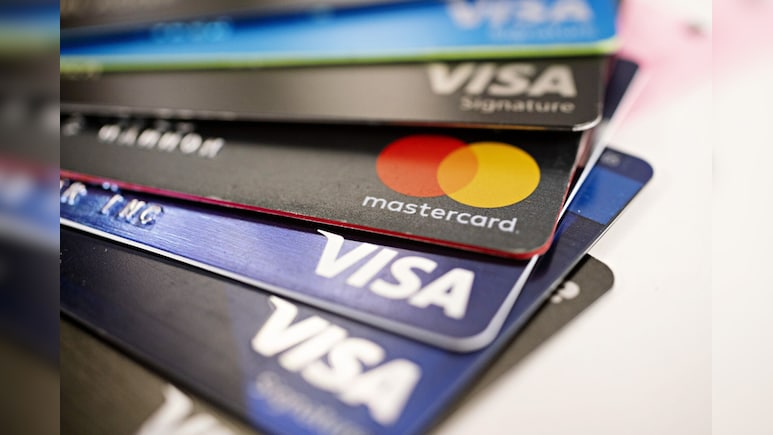
A shopping credit card, a travel rewards card and another offering online shopping discounts can quickly add up to three or more cards in your wallet, each with its own billing cycle and payment due date.
While multiple credit cards can help build your credit history and improve your credit utilisation ratio, managing several cards can also increase the risk of missed payments and mounting debt. Ultimately, their impact on your credit score and finances depends on how responsibly you use and manage them.

-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 Silver Is Now Down From Rs 4.2 Lakh To Rs 1.9 Lakh: Where It Goes From Here
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Also Read: 'What Will You Do By Knowing?' How To Break The Silence Around Mothers And Wealth in Our Homes
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
How Three Credit Cards Can Help
Consider Rahul, who has three credit cards, each with a credit limit of Rs 50,000. This gives him a total credit limit of Rs 1.5 lakh. If he spends Rs 30,000 across the three cards, his credit utilisation ratio stands at 20%.
A lower credit utilisation ratio can help improve his credit score, provided he pays his dues on time. Having multiple cards can also help him maximise benefits such as cashback on groceries, travel reward points and discounts on online shopping.
However, a higher combined credit limit does not automatically translate into a better credit score. His repayment history, outstanding balances and overall credit management also play an important role.
When Multiple Cards Become a Problem
And what if Rahul misses the deadline to pay for the second credit card because he forgot about it? Even though Rahul pays all the other bills on time, missing a single payment will affect his credit score.
If Rahul starts buying things he cannot afford and pays only the minimum amount, interest rates will make the total amount bigger. Over time, this can put pressure on his monthly budget. The annual fee on multiple cards can reduce his rewards.
Should You Keep All Three Cards?
Before closing a card, check its annual fee, benefits, and effect on your overall credit utilisation. Closing a card can reduce your available credit and may affect your credit score.
If you can manage all three cards comfortably, there is no need to close one just because you have multiple cards.
Also Read: Dhanteras 2026: How To Check Gold Purity And Verify BIS Hallmark Before Buying
Three credit cards can work in your favour, but only when you control your spending, pay your bills on time, and keep your balances manageable. Remember, the goal is not to own more credit cards; it is to use credit wisely.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.