While the management expects H2 FY27 to be better than H1, the brokerage remain cautious about the sustainability of growth, given continued softness in European automotive demand and delays in deal closures. Transportation accounts for over 55% of the SDS segment, making the recovery in automotive spending critical to the company's growth trajectory. Further, Ebit margin at 19.7% was supported partly by cross-currency benefits and the reversal of previous one-off costs.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Nirmal Bang Report
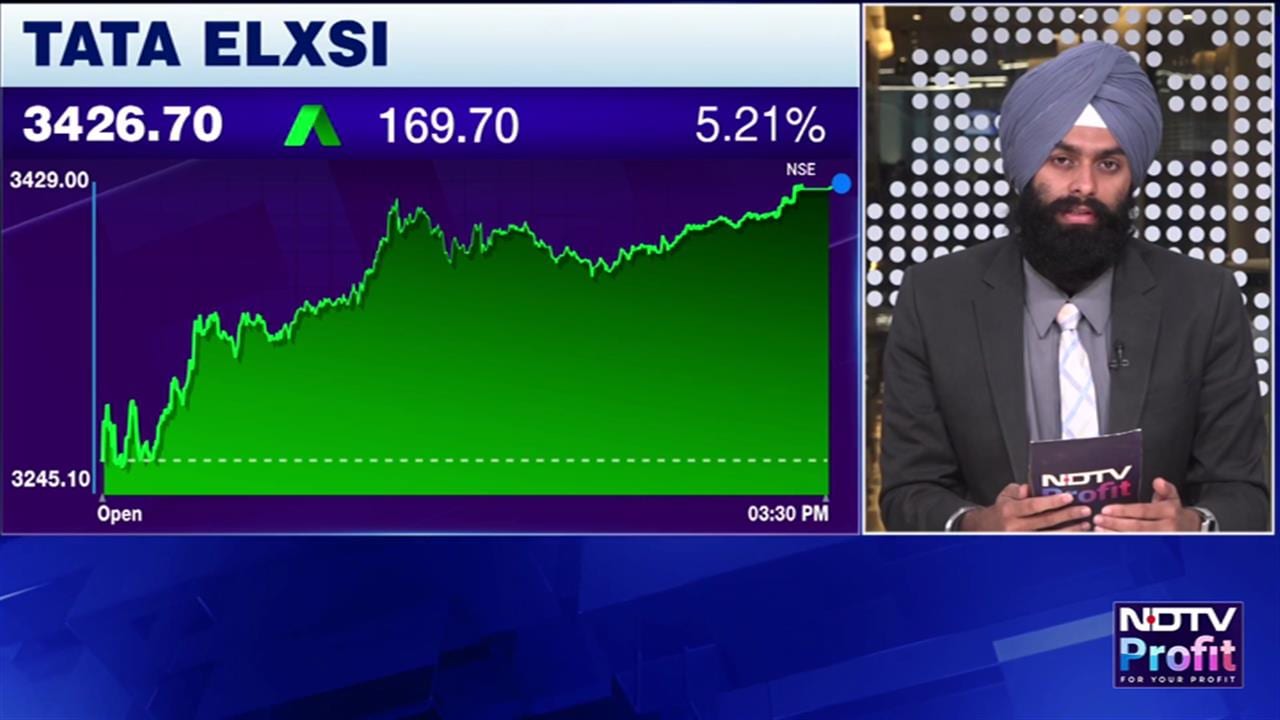
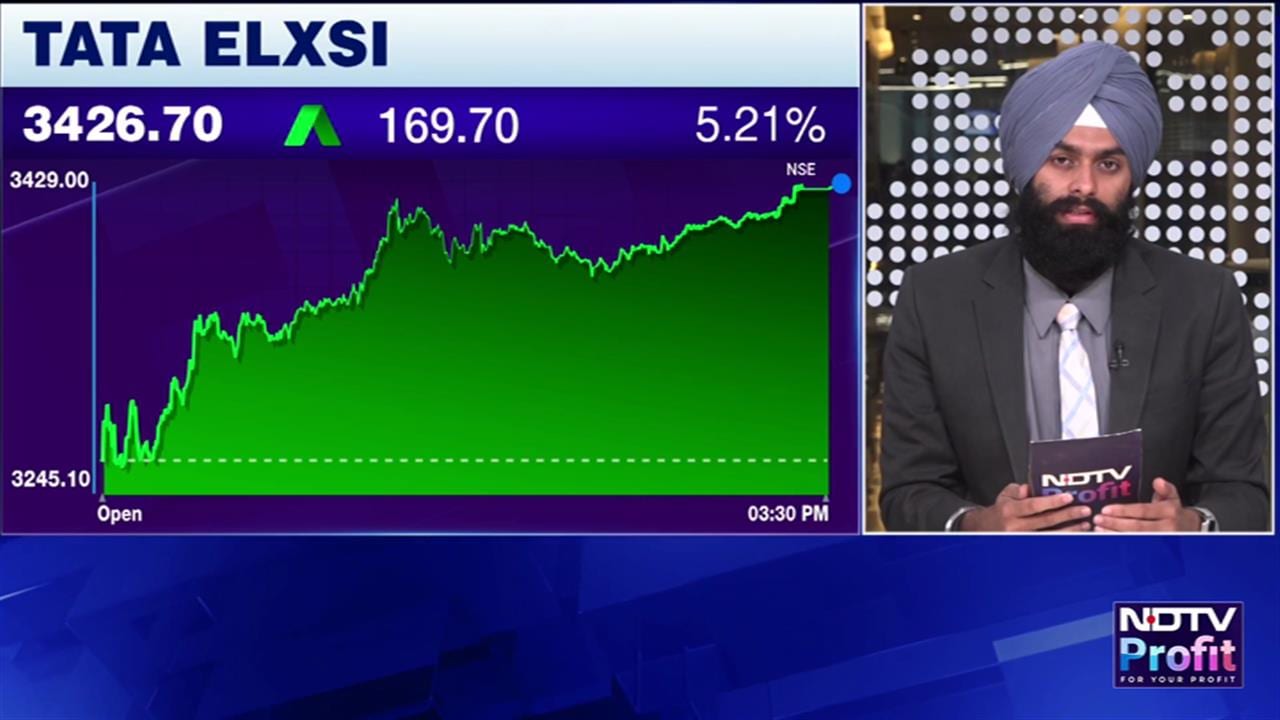
Following Tata Elxsi Ltd.'s September-ending quarter results, Nirmal Bang has reiterated its ‘Hold' rating on the stock, valuing it at an unchanged 25 times blended earnings per share of Rs 153, translating into a target price of Rs 3,825.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
According to the brokerage, Tata Elxsi delivered a sequential recovery in Q2 FY27, with revenue growing 2.3% QoQ and 7.8% YoY on a CC basis, supported by broad-based growth across its key verticals.
While the management expects H2 FY27 to be better than H1, the brokerage remain cautious about the sustainability of growth, given continued softness in European automotive demand and delays in deal closures.
Transportation accounts for over 55% of the SDS segment, making the recovery in automotive spending critical to the company's growth trajectory. Further, Ebit margin at 19.7% was supported partly by cross-currency benefits and the reversal of previous one-off costs.
While the management expects gradual margin improvement through H2, the sustainability of operating leverage remains a key monitorable.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.