Brokerages have highlighted opportunities across pharma, power, exchanges, healthcare, auto ancillary, housing finance, and renewable energy sector issuing fresh calls on Lupin, Dabur, Niva Bupa, Torrent Power, BSE, Lenskart, Emmvee Photovoltaic Power, Glaxo Smith Kline Pharma, Aurobindo Pharma, Balkrishna industries, Varroc Engieering, Dr. Lal Pathlabs, Anthem Biosciences, Samhi Hotels, Apollo Hospitals, Apollo Tyres, Aptus Value, Endurance Technologies, Exide Industries, Abbott India, alongside a broader view on India strategy and US Midterm Elections.
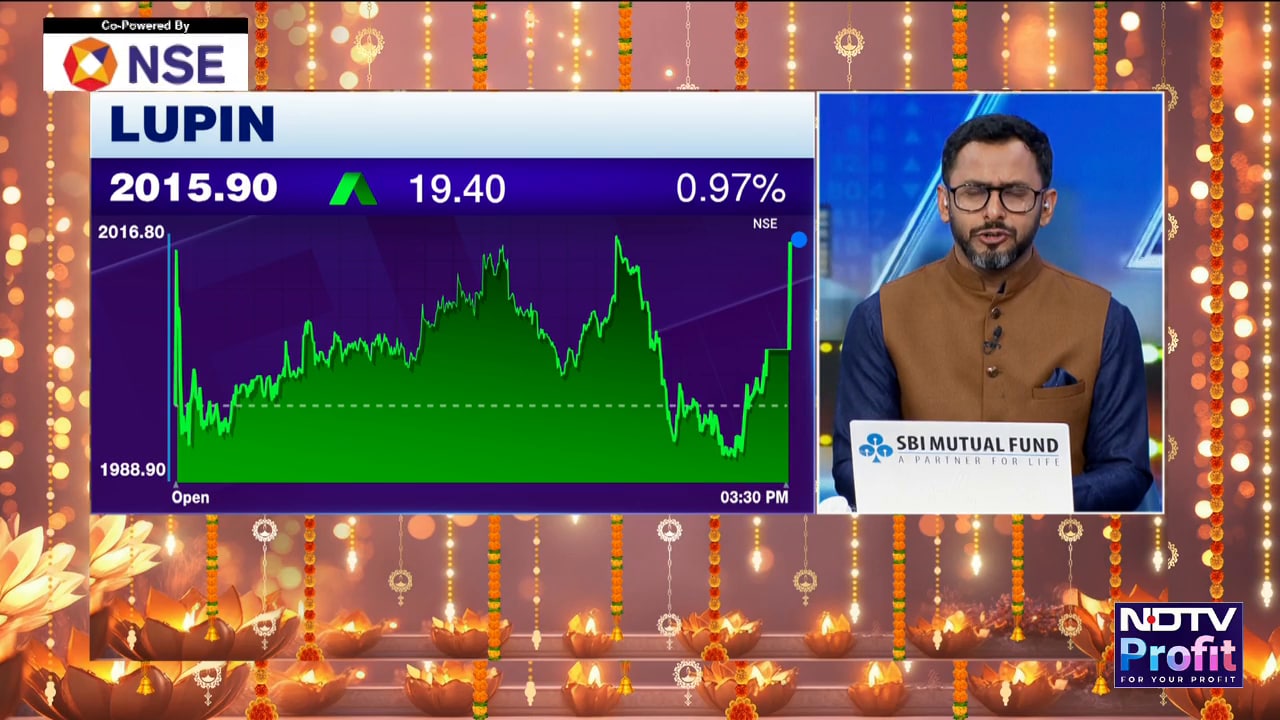
Jefferies on Lupin
- Maintain Underperform; cut TP to Rs 1,750 from Rs 2,050
- US sales expected to decline as competition intensifies for Mirabegron and Tolvaptan
- Key respiratory, injectable and biosimilar launches unlikely to contribute meaningfully before FY29
- Cuts FY27–28 EPS estimates by 5% and 1%; maintains FY27 EBITDA margin guidance of 24–25%.
Kotak on Lupin
- Maintain Add; TP at Rs 2,335
- India formulations expected to outperform industry growth by 1.2–1.3x
- US competition in Tolvaptan and Mirabegron to pressure near-term profitability
- Respiratory generics, biosimilars and Ellipta launches could drive stronger recovery from FY30
Jefferies on Dabur
- Maintain Buy; cut TP to Rs 535 from Rs 610
- CEO Mohit Malhotra's resignation puts upcoming management strategy in focus
- Rural demand recovery, premiumisation and Project Saksham support medium-term growth
- Healthcare faces regulatory challenges; cuts earnings estimates by 1–4% amid cost pressures.
Citi on Dabur
- Maintain Sell; hike TP to Rs 380 from Rs 375
- Leadership transition puts future strategic priorities under focus
- Premiumisation, stronger core brands and general trade recovery support growth
- Sustainability of earnings recovery remains uncertain despite improving business momentum.
Goldman Sachs on Dabur
- Maintain Neutral; TP at Rs 485
- Premium brands growing 4x faster than regular brands, supporting premiumisation
- Hair care, digestives and beverages remain key growth drivers
- CEO transition, rising costs and honey demand recovery remain key monitorables.
HSBC on Dabur
- Maintain Hold; TP at Rs 426
- Leadership transition puts future strategic direction under focus
- General trade recovery, hair care and beverages support domestic growth
- Honey demand disruption and rising operating expenses remain key concerns
Macquarie on Dabur
- Maintain Neutral; TP at Rs 480
- Premium brands growing 4x faster than regular brands support portfolio premiumisation
- Beverages, digestives and international markets offer growth opportunities
- Limited volume acceleration, FSSAI-related risks and CEO transition constrain outlook.
Jefferies on Torrent Power
- Maintain Buy; cut TP to Rs 1,635 from Rs 1,780
- Targets 10 GW renewable capacity by FY30; plans 1–1.2 GW additions in FY27
- Expects 13% EBITDA CAGR through FY30, driven by 35% growth in renewable EBITDA
- Transmission bottlenecks and execution delays remain risks; pumped storage offers additional potential
Jefferies on Niva Bupa
- Maintain Buy; hike TP to Rs 100 from Rs 95
- Strong retail health growth and market-share gains support business expansion
- Improving claims ratios, channel diversification and new products strengthen profitability outlook
- Hikes FY28–29 earnings estimates by 5–12%; distribution regulations and solvency remain monitorables
Jefferies on BSE
- Maintain Underperform; hike TP to Rs 3,100 from Rs 2,840
- Options market-share gains may become harder; expects 12–15% trading volume growth over FY28–29
- Cash equity market share remains below management's double-digit target
- Premium valuation versus NSE and management transition by June 2027 remain key concerns.
ALSO READ | Five Stocks To Buy Today, November 5: HPCL, Bajaj Finance, HAL, And More
Jefferies on Aptus Value Housing Finance
- Maintain Buy; cut TP to Rs 290 from Rs 350
- Expects 20% AUM growth in FY27 against management guidance of 22%
- Rising stress in NBFC subsidiary and higher borrowing costs could pressure margins
- Cuts FY27–28 EPS estimates by 1–3%; attractive valuations and 19–20% ROE support outlook.
Citi on Aptus Value Housing Finance
- Maintain Buy; cut TP to Rs 285 from Rs 350
- Cuts FY27–29 AUM growth forecasts to 20–21% amid slower disbursements
- NBFC asset-quality stress and higher funding costs pressure profitability
- Expects growth recovery by Q4FY27; management retains above-20% ROE guidance.
Jefferies on Lenskart
- Maintain Buy; hike TP to Rs 780 from Rs 680
- Hustlr Club targets the next 100 million Indians; premium evolv stores expand customer reach
- Smart glasses and Hyderabad manufacturing facility offer new growth opportunities
- Targets 25% long-term EBITDA margin without a timeline; currency pressures remain a risk.
Jefferies on Nykaa
- Maintain Buy; hike TP to Rs 415 from Rs 400
- Beauty premiumisation, customer acquisition and own brands remain key growth drivers
- Nykaa Now targets over 25 cities by FY27-end; fashion targets high-single-digit EBITDA margins by FY30
- Simply Nam acquisition and L'Oréal partnership expand beauty portfolio; hikes FY28–29 EBITDA estimates by 5–6%.
BofA on Nykaa
- Maintain Neutral; hike TP to Rs 400 from Rs 370
- Beauty growth supported by customer acquisition, premiumisation and repeat purchases
- Nykaa Now and advertising income offer additional growth opportunities
- Fashion marketing efficiency to improve margins, though premium valuations limit rerating
Kotak on Varroc Engineering
- Maintain Reduce; TP at Rs 740
- EV orders, polymer products and overseas expansion to support growth ahead of industry
- Lighting competition and limited e-mobility OEM diversification remain key risks
- Margin recovery likely to remain subdued amid pricing pressure and slower overseas ramp-up
Kotak on Dr Lal PathLabs
- Downgrade to Add from Buy; TP at Rs 2,300
- Hikes FY27 revenue growth guidance to high teens from mid teens
- Network expansion, rural penetration and Suburban turnaround support volume growth
- Expects 17% adjusted EPS CAGR through FY29, aided by specialty diagnostics and genomics.
Citi on Dr Lal PathLabs
- Maintain Buy; hike TP to Rs 2,380 from Rs 2,160
- Management targets high-teens FY27 revenue growth and sustainable mid-teens organic growth
- Network expansion and specialized diagnostics support sustained volume growth
- Genomics, oncology and preventive testing to improve revenue mix and profitability.
Goldman Sachs on Dr Lal PathLabs
- Maintain Sell; hike TP to Rs 1,750 from Rs 1,700
- Management hikes FY27 revenue growth guidance to high teens and EBITDA margin guidance above 28%
- Preventive diagnostics, better test mix and higher realisations support earnings growth
- Hikes FY27–29 estimates by up to 4%, but expensive valuations limit attractiveness
Kotak on SAMHI Hotels
- Maintain Buy; cut TP to Rs 235 from Rs 240
- Targets 14–15% same-store RevPAR growth in 2HFY27 on strong domestic demand
- Plans 1,669 additional rooms by FY31 and repositioning of 473 rooms into upper-upscale segment
- Expects leverage below 3x by FY27-end, with expansion largely funded internally.
Citi on Anthem Biosciences
- Maintain Buy; hike TP to Rs 1,030 from Rs 870
- Targets double-digit FY27 growth, supported by commercial molecule ramp-up
- Unit 4 commissioning targeted around March 2028 with Rs 12 bn planned capex
- Strong late-stage pipeline, pharma relationships and efficiency gains support margin outlook.
Citi on Apollo Hospitals
- Maintain Buy; TP at Rs 10,770
- Hospital expansion pipeline exceeds 4,700 beds, supporting medium-term growth
- HealthCo digital turns cash-positive; restructuring and listing targeted for Q4FY27
- Oncology trade-margin caps and hospital pricing regulations remain key risks
Citi on Apollo Tyres
- Maintain Buy; cut TP to Rs 500 from Rs 510
- Strong India demand and cost optimization support earnings resilience
- European operations face weak demand and persistent margin pressure
- Cuts earnings estimates as higher raw material costs offset domestic revenue growth
Citi on Aurobindo Pharma
- Maintain Sell; TP unchanged at Rs 1,270
- Lannett integration and injectable launches support US business expansion
- European growth faces sustainability risks from market saturation and pricing pressure
- US growth likely to moderate as acquisition and currency benefits normalize.
ALSO READ | Stock Market Today: All You Need To Know Before Going Into Trade On November 5
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
Citi on Balkrishna Industries
- Maintain Sell; TP unchanged at Rs 2,150
- Strong demand across India, Europe and Americas supports volume growth
- Commodity inflation and adverse product mix likely to pressure margins
- Cuts FY27–29 earnings estimates despite stronger revenue outlook
Citi on Lenskart
- Maintain Neutral; hike TP to Rs 700 from Rs 650
- Store expansion, premium lenses and higher volumes support growth
- Operating leverage and in-house manufacturing should drive gradual margin improvement
- Premium valuations and tougher second-half comparisons limit rerating potential.
Citi on Varroc Engineering
- Maintain Sell; TP at Rs 640
- Recent order wins and Forsee acquisition expected to strengthen revenue growth and expand battery-pack business
- Plans to exit Italian two-wheeler lighting facility and shift selected production lines to Vietnam and Romania
- Margin pressure and rising debt remain concerns; recovery of input-cost inflation from OEMs is a key monitorable
Jefferies on Zydus Lifesciences
- Maintain Buy; hike TP to Rs 1,430 from Rs 1,370
- Saroglitazar awaits US FDA decision in November 2026, with commercial launch targeted for March 2027
- US specialty portfolio, exclusive launches and differentiated Indian products expected to sustain growth
- Retains North America mid-single-digit growth guidance and consolidated EBITDA margin guidance above 24%.
BofA on Zydus Lifesciences
- Maintain Neutral; TP at Rs 1,200
- gAdempas and gIbrance launches to support US growth in FY28
- Saroglitazar US launch targeted for March 2027, with meaningful traction expected after FY29
- US commercialisation spending and elevated R&D costs likely to pressure margins.
Kotak on Endurance Technologies
- Maintain Add; cut TP to Rs 2,825 from Rs 3,000
- Stricter safety regulations and expansion into four-wheelers and EV components support multi-year growth
- ETL 2.0 strategy targets aerospace, defence and other non-automotive opportunities
- European consolidation could drive market share gains, but commodity pressures may delay margin recovery
Goldman Sachs on Endurance Technologies
- Maintain Neutral; cut TP to Rs 2,650 from Rs 3,090
- Expects meaningful margin recovery in FY28 as greenfield expansion start-up costs moderate
- Exploring aerospace, defence, data centres, robotics, railways, solar and power-backup opportunities
- Higher depreciation, financing costs and raw-material pressures prompt cuts to FY27–29 earnings estimates
Jefferies on Anthem Biosciences
- Maintain Buy; TP at Rs 1,050
- Expects another 1–2 late-stage molecules to transition to commercial manufacturing over the next 12 months
- Expanding relationships with global pharmaceutical companies strengthen its CRDMO growth pipeline
- Plans Rs 12 bn capex, including fermentation expansion and new fill-and-finish capabilities for biologics
Jefferies on Emmvee Photovoltaic Power
- Maintain Buy; TP at Rs 430
- Expects domestic solar module demand of 70 GW in FY27, supported by cheaper renewable power and government schemes
- Expanding cell capacity to 8.9 GW and module capacity to 16.3 GW; targets 9 GW ingot-wafer integration by FY30
- Projects 34% EBITDA CAGR through FY29; disciplined order selection aims to protect margins amid rising competition
Bernstein on GSK Pharma India
- Initiate Outperform; TP at Rs 3,430
- Top pick among listed multinational pharma companies, supported by a strong global innovation pipeline
- Adult vaccines, specialty respiratory treatments and oncology launches expected to accelerate revenue growth
- Innovation-led portfolio expansion could drive high double-digit growth, with oncology sales reaching Rs 3.8 bn by FY28
Bernstein on Pfizer India
- Initiate Outperform; TP at Rs 4,424
- Global innovation pipeline and new specialty medicines expected to transform India's growth trajectory
- Hospital-focused therapies and preventive healthcare launches could support double-digit revenue growth
- Improving operating leverage and faster access to globally developed medicines underpin earnings recovery
Bernstein on Abbott India
- Initiate Market-Perform; TP at Rs 24,851
- Strong established brands and commercial execution support steady growth in the domestic pharmaceutical market
- Limited new-molecule pipeline constrains participation in India's innovation-led healthcare expansion
- Annual product launches have declined from 11 to five, with brand extensions accounting for 80% of launches
Citi on Exide Industries
- Maintain Buy; hike TP to Rs 560 from Rs 510
- Commissioned 6 GWh lithium-ion cell gigafactory in Bengaluru; customer qualification and commercial ramp-up remain key triggers
- Strong automotive OEM wins, replacement demand and solar adoption support continued business momentum
- European battery partnership expands export opportunities; cost optimisation and calibrated pricing support margins
Bernstein on US Midterm Elections – Impact on India - Venugopal Garre
- Retains Nifty target at 25,000; sees limited near-term gains from Democratic victory
- Democratic Congress could curb US spending and lower Treasury yields
- Falling US yields historically supported FII inflows into Indian equities
- Every 10 bps decline in US yields historically attracted US$950 mn in FII inflows
- Lower yields could strengthen the rupee and improve foreign investor sentiment
- AI investments and competing emerging markets may limit India's foreign inflows
- US political deadlock could trigger risk aversion and capital outflows
- Trump's tariffs on Russian oil buyers unlikely to change despite Democratic control
- Middle East tensions and elevated crude prices remain major risks for India
- H-1B restrictions may face resistance, but tighter immigration scrutiny likely to continue
- Indian IT faces US spending risks, with North America contributing over 55% of revenues
- Long-term market performance hinges on crude prices, external balances and earnings growth
JPMorgan on India Equity Strategy - Rajiv Batra
- Bullish on Indian equities amid falling crude prices, lower US yields and renewed FII interest
- Foreign investors reversing their India underweight could unlock US$115 bn in inflows
- Lower crude could support the rupee, ease inflation and improve corporate margins
- Expects small- and mid-caps to outperform large-caps on earnings growth
- Overweight Financials, Industrials, Healthcare, Materials and Consumer Discretionary; Underweight IT
- Private capex recovery gaining momentum across renewables, semiconductors, EVs and data centres
- India's peak electricity demand projected to reach 459 GW by FY36 from 271 GW
- Power transmission investment opportunity estimated at Rs 8 trillion
- MSCI India trades at a 13.4% discount to its 10-year average valuation
- Banks, real estate, insurance and materials offer attractive relative valuations
- Aviation, paints, cement, tyres and logistics among potential beneficiaries of cheaper crude
- El Niño and weak rainfall threaten rural demand and agricultural incomes
- AI disruption puts 80% of Indian IT services' existing revenue pool at contraction risk
- Higher global bond yields could trigger FII outflows and pressure equity valuations.
BofA on India Equity Strategy – US Midterms & AI Capex - Amish Shah
- Democratic sweep raises AI regulation risks and could slow US data-centre expansion
- BofA sees AI capex concerns as overdone, with slower investment reducing overcapacity risks
- US AI capex growing at 26% annualised real pace, raising overinvestment concerns
- US growth, inflation and Fed forecasts through 2028 remain unchanged
- State-level zoning and permitting restrictions pose bigger risks to AI infrastructure
- Political gridlock could increase US trade and foreign policy uncertainty
- India could benefit from lower AI exposure and reduced global technology volatility
- Lower US yields and weaker dollar could support FII inflows and stabilise INR
- Korea, Taiwan and Japan face greater risks from an AI investment slowdown
- India's limited participation in the AI rally could cushion a global technology correction
- Indian AI-capex exporters trade at expensive 47x forward P/E and 1.8x PEG
- ABB India, Siemens and Cummins India face risks from slower US data-centre orders
- Maintain Underweight on AI-linked Industrials and Capital Goods exporters
- Maintain Overweight on Cables given limited US data-centre export exposure
- Prefer Financials, Real Estate, Autos and Regulated Utilities on potential RBI rate cuts
Disclaimer: The views and opinions expressed by the investment advisers on NDTV Profit are of their own and not of NDTV Profit. NDTV Profit advises users to consult with their own financial or investment adviser before taking any investment decision.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.