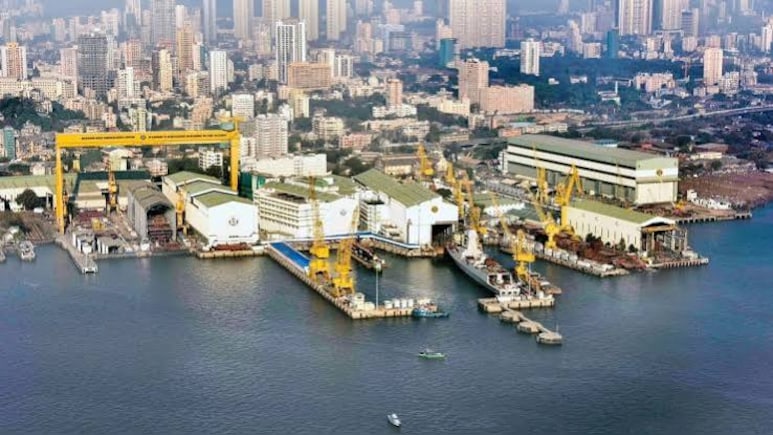
Mazagon Dock Shipbuilders' September quarter earnings disappointed brokerages, with weaker execution and higher provisions weighing on profitability. Kotak Neo and HSBC have cut their target prices on the stock, while Goldman Sachs has retained its Sell rating, pointing to the risk of continued earnings weakness and subdued stock performance until fresh order inflows materialise.
Brokerages remain watchful of the timing of the P75I submarine order, which could support sentiment and strengthen the company's order pipeline. However, the revenue benefits from the potential order may take time to come through, leaving near-term earnings under pressure.

-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 Silver Is Now Down From Rs 4.2 Lakh To Rs 1.9 Lakh: Where It Goes From Here
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Mazagon Dock Shipbuilders Q2 Results: Key Highlights
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
- Net profit: Fell 54.1% YoY to Rs 344 crore from Rs 750 crore.
- Revenue: Declined 16.5% YoY to Rs 2,446 crore from Rs 2,929 crore.
- Ebitda: Dropped 71.4% YoY to Rs 199 crore from Rs 695 crore.
- Ebitda margin: Contracted 1,560 basis points to 8.1% from 23.7%.
- Interim dividend: The company declared a dividend of Rs 5 per share for fiscal 2027, with November 3, 2026, as the record date.
Also Read: Mazagon Dock Q2 Results: Profit Falls 54%, Margins Contract Sharply To 8.1%
What Brokerages Say On Mazagon Dock Shipbuilders
Kotak Neo: Maintain Sell, Cut Target Price To Rs 1,660
Kotak Neo has lowered its target price on Mazagon Dock Shipbuilders to Rs 1,660 from Rs 1,900, retaining its Sell rating.
- The brokerage attributed the weak quarterly performance to execution challenges and provisions, which affected earnings.
- The timely award of the P75I submarine order remains an important trigger for the stock.
- Despite the near-term concerns, the company continues to have a strong order pipeline.
HSBC: Maintain Reduce, Cut Target Price To Rs 1,680
HSBC has reduced its target price to Rs 1,680 from Rs 1,860 and maintained its Reduce rating after the company significantly missed the brokerage's September quarter earnings estimates.
- HSBC continues to factor in the P75I submarine order into its fiscal 2027 expectations.
- However, the brokerage expects the revenue contribution from the order to take two to three years to materialise.
- While the order could improve investor sentiment, HSBC expects earnings to remain weak through fiscal 2027 to fiscal 2029.
Goldman Sachs: Maintain Sell, Target Price At Rs 1,855
Goldman Sachs has retained its Sell rating on Mazagon Dock Shipbuilders, with a target price of Rs 1,855.
- Its September quarter review points to a decline in earnings.
- The brokerage is awaiting fresh order inflows to provide greater clarity on the company's growth outlook.
- Until meaningful orders materialise, Goldman Sachs expects the stock's performance to remain subdued.
Also Read: Mazagon Dock Shares Tumble 10% As Q2 Profit Tanks 54%
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.