Coal India, the state-owned world's largest coal producer, reported weaker-than-expected September quarter earnings. However, brokerage firms remain largely constructive, citing strong thermal power demand, declining coal inventories at power plants and rising international coal prices as potential catalysts for earnings growth.
Morgan Stanley maintained its ‘Overweight' rating on Coal India, with a target price of Rs 480 per share. The brokerage described the quarterly performance as disappointing but believes the company is entering an earnings upgrade cycle.

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
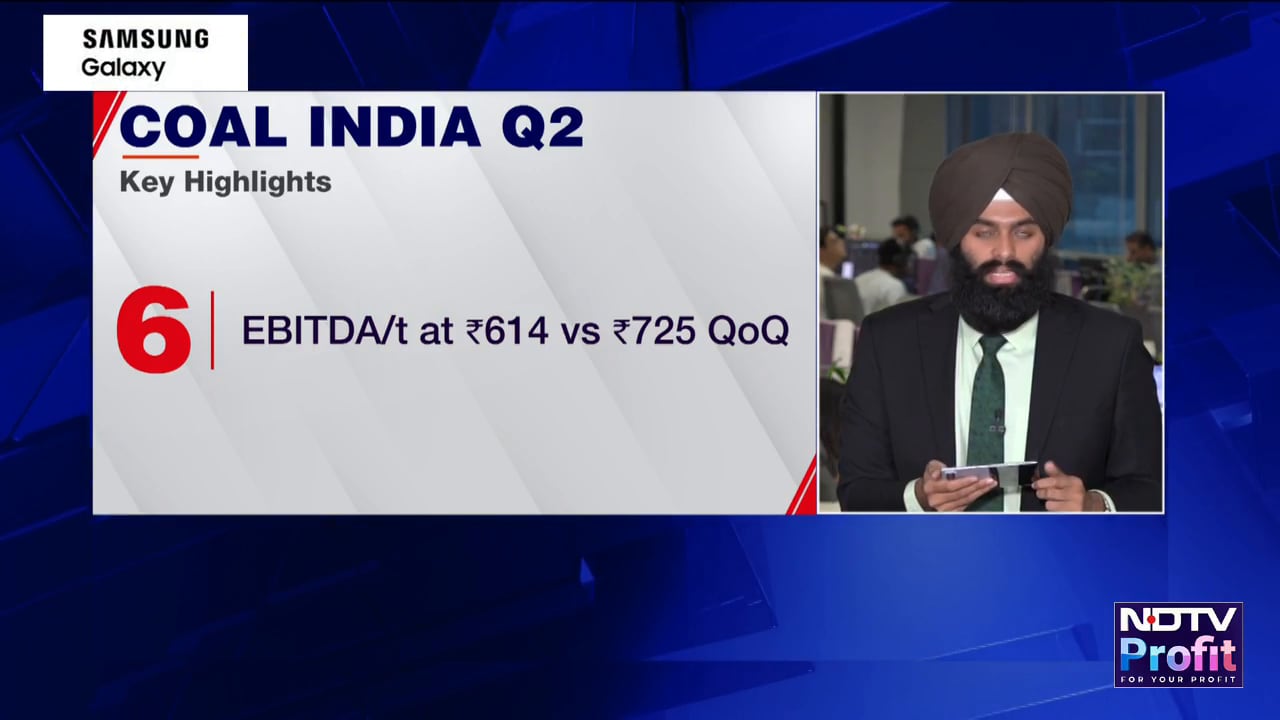
The brokerage highlighted a significant EBITDA miss, with adjusted EBITDA of around Rs 73.9 billion, approximately 37% below its estimates. Lower e-auction realisations and higher operating expenses weighed on profitability. However, FSA volumes grew 12% year-on-year, while realisations increased 4.4% sequentially.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Morgan Stanley believes Coal India's fundamentals remain favourable, supported by thermal power demand growth of around 8% year-on-year over the trailing 12 months. Coal inventories at thermal power plants have declined to around six days, their lowest level in five years. Rising international coal prices could also support higher e-auction premiums and realisations.
Jefferies maintained its ‘Buy' rating on Coal India but reduced its target price to Rs 460 from Rs 500. It highlighted a 29% year-on-year increase in Q2 cash EBITDA and a 53% jump in profit after tax, supported by 12% growth in dispatch volumes.
The brokerage expects a 7% earnings per share compound annual growth rate over FY26-FY29. A dividend yield of around 7% also supports its positive investment outlook.
Meanwhile, HSBC maintained its ‘Hold' rating and target price of Rs 440. While it sees potential for higher e-auction realisations and dividend payouts, it flagged medium-term concerns, including rising costs. HSBC forecasts a FY27 dividend of Rs 30.9 per share and believes potential subsidiary listings and stake sales could provide additional dividend upside.
Thus, while all three brokerages see support from improving coal demand and pricing, their differing views reflect concerns around costs and the sustainability of earnings growth.
ALSO READ: Godrej Consumer Q2 Review: Brokerages Flag Margin Pressure Despite Strong Volume Growth
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.