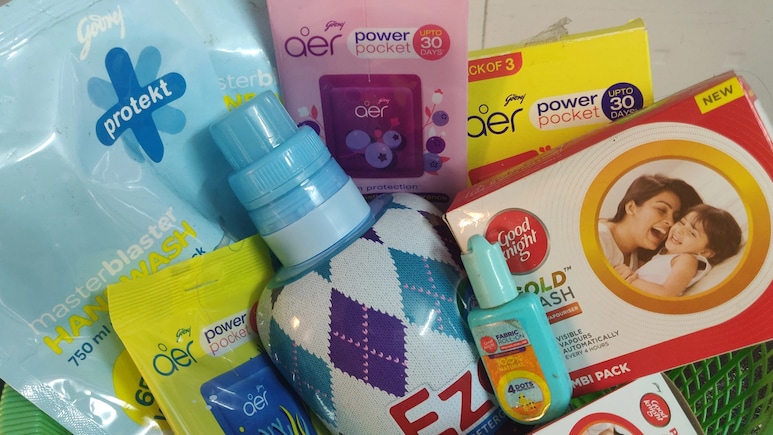
Godrej Consumer Products Ltd.'s September-quarter revenue was broadly in line with expectations, while EBITDA and net profit marginally missed estimates.
Consolidated volume growth stood at 8%, supported by home care and strong international performance, particularly in Indonesia and the Godrej Africa, USA and Middle East (GAUM) business. Brokerages remained divided on the outlook, with Goldman Sachs and Jefferies retaining Buy ratings, while HSBC maintained Hold. Analysts flagged rising commodity costs and pressure on profitability, even as volume growth remained healthy.
Godrej Consumer Q2 Highlights (YoY)
- Revenue rose 19% year on year to Rs 4,413 crore from Rs 3,708 crore.
- EBITDA increased 11.7% year on year to Rs 820 crore from Rs 734 crore.
- Net profit grew 13.9% year on year to Rs 523 crore from Rs 459 crore.
- EBITDA margin declined to 18.6% from 19.8% a year earlier.
- Consolidated volume growth stood at 8%, while India volume growth was 7%.
- Home care revenue increased 19%, while personal care revenue grew 8%.
- Gross margin contracted 300 basis points year on year.
Here's what brokerages are saying after Godrej Consumer announced Q2 results:
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
HSBC
- Maintained 'Hold'; Target Price At Rs 960
- Expects single-digit India volume growth and double-digit consolidated EBITDA growth in FY27.
- Said the company plans calibrated price increases in soaps and liquid detergents to offset rising commodity inflation.
- Cut FY28 margin expectations.
- Identified India profitability and management changes as key concerns.
Goldman Sachs
- Maintained 'Buy'; Target Price At Rs 1,030
- Said Q2 revenue rose 15.4% year on year, while EBITDA increased 11.8%, with margin at 18.6%.
- Highlighted 7% growth in India volumes.
- Noted that home care sales rose 19% despite inventory correction.
- Retained its FY27 expectations of high-single-digit India volume growth and double-digit consolidated revenue and EBITDA growth.
Jefferies
- Maintained 'Buy'; Target Price Cut To Rs 1,075 From Rs 1,400
- Said Q2 revenue grew around 19% year on year, while EBITDA increased 13%.
- Highlighted 7% growth in India volumes.
- Noted that home care grew 19%, while international business remained strong, led by Indonesia and GAUM.
- Cut FY27–FY28 earnings per share estimates by 3%, citing rising input costs.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.