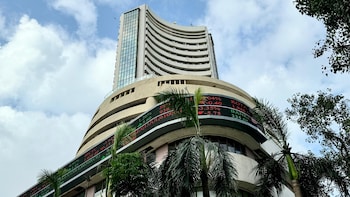

Brokerages have highlighted opportunities across NBFC, Indian stock exchanges, cement, pharma, healthcare, banks, power, FMCG and retail sector, issuing fresh calls on National Stock Exchange, BSE, Groww, Dalmia Bharat, Bajaj Finance, Varun Beverages, Piramal Pharma, Yes Bank, Vishal Mega Mart, CESC, Motilal Oswal, Manipal Health, India Shelter while also sharing their outlook on banks, NBFCs and insurance sector.
Macquarie on NSE
- Initiate Outperform with TP of Rs 1965
- View NSE as “The Dominator”, due to its leading market share and power
- Full set of services, technology stack and deep liquidity make NSE the lynchpin of India's financialisation
- Entrenched network effects, industry-leading profitability and cash, underpin positive outlook
- Platform expansion to drive revenues
- Near-term pressure from CAS, long-term industry outlook still constructive
- Superior fundamentals justify a premium multiple
- Room for further re-rating, if new products accelerate
Macquarie on BSE
- Initiate Outperform with TP of Rs 4000
- View BSE as “The Challenger” as its pivot to index options has made it a credible competitor to NSE
- BSE's platform expansion and share gains create revenue and margin optionality, supporting strong cash generation
- Earnings growth, margin expansion and platform optionality underpin positive outlook
- Riding India's financialisation wave
- Platform expansion to drive revenues; Structural margin tailwinds
- Near-term pressure from CAS, long-term industry outlook still constructive
- Room for further re-rating
Macquarie on MCX
- Maintain Outperform with TP of Rs 3820
- Deem MCX 'The Phoenix' as it has recovered from a near-death situation and leveraged its first-mover advantage to dominate commodity trading
- Despite a high FY26 base, MCX's low penetration of investors and products should evolve, driving highly visible growth and high margins
- Commodities is an under-penetrated opportunity in India
- MCX has built a deep moat and is improving its value proposition with new products broadening the base
- Revenue trajectory driven by increase in investors and products
Macquarie on Angel One
- Initiate Neutral with TP of Rs 285
- Consider Angel One a 'Transformer,' as it transitions from a "Bricks & Mortar" broker to a "Bricks & Clicks" model
- See several challenges due to increased competition, high earnings sensitivity to reduced volumes, and high proportion of float income
- Growth may become harder to achieve
Macquarie on Groww
- Initiate Outperform with TP of Rs 260
- See digital financial-services platform GROWW as a 'Disruptor' as it upends India's retail stock brokerage industry with its tech-first platform
- GROWW's platform-based approach creates flywheel benefits driving share gains, high margins, and significant cash generation
- Revenue trajectory driven by platform expansion
- Expect significant margin expansion
- Very constructive long term on the industry; near-term results to be impacted by CAS
ALSO READ: Four Stocks To Buy Today: Sona BLW, MCX, Deepak Fertilisers, And Marksans Pharma | Sept 24
Macquarie on India Insurance
- IRDAI takes an axe to distribution payouts
- Higher caps for tied agents over the banca and broker channel, rewarding selling effort over distribution leverage
- Pure-term life first-year commissions are capped at 25-30%
- EoM squeezed to 12.5% (life) and 20% (general) over five years
- LIC and SBI Life relatively insulated while PB Fintech most exposed
- Axis and HDFC Bank affected more than SBI, ICICI, and Kotak
HSBC on India Insurance
- IRDAI proposal upends traditional compensation models
- IRDAI proposes a broad redesign of insurance distribution and cost structure to improve insurance affordability and penetration
- Proposed EoM limits are stringent and, if implemented, can have a wide implication across insurers, brokers, and lenders
- Relatively, SBI LIFE appears least impacted while HDFCLIFE, MAX Financial and PB FINTECH could see higher potential impact.
Bernstein on Insurance
- UGLY commission cuts - we were wrong
- PB Fintech most impacted with varying impact on insurers
- Deep cuts in health, deferrals for term, motor goes to zero
- PB Fintech – unviable
- At this point, the real question is - does the regulator see PB Fin as a positive contributor to the insurance ecosystem or not? It does not seem like it
- The cuts are shaped in a way that pinch PB Fintech the most
- Insurers need to manage lower commission/total costs caps and growth
- Lower costs will be passed on to customers, bringing in some volume uptick
- These proposals will hurt the industry in the near-term, for sure; it could be a good step in the long-run
- LIC and SBI Life are better placed given their agency mix/ULIP mix and their lower cost structures
- Other life insurers will need to balance growth and commission/opex cuts.
Citi on Dalmia Bharat
- Maintain Buy with TP of Rs 2150
- To become a pan India player – entered Central India, next phase of expansion likely in the North
- To aim increase utilization in existing geographies
- Trying to reduce the gap vs. the highest price category A player
- Balance sheet – maintain Debt/EBITDA at <2x, rational capacity addition
- Indicated weak Q2 demand and pricing in East/North East
- Overall cost pressures worse than earlier expected.
Jefferies on Bajaj Finance
- Maintain Buy with TP of Rs 1280
- To seek shareholder approval to raise capital
- Leverage is manageable at 4.9x with healthy ROE of 21%, strong loan growth
- Staggered monetisation of 87% stake in Bajaj Housing & mgt succession in Mar-28 may have pushed the raising
- Assuming they raise 10% of FY28 net worth, it may be Rs 15000 cr
- This can lift FY28e EPS by 1%, BVPS by 7%, ROE tapers marginally
- Given strong growth & ROE, Bajaj Finance stays among top picks
GS on Piramal Pharma
- Maintain Buy with TP of Rs 250
- Reiterated their guidance of low to mid teen topline growth with faster EBITDA/PAT growth in FY27
- There is potential to be reviewed upwards after Q2
- Maintained medium term guidance of doubling company level revenue to $2bn with 25% margin by FY30, driven by a couple of large CDMO opportunities
- However, acknowledged that it could be a stretch
Citi on Yes Bank
- Maintain Sell with TP of Rs 22
- FCNR mobilization favored granularity and tenor diversification
- Excess FCNR liquidity and IBU leverage will temporarily weigh on margins
- MDR implementation is fee-accretive
- Credit costs stay anchored at 50 bps or less with no fresh stress
- Focused on improving core profitability excluding treasury and SR-related volatility
- AT1 verdict remains pending
- SMBC collaboration is gathering momentum across origination, best-practice exchange, and ecosystem access
Jefferies on Banks
- Tighter Commission Norms are Slight Earnings Risk for Banks
- Insurance regulator proposes to tighten caps on insurance commissions from FY28
- It has sought public opinion on draft norms over next month, and rules apply prospectively
- This will be tad negative for banks' bancassurance fees, esp credit-protect premiums, as it's mostly single premium with high commissions
- Based on FY26 banca commission/FY27 profit (normalised), IndusInd Bank and IDFC First have higher exposure, and ICICI and PSU Banks have lower risk
Citi on Banks and NBFCs
- The commission crunch
- For banks/NBFCs, adversely impacts bancassurance/credit-life economics
- It reduces insurance fee pools earned from credit-life, property, and related loan-linked insurance products
- Proposed caps compress loan-linked insurance commissions to as low as <5%
- It bans compulsory bundling, mandate direct premium payment from customer's own account and impose an ‘all-inclusive' definition of commission.
ALSO READ: NSE IPO Listing Live: Track Listing Price, Share Moves, Investor Response And Market Debut Updates
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Jefferies on Insurance
- IRDAI's Distribution Regulations: negative for Distributors; Neutral for Insurers
- IRDA's distribution consultation paper proposes stricter EOM limits for insurers
- Proposes 1/2-1/3rd commission cuts in health, term and motor insurance
- This is a risk for PB Fintech/Turtlemint; 10% cut in new business commission rates translate to 10-12% fall in their earnings
- On the other hand, any correction in SBI Life, Star Health and ICICI Lombard could be a BUYing opportunity
- See limited risks from the paper, share gain opportunities and scope to expand margins
Citi on India Shelter
- Maintain Buy with TP of Rs 1010
- Distribution recognition transition behind; sourcing aligned
- Asset quality – near term plateau and see H2 recovery
- Liability defenses intact; floating mix and AA upgrade runway buffer margins
- Calibrated expansion – scaling digital sourcing while staggering branch rollouts.
Kotak Securities on Manipal Health
- Initiate Add with TP of Rs 825
- Born in Bengaluru, built for India
- Repeatable M&A playbook and scaling in existing and new markets
- Financials: estimate robust ~16%/19% sales/EBITDA CAGRs over FY2026-29E
- Key risks: Any acquisition-related integration issues and lower RoCEs
CLSA on CESC
- Maintain Outperform with TP of Rs 204
- Emerging transition play
- 2x PAT by 2030 - achievable
- See combination of renewable scale-up, improving subsidiary profitability and a growing IPP portfolio, funded by distribution cashflows
- These positions CESC to deliver structurally higher earnings growth and returns.
ALSO READ: Stock Market Today: All You Need To Know Before Going Into Trade On Sept 24
CLSA on Varun Beverages
- Maintain High Conviction Outperform with TP of Rs 629
- Portfolio broadening supports growth; competition manageable
- Competition remains concentrated; Campa adjusts pack architecture
- Mix shifting toward Sting, Mountain Dew and emerging categories
- Indian snacks launch can leverage VBL's distribution reach
- Pricing, input costs and trade spends appear manageable
UBS on Motilal Oswal
- Maintain Buy with TP of Rs 1150
- Received SEBI approval as securities custodian
- Strategically positive, with a limited near-term impact on earnings
- License enhances MOFSL's institutional platform, creates cross-selling opportunities & provides exposure to a high-barrier-to-entry, recurring fee-income business.
- MOFSL remains top pick in capital markets
Jefferies on Vishal Mega Mart
- Maintain Buy with TP of Rs 160
- Analyst Meet Update - Show of Strength
- Maiden analyst day, exposed its mid-level mgmt., a first alongside CEO, popularly known as GK
- Vishal's value-for-money playbook is evolving with rising aspirations
- Mgmt. sees a long growth runway via store expansion, refurbishments, private labels, & quick commerce, while new formats expand TAM
- Despite heavy investments in tech, supply chain & automation, strong volumes and sourcing advantages underpin confidence in sustaining margins
MS on Vishal Mega Mart
- Maintain Overweight with TP of Rs 146
- Reiterated guidance of 100+ store openings annually for the current format stores, along with 4-5 openings per quarter for the smaller format stores
- Clear path to 2,000 stores for the current format; towns and locations have been identified for most
- On a full-year basis, the key goal remains double-digit SSSG
- This year's festive season is delayed to Q3, vs. 2Q last year
- Benefits of operating leverage from the 17-18% volume growth that the business has been showing will be invested back in the business
- Vishal is piloting a new fashion store in Delhi under a new brand name
- Vishal's online channel is at cash break-even.
Disclaimer: The views and opinions expressed by the investment advisers on NDTV Profit are of their own and not of NDTV Profit. NDTV Profit advises users to consult with their own financial or investment adviser before taking any investment decision.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.