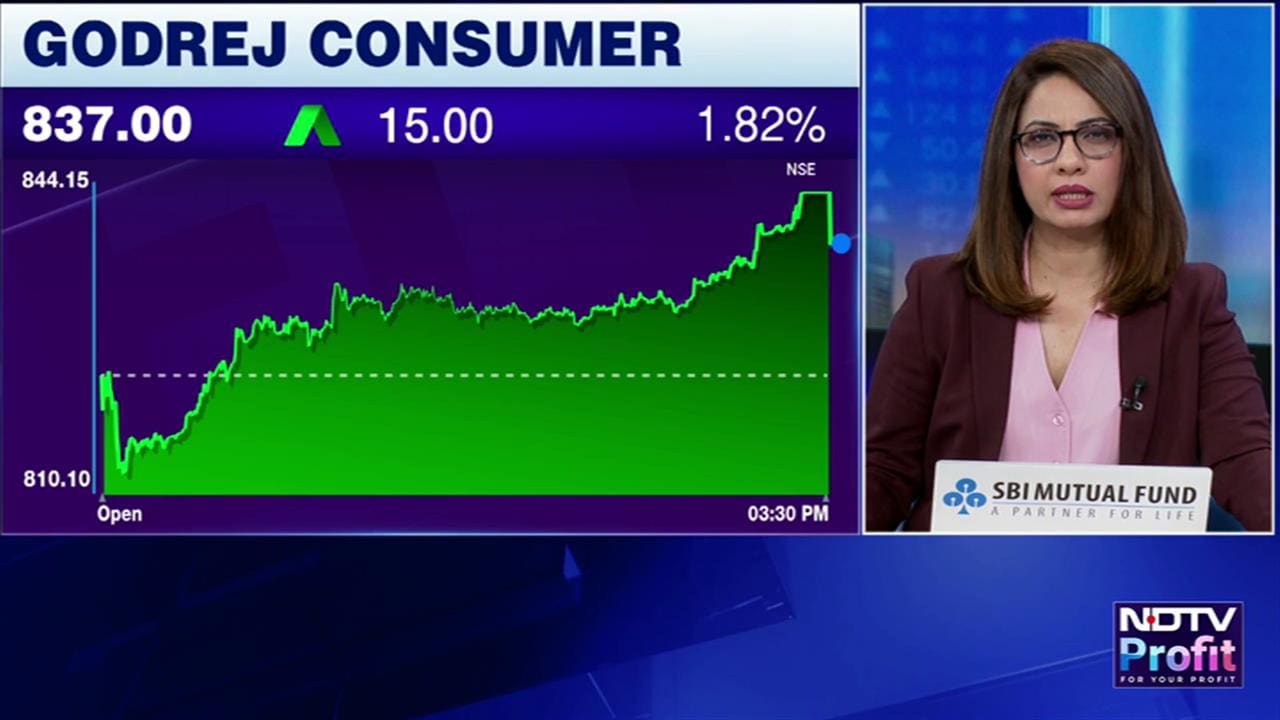
Shares of Godrej Consumer Products Ltd. fell 3.82% to Rs 805.05 on Friday after the company reported its September-quarter results. The stock opened at Rs 815 and dropped to an intraday low of Rs 777.20 before recovering some losses. It had closed at Rs 837 in the previous session.
The decline came despite 8% consolidated volume growth in the September quarter, as investors weighed pressure on margins against stronger sales. The stock was trading near its 52-week low of Rs 810.10, recorded on October 29, according to the data available on the trading screen.

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
Trading volumes were elevated, with 23.19 lakh shares changing hands by 9:30 a.m., against the 30-day average of 9.57 lakh shares. This was 2.42 times the average volume.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Godrej Consumer's revenue increased 19% year on year to Rs 4,413 crore, while EBITDA rose 11.7% to Rs 820 crore. Net profit grew 13.9% to Rs 523 crore. However, EBITDA margin declined to 18.6% from 19.8% a year earlier, while gross margin contracted 300 basis points.
The company reported 7% volume growth in India, with home care revenue rising 19% and personal care revenue increasing 8%. International businesses, particularly Indonesia and the Godrej Africa, USA and Middle East business, also supported growth.
What Brokerages Say
Brokerages flagged rising input costs and margin pressures despite the volume growth.
Jefferies retained its Buy rating but cut its target price to Rs 1,075 from Rs 1,400. The brokerage lowered its FY27–FY28 earnings estimates by 3%, citing higher input costs.
Goldman Sachs maintained its Buy rating with a target price of Rs 1,030. It retained its expectations of high-single-digit India volume growth and double-digit consolidated revenue and EBITDA growth in FY27.
HSBC maintained its Hold rating with a target price of Rs 960. It expects single-digit India volume growth and double-digit consolidated EBITDA growth in FY27, but lowered its FY28 margin expectations. The brokerage also flagged India profitability and management changes as concerns.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.