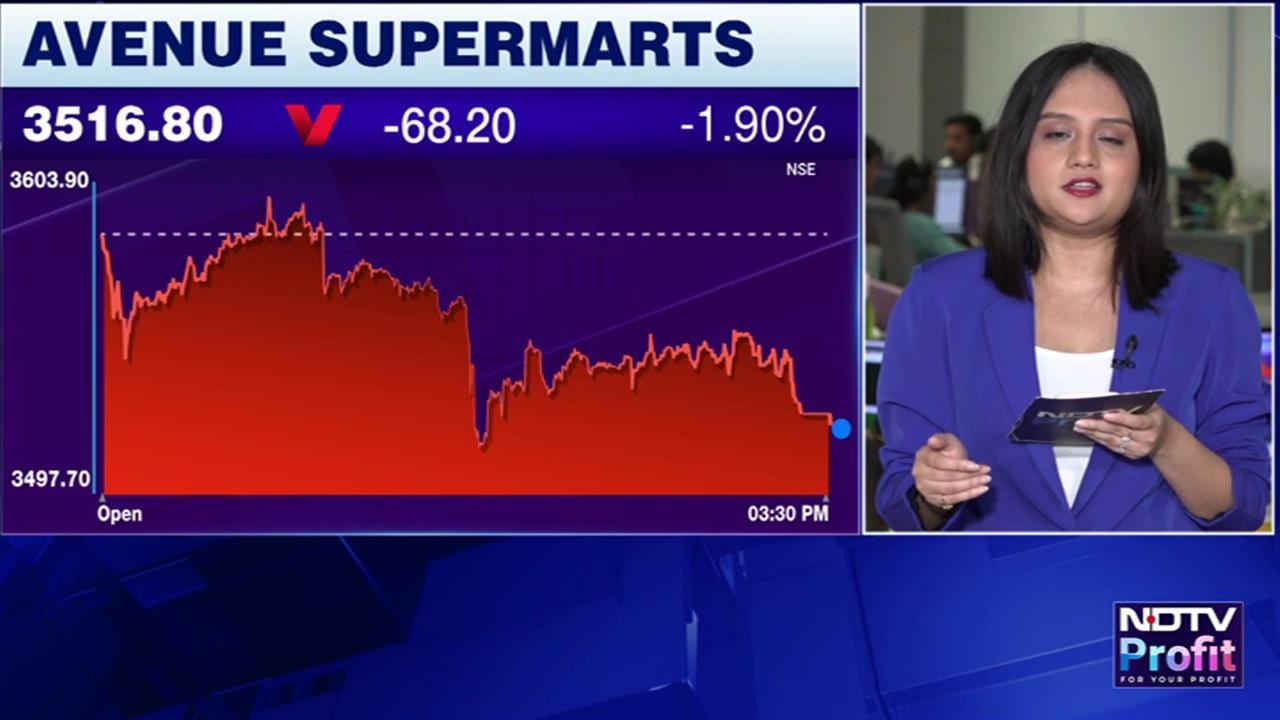
DMart-parent Avenue Supermarts Ltd. is expected to face some immediate and near-term pressure after missing its second quarter profit expectations, according to brokerages like Jefferies, Morgan Stanley, and Citi.
Avenue Supermarts declared the results for the July to September quarter on Saturday, October 10. The company's net profit rose 7.6% to Rs 804 crore in the second quarter of FY27, against Rs 747 crore in the same quarter of the previous year. The net profit missed Bloomberg estimate of Rs 879 crore.
Jefferies held that Dmart's margin miss was a "shocker" and has lowered its price target for the retail chain to Rs 4,000 from an earlier Rs 4,500. The brokerage has also trimmed its EPS estimates by 2-3%, expecting the stock to trade lower in reaction to the Q2 miss.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
"Higher food mix, weaker GM, wage inflation & inventory build weighed on earnings & OpCF. Store expansion remained modest, but productivity softened, as evidenced by a multi-qtr low unit EBITDA for 2Q," Jefferies stated while maintaining a 'hold' rating on the stock.
Morgan Stanley has maintained an 'overweight' rating on the stock, while cutting its price target to Rs 4,182 from Rs 4,464. The brokerage has also trimmed EBITDA to 7.5% and EPS expectations have been reduced by 4%.
"Our decline by 5-7% due to the earnings revisions outlined above, partly offset by a three-month roll-forward of our RI model. All other RI assumptions, including the cost of equity, terminal growth rate, and risk-free rate, remain unchanged," MS stated.
Dmart is facing a harsher treatment from Citi Research, as the brokerage has re-iterated its sell call for the counter noting the lag in profitability. The price target has been revised downwards to Rs 3,516.80 from Rs 3,250.
"Avenue Supermarts is facing double whammy of competition from QC on revenue as well as on profitability. PBT growth has lagged revenue growth in 11 out of last 14 qtrs," Citi outlined in its research note.
The Long-Term View May Be Free Of Bears
Notably, Jefferies and Morgan Stanley have maintained their earlier ratings despite pricing in the margin and PAT miss and cutting down estimates. This is because both brokerages estimate the company and its stock to fare well in the longer run.
"DMart is the leader in value retailing in India and has strong moats and a defensible business model, making it largely resistant to earnings volatility. The worst of mix deterioration is over, in our view, and we build in healthy, high-teens growth, supported by robust SSG and area adds. Valuations have come off their peak, but remain expensive," Jefferies outlined.
Morgan Stanley highlighted that it remains bullish on the long-term opportunity given the substantial addressable market for grocery and DMart's business model strengths.
"We believe DMart's growth slowdown was self-inflicted - its pace of store expansion had not kept pace with the revenue scale of the company. The sharp acceleration in the pace of store expansion in F2026 increases our confidence in DMart's revenue growth delivery in F2027," the brokerage said, adding that it expects revenue growth to improve to 17-18% over Fiscal 2027-29 driven by faster store expansion and improving SSSG trends.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.