New Delhi: India will introduce gold deposit accounts to utilise the 20,000 tonnes available within the country and launch a sovereign bond as an alternative to buying the metal, moves that are likely to cut imports.
Finance Minister Arun Jaitley however did not make any mention of cutting the 10 per cent import duty in his speech on Saturday unveiling the budget for the next fiscal year starting April 1.
India ships in 800-1,000 tonnes of gold a year despite massive stocks in the country that are neither traded nor monetised, Jaitley said.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Without setting a timeline, Mr Jaitley said the government will introduce a gold monetisation scheme which will replace the present gold deposit and gold metal loan schemes.
Gold depositors will earn an interest on their metal account. Banks and other dealers will be able to monetize this gold.
The government will also develop a sovereign gold bond as an alternative to purchasing gold. The bonds will carry a fixed rate of interest and holders will be able to redeem them in cash on the face value of gold.
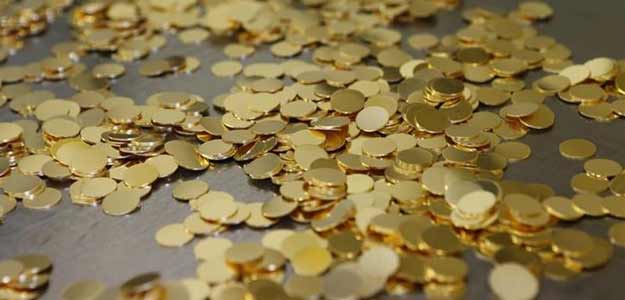
Mr Jaitley said work will also start on an Indian gold coin with the Ashoka Chakra to cut demand for foreign-minted coins.
"Such an Indian gold coin would help reduce the demand for coins minted outside India and also help to recycle the gold available in the country," he said.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.