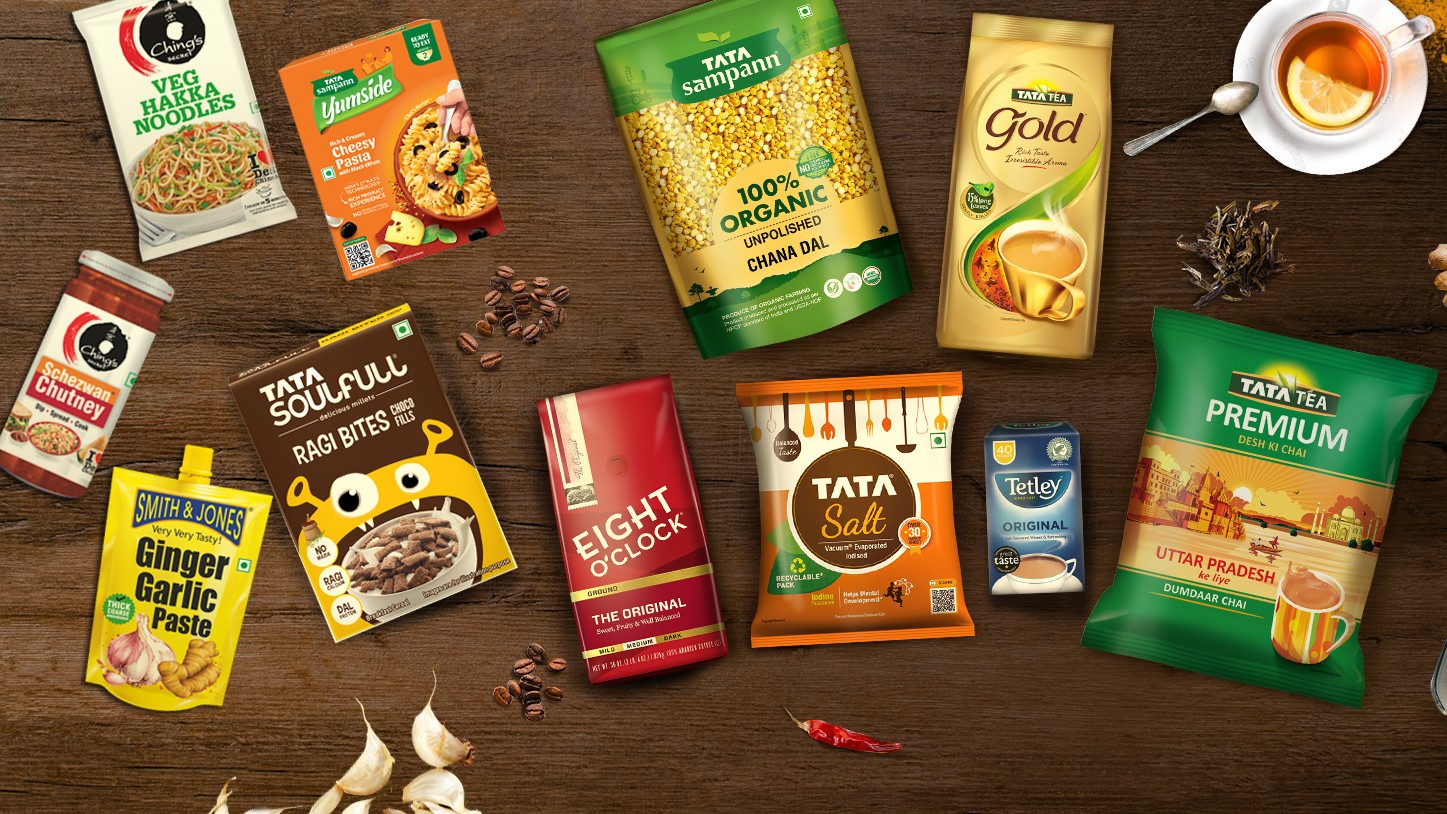
Shares of Tata Consumer Products Ltd. are in focus in trade on Tuesday after brokerages raised their target prices, on the back of strong sales growth in the company's India business.
The FMCG major reported a double digit increase in both revenue and net profit for the September quarter. Its consolidated net profit rose 11% in the second quarter of fiscal 2026. TCPL posted a bottom line of Rs 404 crore, according to an exchange filing on Monday. That compares with the Rs 364-crore net profit posted in the second quarter of FY25.

-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
-
 "I Am A Material Man In A Material World': Quantum Advisors' Ajit Dayal On NDTV Profit Ignite
The topline for Tata Consumer in the second quarter stood at Rs 4,966 crore, which accounts for a 17.8% increase on a year-on-year basis. Margin, though, saw a contraction of 140 basis points, falling to 13.5% compared 14.9% for the same period last fiscal.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The India Foods segment saw a 19% jump, led by a 40% surge in its Tata Sampann portfolio and 23% growth in value-added salt.
The India Beverages segment grew 12%, powered by a 56% rise in its coffee business and 25% growth in its ready-to-drink (RTD) portfolio.
Brokerages' View
CLSA stuck with its 'hold' call on the counter, slightly upping its target price to Rs 1,097.
Though margins contracted, missing CLSA's estimates, the brokerage raised its target price on the back of strong sales growth, as per their latest note. The beat across other estimates was driven by the growth of the tea and salt verticals, says CLSA.
Jefferies also has a similar outlook on the stock, setting its target price at Rs 1,210. The brokerage believes uncertainty owing to tariffs may prevail, and margins may take a quarter or more to normalise in the international segment.
However, the company's management sounded confident on growth and profitability for the India business, Jefferies stated.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.