Shares of Bharat Electronics Ltd. are under pressure in Tuesday's early trade after reporting a weaker-than-expected operating margin in the June quarter. However, leading brokerages are reiterating bullish views on the company's long-term growth prospects driven by a robust order pipeline and rising defence spending.
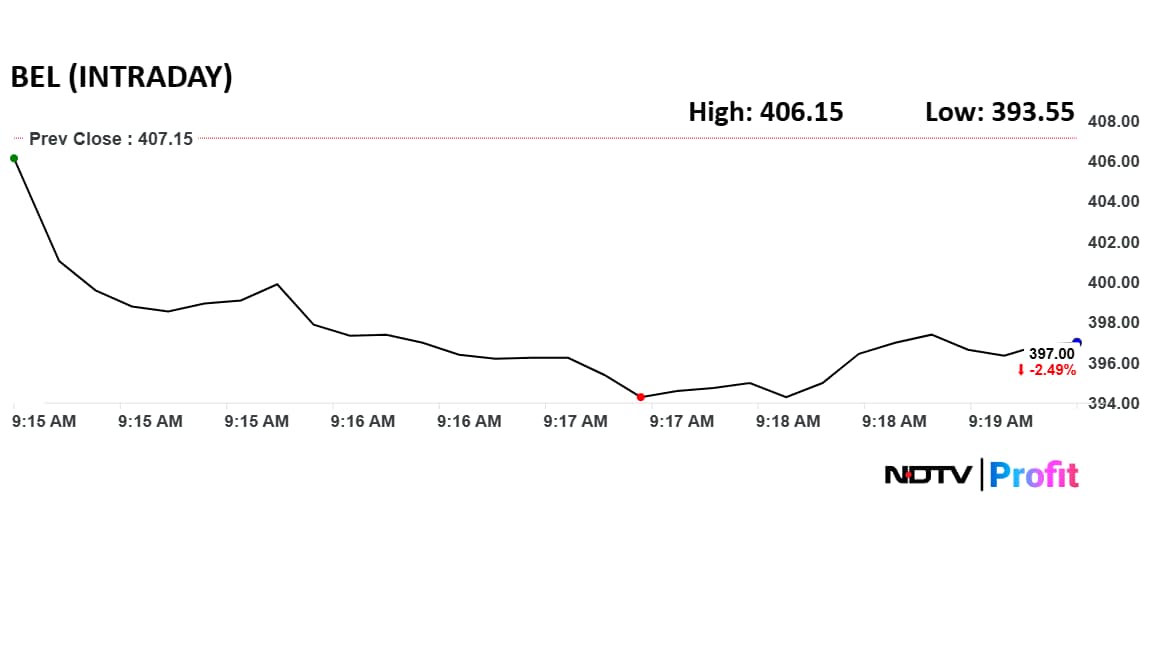
BEL shares slumped 2.49% to Rs 397 apiece as of 9:22 am. It fell as much as 3.34% during the opening trade.

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
Add image caption here
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Bharat Electronics Q1 Results - Standalone
Revenue at Rs 5,533.06 crore vs estimate of Rs 5,086 crore
EBITDA at Rs 1,389.2 crore vs estimate of Rs 1,417 crore
EBITDA margin at 25.1% vs estimate of 27.86%
Net profit (PAT) at Rs 1,048.33 crore vs estimate of Rs 1,077 crore
Brokerages on BEL
JPMorgan
- Maintain Overweight; Target Price: Rs 525.
- Product mix impacted margins in Q1.
- FY27 guidance was maintained across key parameters.
- BEL remains JPMorgan's top pick in the Indian defence sector.
- Medium-term margin sustainability and the impact of the Pay Commission remain key monitorables.
- A strong order pipeline includes NGC, P75I, Hammer, Shakti and electronic warfare (EW) systems.
Goldman Sachs
- Maintain Buy; Cut target price to Rs 470 from Rs 475.
- Order inflows remain the key monitorable.
- Management maintained guidance across key parameters.
- A robust programme pipeline is the key near-term catalyst.
- Margins are expected to remain resilient.
- Exports are becoming an increasingly important part of BEL's medium-term strategy.
- Sees strong growth potential in the counter-drone and drone segments.
Macquarie
- Maintain Outperform; Hike target price to Rs 550 from Rs 510.
- Q1 performance was ahead of expectations.
- Order backlog remained steady.
- Expects FY27 order inflows to exceed Rs 55,000 crore.
- Believes BEL is among the best-positioned stocks to benefit from India's multi-year defence opportunity.
Jefferies
- Maintain Buy; Cut target price to Rs 550 from Rs 585.
- Strong execution offset the margin miss.
- FY27 order inflow guidance was maintained, with 16% of the target already achieved YTD (excluding QRSAM).
- Management reiterated confidence in 15%+ FY27 revenue growth.
- Sees visible double-digit earnings growth over the medium term.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.