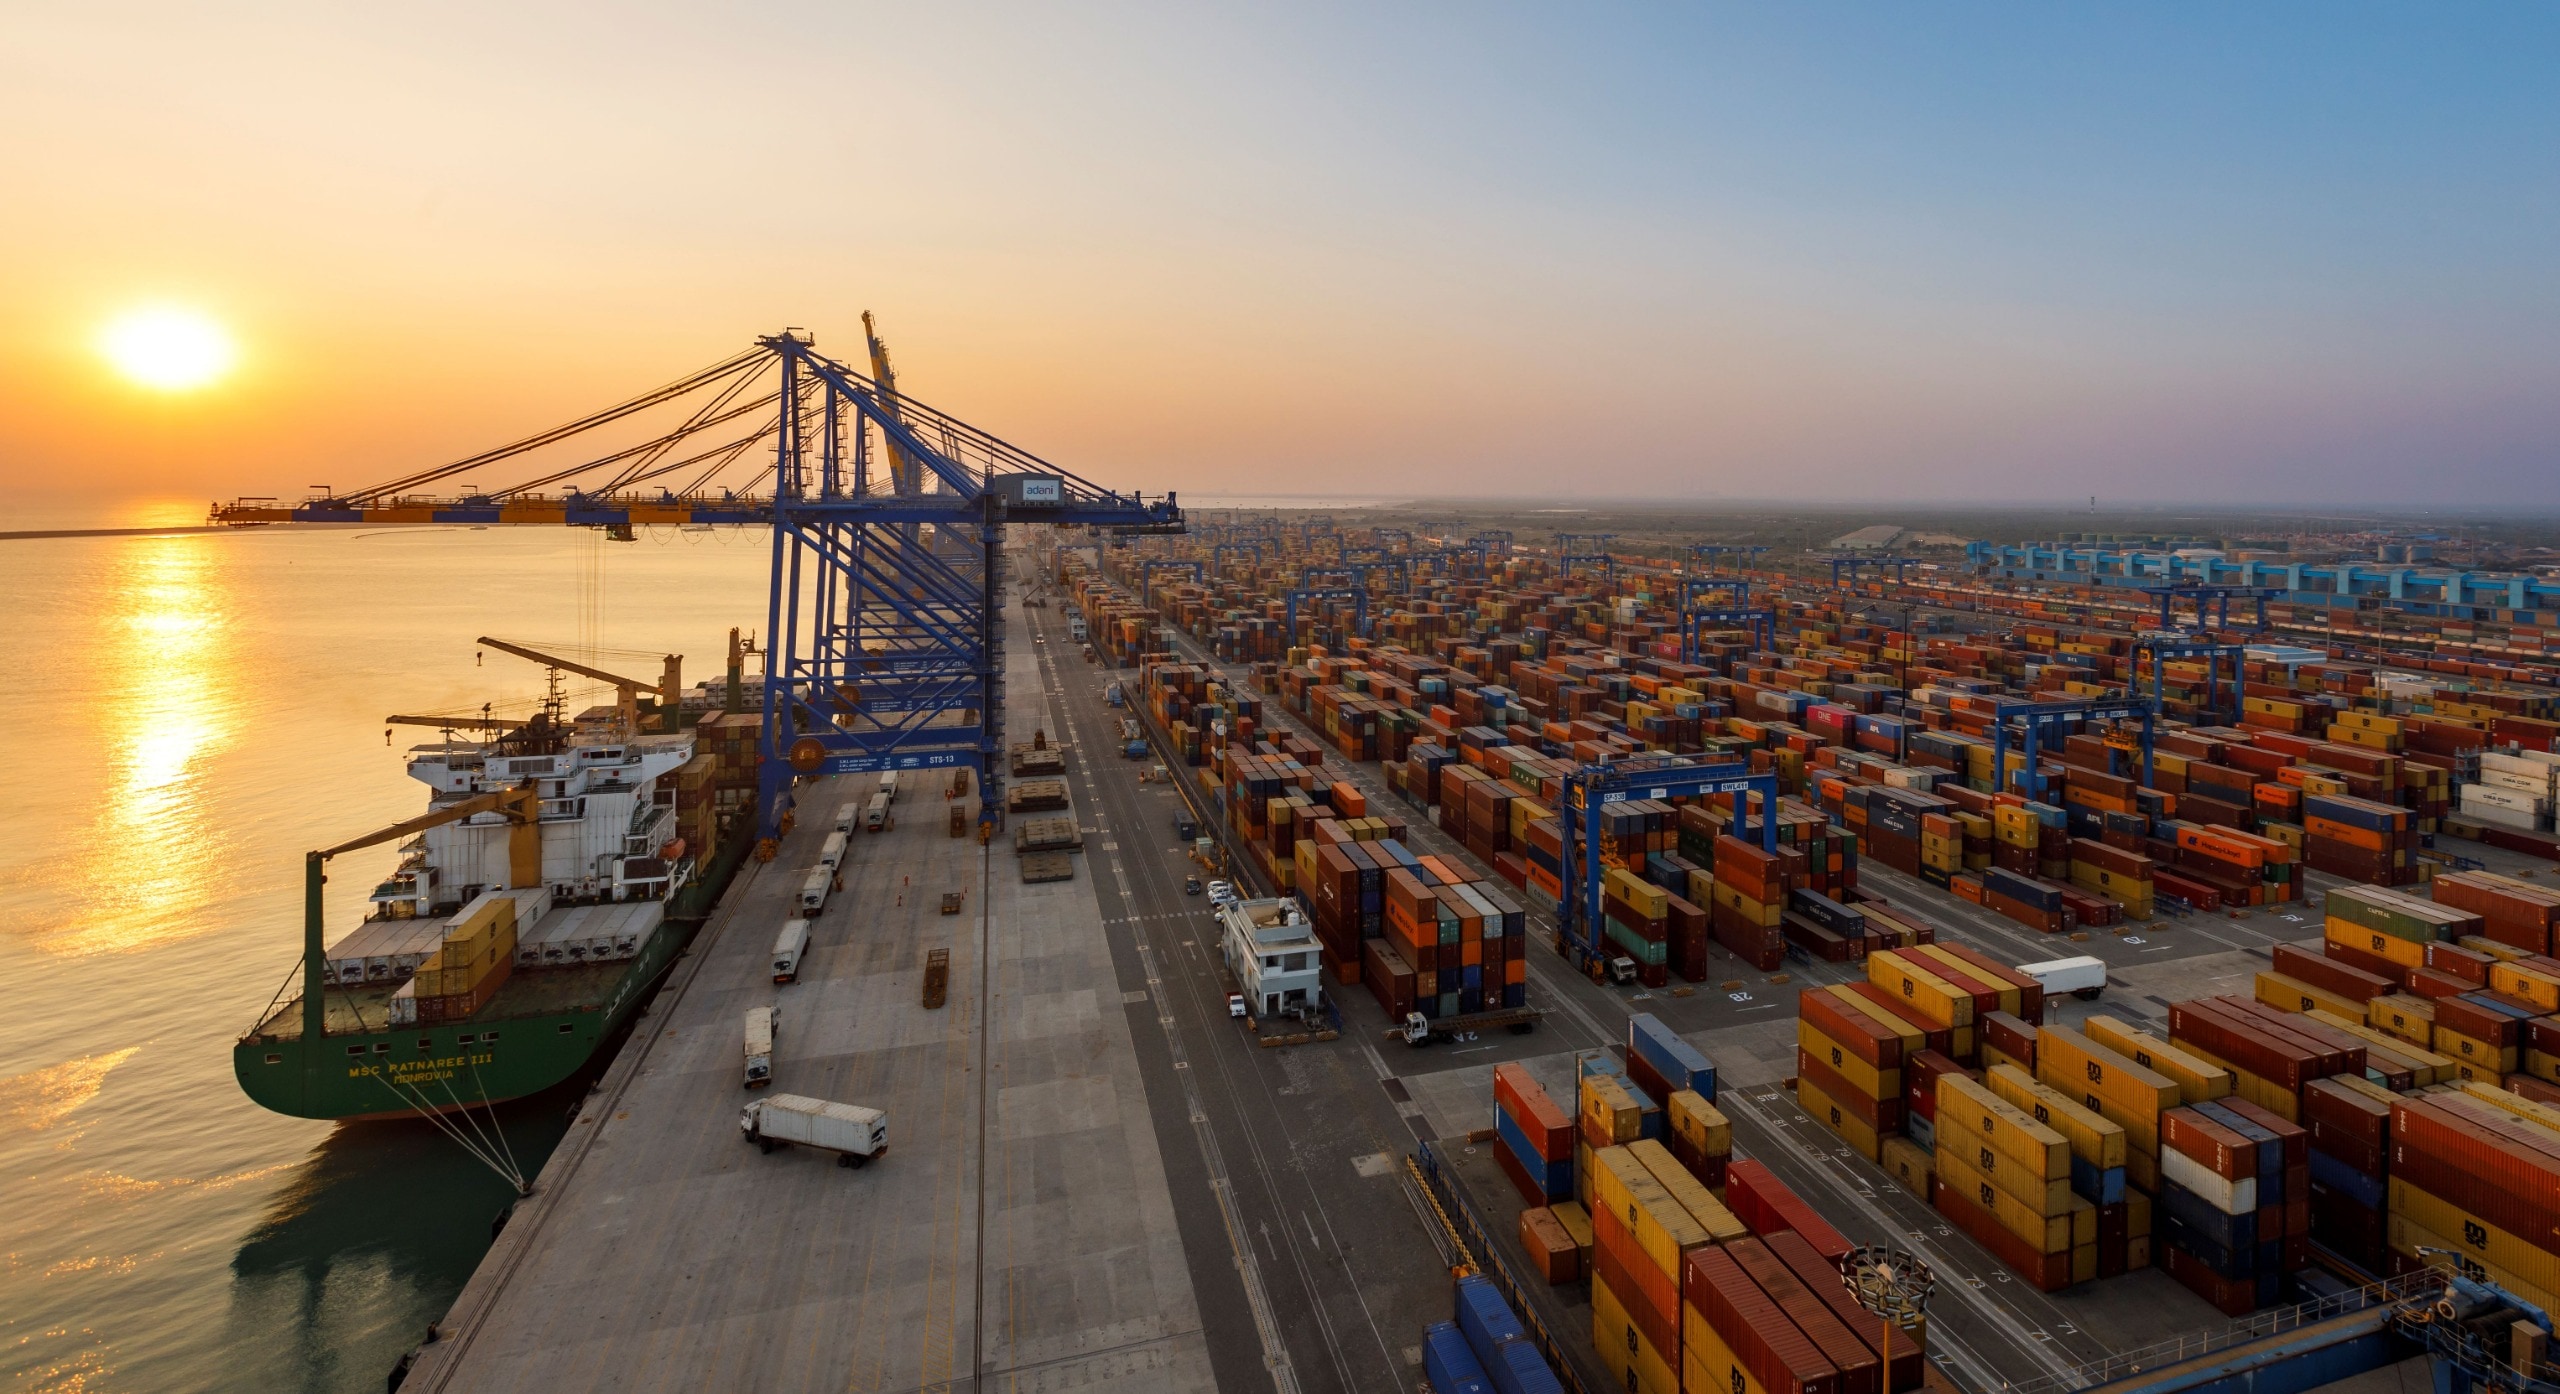
Top brokerages hiked the target price for Adani Ports and Special Economic Zone Ltd. following robust second-quarter results of the company. According to Goldman Sachs, the risk-reward ratio of the stock looks attractive.
Adani Ports and Special Economic Zone reported a 12.4% volume growth because its portfolio of port assets leveraged it for market share gains, Goldman Sachs said. The company will get more organic and inorganic growth opportunities as the balance sheets get stronger.

-
 SEBI Says CAS Works Technologically, Explains Concern Over Expiry-Day Derivatives
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
-
 SEBI To Float Consultation Paper On FPI Norms To Align Indian Markets Globally
-
 Gold ETF Fund-Of-Funds Investment Curbs Are Temporary, SEBI Chair Pandey Says
-
 SEBI To Review Closing Auction Rules After One Year, Chairman Pandey Reiterates
-
SEBI Chief: Direct MF Plans Default From Nov 1; IPO Rules, SME Framework Under Review
-
 "I Am A Material Man In A Material World': Quantum Advisors' Ajit Dayal On NDTV Profit Ignite
-
 Structurally Positive On India In The Long-term:Ben Powell, On NDTV Profit Ignite
-
 'I Am My Own Intern': Tamannaah Bhatia On NDTV Profit Ignite
-
 Indian Mkt Will Return With The 'Smart Mkt' Story: NSE MD & CEO Ashishkumar Chauhan On NDTV Profit I
In the second half, Adani Ports and Special Economic Zone will see an increase in volume growth as new ports start operating, according to Goldman Sachs. Vizinjham, Tanzania, and Colombo Ports will continue to deliver strong traffic in subsequent quarters.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
In coking coal segment, Adani Ports and Special Economic Zone increased their market share to 41.9% from 36.5%. Coastal coal share reached 31.1% compared to 27.8% in the second quarter of the financial year 2025. The management of the company also highlighted an increased focus on electric vehicles.
Goldman Sachs has a Buy rating on the stock with a target price Rs 1,540 apiece, which implied a 7% upside from Tuesday's close level.
Adani Ports & SEZ Q2 Earnings Key Highlights (Consolidated, YoY)
Revenue rose 29.7% to Rs 9,167 crore versus Rs 7,067 crore
Ebitda rose 27% to Rs 5,550 crore versus Rs 4,369 crore
Net Profit rose 27.2% to Rs 3,109 crore versus Rs 2,445 crore
Adani Ports and Special Economic Zone Ltd. maintained its strategy to drive absolute Ebitda growth., led by integrated logistics solutions. Capital allocation is in focus, according to Jefferies.
Jefferies has a Buy rating on the stock. The brokerage hiked the target price to Rs 1,880 apiece from Rs 1,815, which implies a 30% upside potential from the Tuesday's close price.
Macquarie maintained an Outperform rating and Rs 1,760 target price, which implied a 22% upside. Adani Ports and Special Economic Zone is well-placed to achieve the volume growth target for financial year 2026. The long-term outlook remained positive because of the diversification efforts, execution track record, and expansion plans.
CLSA also maintained an Outperform rating with a target price of Rs 1,764 apiece on Adani Ports and Special Economic Zone. The target price implied a 22% upside from Tuesday's close price.
Disclaimer: NDTV is a subsidiary of AMG Media Networks Limited, an Adani Group Company.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.