BQ Prime's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer BQ Prime's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
HDFC Securities Institutional Equities
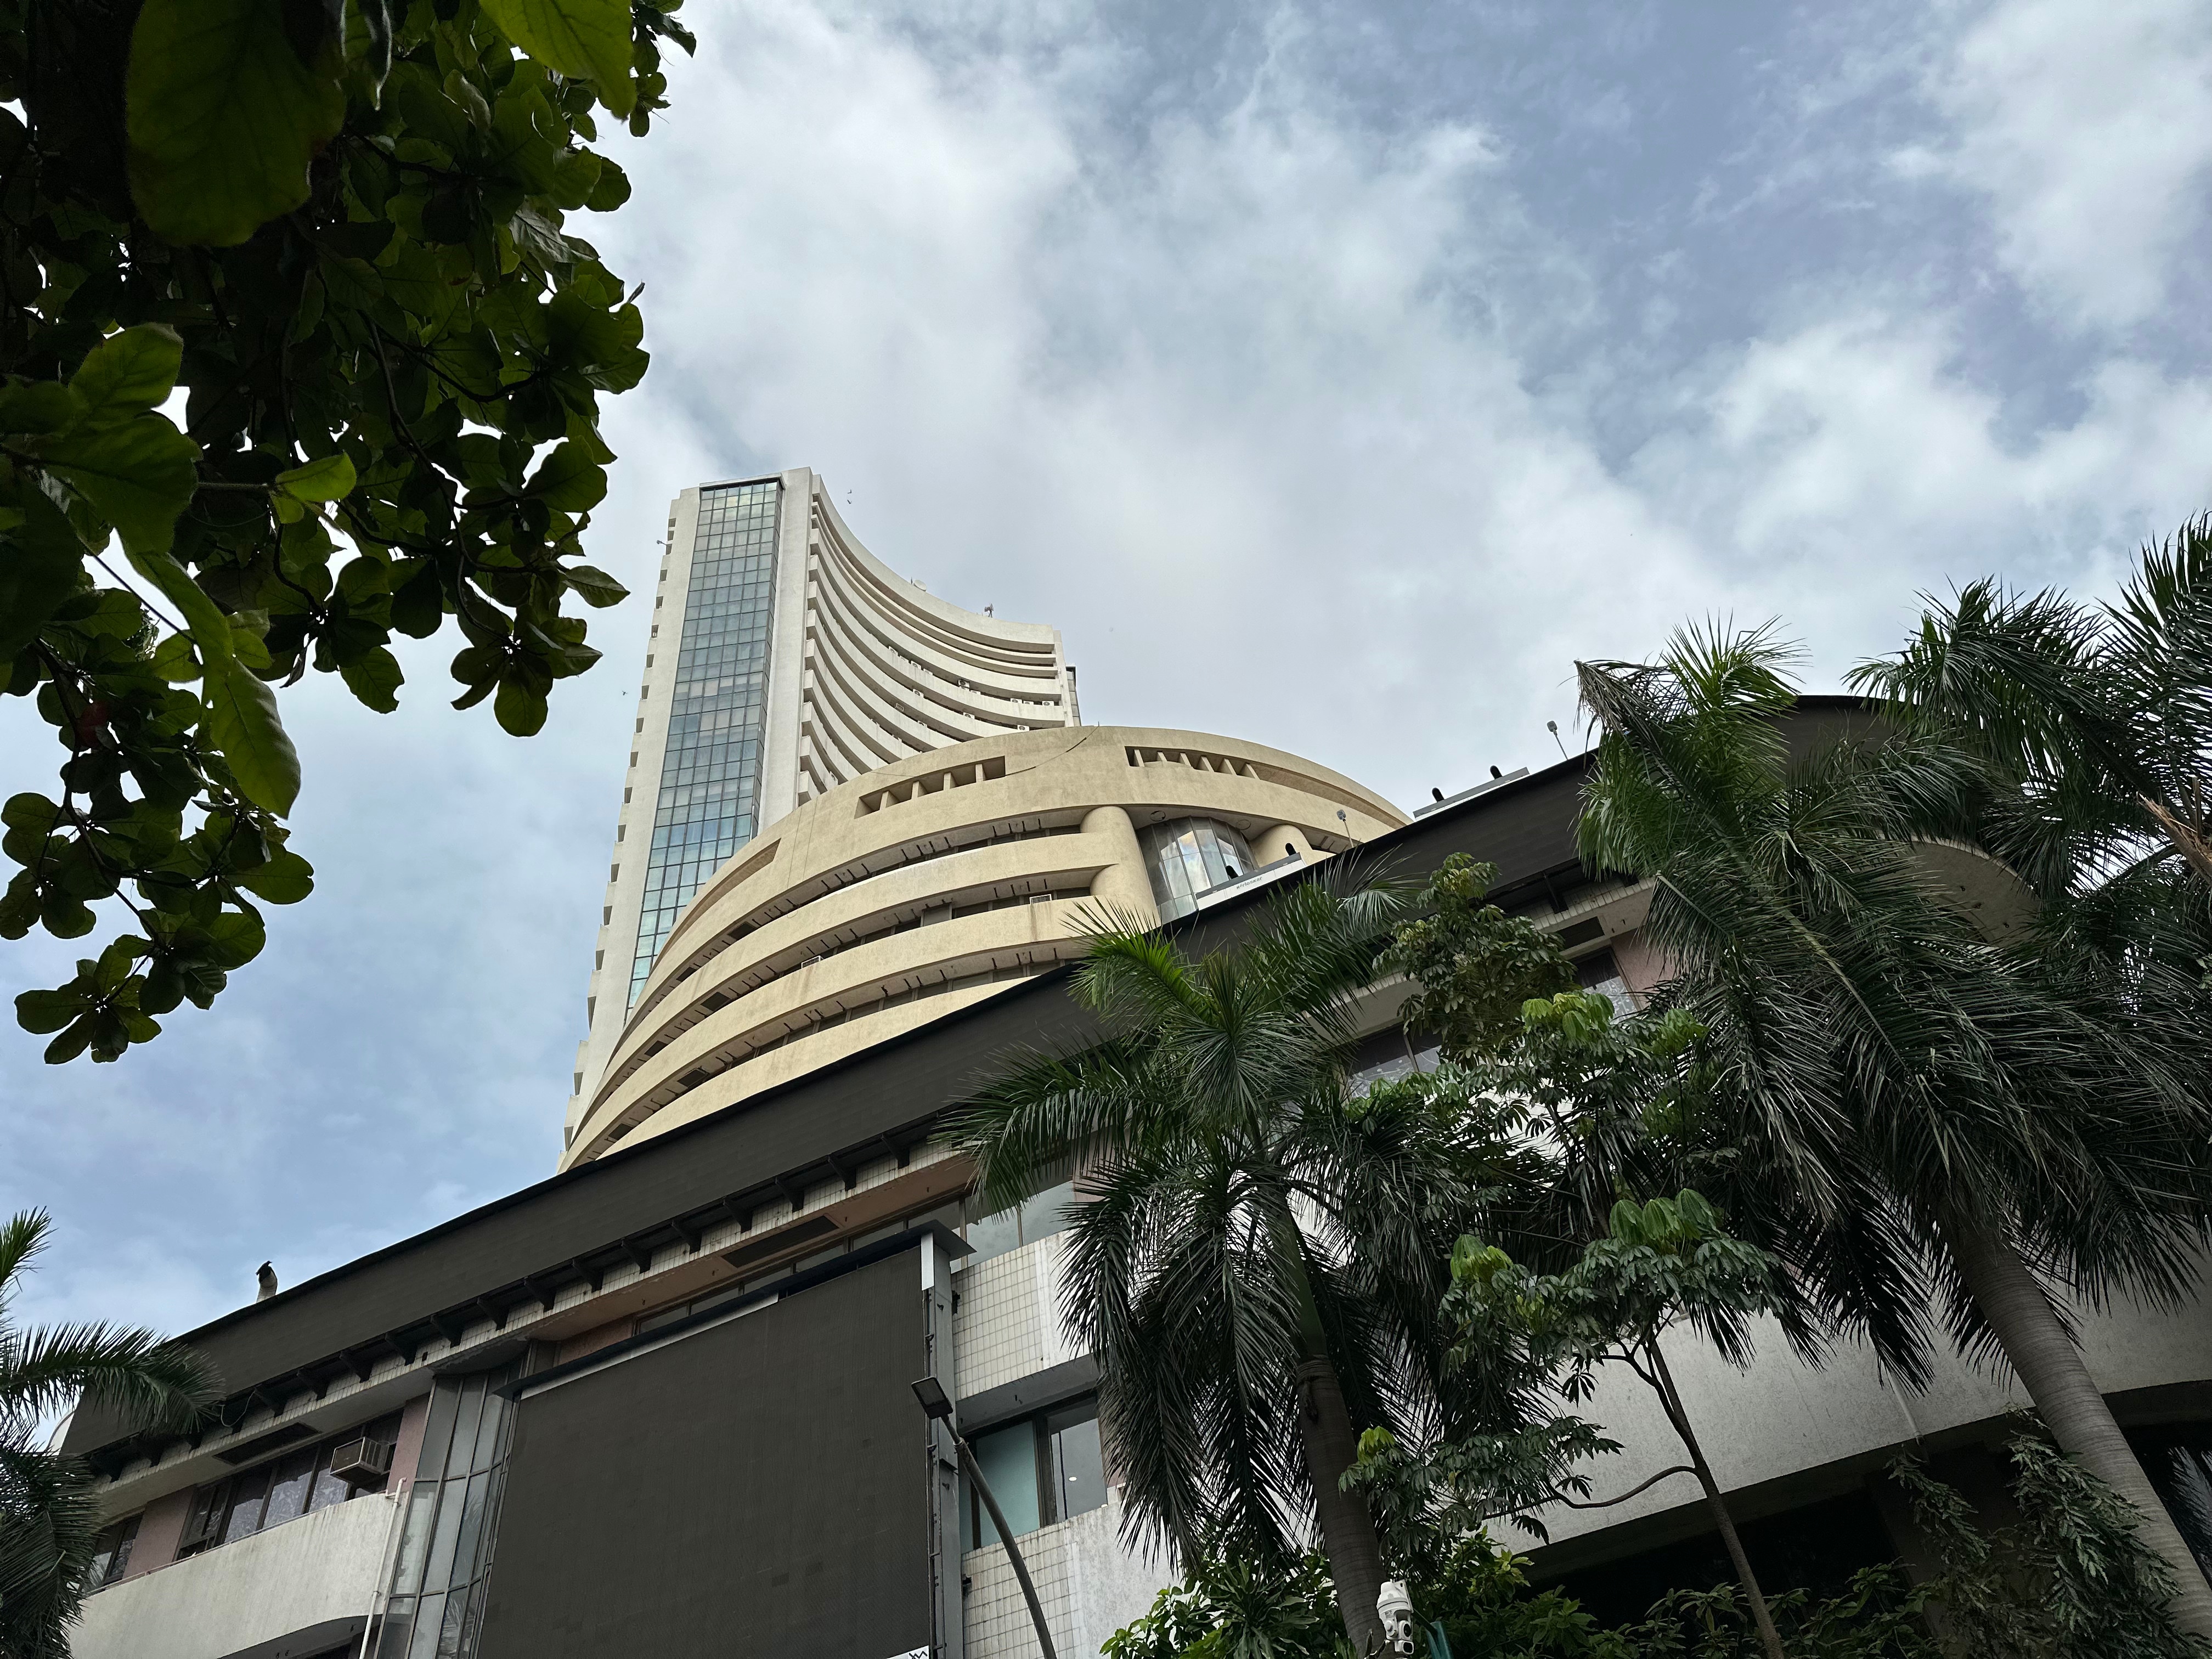
BSE Ltd. has witnessed success with the Sensex contract in the much larger equity derivatives segment, dominated by National Stock Exchange. The Sensex contract is currently catering to ~40% of the NSE's derivatives volume (Nifty) but with the launch of the Bankex contract, BSE will address ~95% of NSE's derivative volume.
With a single contract, the exchange has reached ~9/3% notional/premium market share, which is impressive. The go-live of discount brokers on the platform and new product launch will accelerate BSE's market share gain.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The derivatives growth is organic and is driven by proprietary and retail traders, the active unique client codes on the platform have reached ~0.4 million from nearly zero on June 23.
BSE option pricing is currently one-seventh of NSE, which is not sustainable. We expect the pricing reset to happen soon and have increased options pricing by ~three times; still, it's at ~57% discount to NSE.
Assuming a premium market share of ~9% in FY26E and pricing hike, derivatives will contribute ~25% of BSE's total revenue, 35% of Ebitda and 75% of incremental growth.
We expect a revenue/earnings per share compound annual growth rate of ~26/31% over FY23-26E, led by a revival in transaction revenue.
We increase our EPS estimates by ~15% for FY25/26E and increase the core multiple to 33 times (versus 28 times).
We maintain our 'Buy' rating and assign a SoTP based target price of Rs 1,600, based on 33 times core FY26E PAT plus CDSL stake plus net cash ex SGF.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. BQ Prime does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of BQ Prime.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.