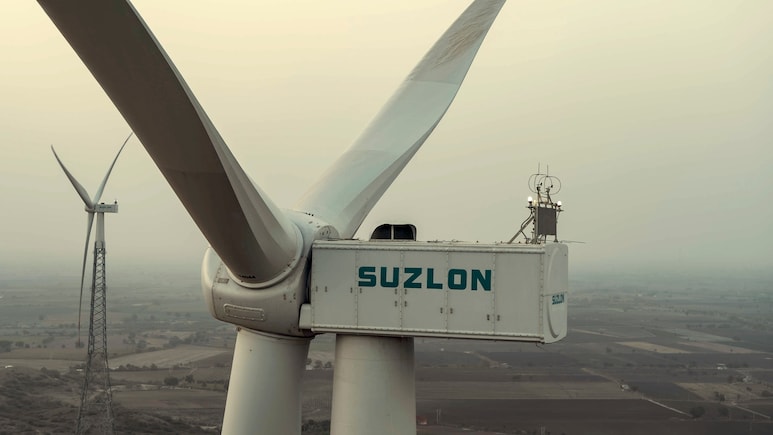
- Suzlon Energy's Q2 revenue rose 26% to Rs 4,869 crore on record 710 MW deliveries
- EBITDA remained flat at Rs 720 crore, with margin narrowing to 14.8% from 18.6%
- Core wind segment revenue grew 30%, but segment result dropped 22.5%, margin fell to 8.8%
Suzlon Energy shipped more turbines in the September quarter than in any previous second quarter, yet its operating profit barely moved. Consolidated revenue rose 26% year-on-year to Rs 4,869 crore on record India deliveries of 710 MW, but EBITDA came in at Rs 720 crore, against Rs 721 crore a year ago. The EBITDA margin narrowed to 14.8% from 18.6% in the year-ago quarter and 15.6% in the June quarter.
It is the second straight quarter in which growth has not reached the operating line. In the April-June period, revenue rose 23% while EBITDA slipped to Rs 595 crore from Rs 599 crore. On its July earnings call, management said it expected margins to stay around the 17-18% range, with the chief financial officer allowing for a deviation of 1-2 percentage points, according to a transcript published by Investing.com. The September-quarter margin falls below even the bottom of that wider band, and first-half margin stands at 15.1%.

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
The pressure is concentrated in Suzlon's core wind business, now called Renewable Energy Solutions. The segment's revenue rose 30% to Rs 4,211.6 crore, but its segment result fell 22.5% to Rs 370.5 crore, according to the company's segment disclosures. That took the segment's margin to 8.8% from 14.8% a year earlier. The company put the wind turbine business's contribution margin for the first half at 22.1%, saying it was hurt by customer and scope mix as well as currency and commodity volatility.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The group-level numbers tell the same story. Suzlon's contribution margin, as reported in its investor presentation, fell to 28.7% from 34.1% a year ago and 32.1% in the June quarter. Material, component and service costs, adjusted for inventory changes, absorbed 68.6% of revenue in the quarter, compared with 62.8% a year earlier. That cost line rose 36%, well ahead of the 26% rise in revenue.

The EPC Effect
A large part of the shift appears to come from what Suzlon is selling. Engineering, procurement and construction contracts, where the company builds the wind farm as well as supplying turbines, now make up 38% of its order book, up from 22% in the June quarter of last year. Suzlon aims to take that share to 50% by FY28.
On the July call, chief executive Ajay Kapur linked the rise in material costs to that larger EPC share. He also said the average selling price had risen to Rs 6.3 crore per MW from Rs 5.6 crore a year earlier, helped by the project mix. In effect, EPC work lifts revenue per megawatt but also brings more bought-in material and construction cost into the books, which can weigh on margins in percentage terms. Management has not quantified that impact, and the CEO has described the newer DevCo-led EPC orders as value accretive.
External factors added to the strain. In Thursday's results statement, chief financial officer Rahul Jain said the quarter was delivered despite commodity and currency volatility. Other expenses, net of adjustments, rose 28% to Rs 388 crore, even as employee costs held flat at about Rs 290 crore.
ALSO READ: Suzlon Energy Q2: Net Profit Plunges 69% To Rs 394 Crore; Margin Contracts
Services Provide The Cushion
The one part of the business moving the other way is servicing. Suzlon's asset management services segment, which maintains more than 16 GW of installed turbines in India, grew revenue 11% to Rs 639.6 crore, while its segment result jumped 51.5% to Rs 220.4 crore. That segment accounted for about 13% of segment revenue but more than a third of segment profit in the quarter, up from 22.5% a year ago.
That cushion may not stay as thick. The services business posted a first-half EBITDA margin of 43.4%, and management said in July that it expected such margins to settle in the high 30s, closer to 40%.
Management has argued that the second half will bring operating leverage. On the July call, the CFO said commissioning has historically been split roughly 35-40% in the first half and 60-65% in the second. Suzlon also has 1,295 MW of turbines erected and awaiting commissioning, and an order book of 6,009 MW.
Whether that is enough to restore margins to the guided range will depend on how much of the slide comes from a lasting shift in project mix, and how much from temporary cost and currency pressure.
ALSO READ: No More Just A Wind Company? Suzlon 2.0 Looking To Expand Into Solar, Battery Energy
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.