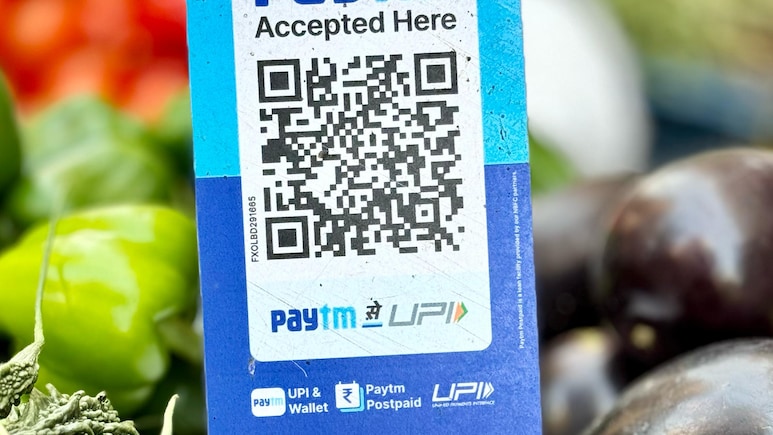
One 97 Communications reported a net profit of Rs 225 crore (18% miss to our estimate of Rs 270 crore), owing to higher indirect expenses and taxes, even as revenue growth was robust despite flat QoQ gross merchandise value growth. Strong revenue growth of 28% YoY/8% QoQ to Rs 2,650 crore (in line) was aided by steady growth in merchant base, number of transactions, device subscription, and payment margin expansion.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.

-
 Gold Price Dips Ahead Of Diwali: Can It Go Lower On Dhanteras? What To Expect
-
 What Would Make Brokers Bullish Again On Indian Markets? Axis Lists Its Triggers
-
 India's Market Leaders To Decode The New Samvat At NDTV Profit Ignite In Mumbai On Oct 28
-
 NDTV Profit IGNITE Diwali 2026: Top Market Veterans Decode Wealth Creation
-
 The Week Ahead: Earnings Season, Fed Policy Verdict And Crude Oil In Focus
-
 NDTV Ignite, The Trillion-Dollar Trajectory: India's Road to 2030
Motilal Oswal Report
According to Motilal Oswal, One 97 Communications Ltd. reported a steady quarter, supported by robust revenue growth and disciplined management, even as PAT was a miss due to higher indirect expenses and taxes. Management expects indirect expenses to grow at less than half the rate of revenue.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The company continues to make healthy progress toward sustainable profitability and improving operating leverage, even while gross merchandise value was flat QoQ owing to festive season getting pushed to Q3.
Contribution margin stood healthy at 56%, while the software, cloud, data center expenses and taxes were higher than expected.
On the proposed MDR on select UPI transactions less than Rs 2,000, the company has indicated ~2.5 basis points rise in overall PPM.
The brokerage has aligned its earnings estimates to factor in potential MDR impact on UPI, building in a PAT of Rs 1,040 crore/Rs 2,650 crore in FY27/28E.
Motilal Oswal has valued Paytm at Rs 1,850, based on 38 times FY28E EV/Ebitda and has reiterated Neutral rating on the stock.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.