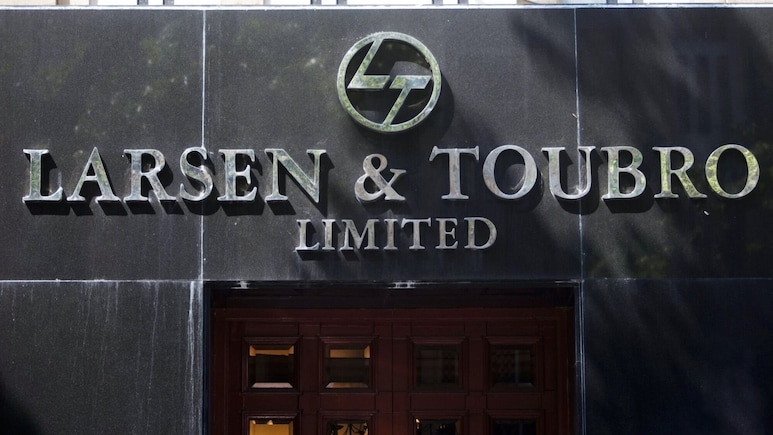
JP Morgan has reiterated its bullish view on infrastructure major Larsen & Toubro (L&T), supported by attractive valuations and strong growth prospects.
The brokerage firm believes that while the US-Iran war in the Middle East is an overhang on L&T shares, the business is being positioned for mid-teens growth with healthy RoE in traditional and emerging areas.
According to JPMorgan, the current valuation of L&T shares at less than 25x P/E is attractive and the stock remains its preferred pick. It has maintained an ‘Overweight' rating on L&T shares, with September 2027 target price of Rs 5,060 apiece, implying an upside potential of nearly 30% from Monday's closing price.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
JP Morgan noted that L&T's execution in the Middle East continues without any major disruptions and customers are by and large accommodating cost increases due to the impact of the conflict.
ALSO READ: Stock Market Today: All You Need To Know Before Going Into Trade On Sept 22
On the domestic front, the brokerage firm expects public capex to up after a period of consolidation, while private corporate capex has achieved traction, led by large order wins in thermal power.
Additionally, L&T has rolled out a strategic plan which envisages entry into new areas of data centers, green energy and electronic manufacturing and aims to double defense revenue by 2031, while keeping a focus on RoE, cash flows and shareholder returns intact.
“We believe that while the conflict in the Middle East is an overhang on L&T stock, the business is being positioned for mid-teens growth with healthy RoE in traditional and emerging areas. Valuation at <25x P/E is attractive and L&T remains our preferred pick,” JPMorgan said.
On Monday, L&T share price ended higher at Rs apiece on the BSE.
ALSO READ: Catch Stock Market Live Updates Here
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.