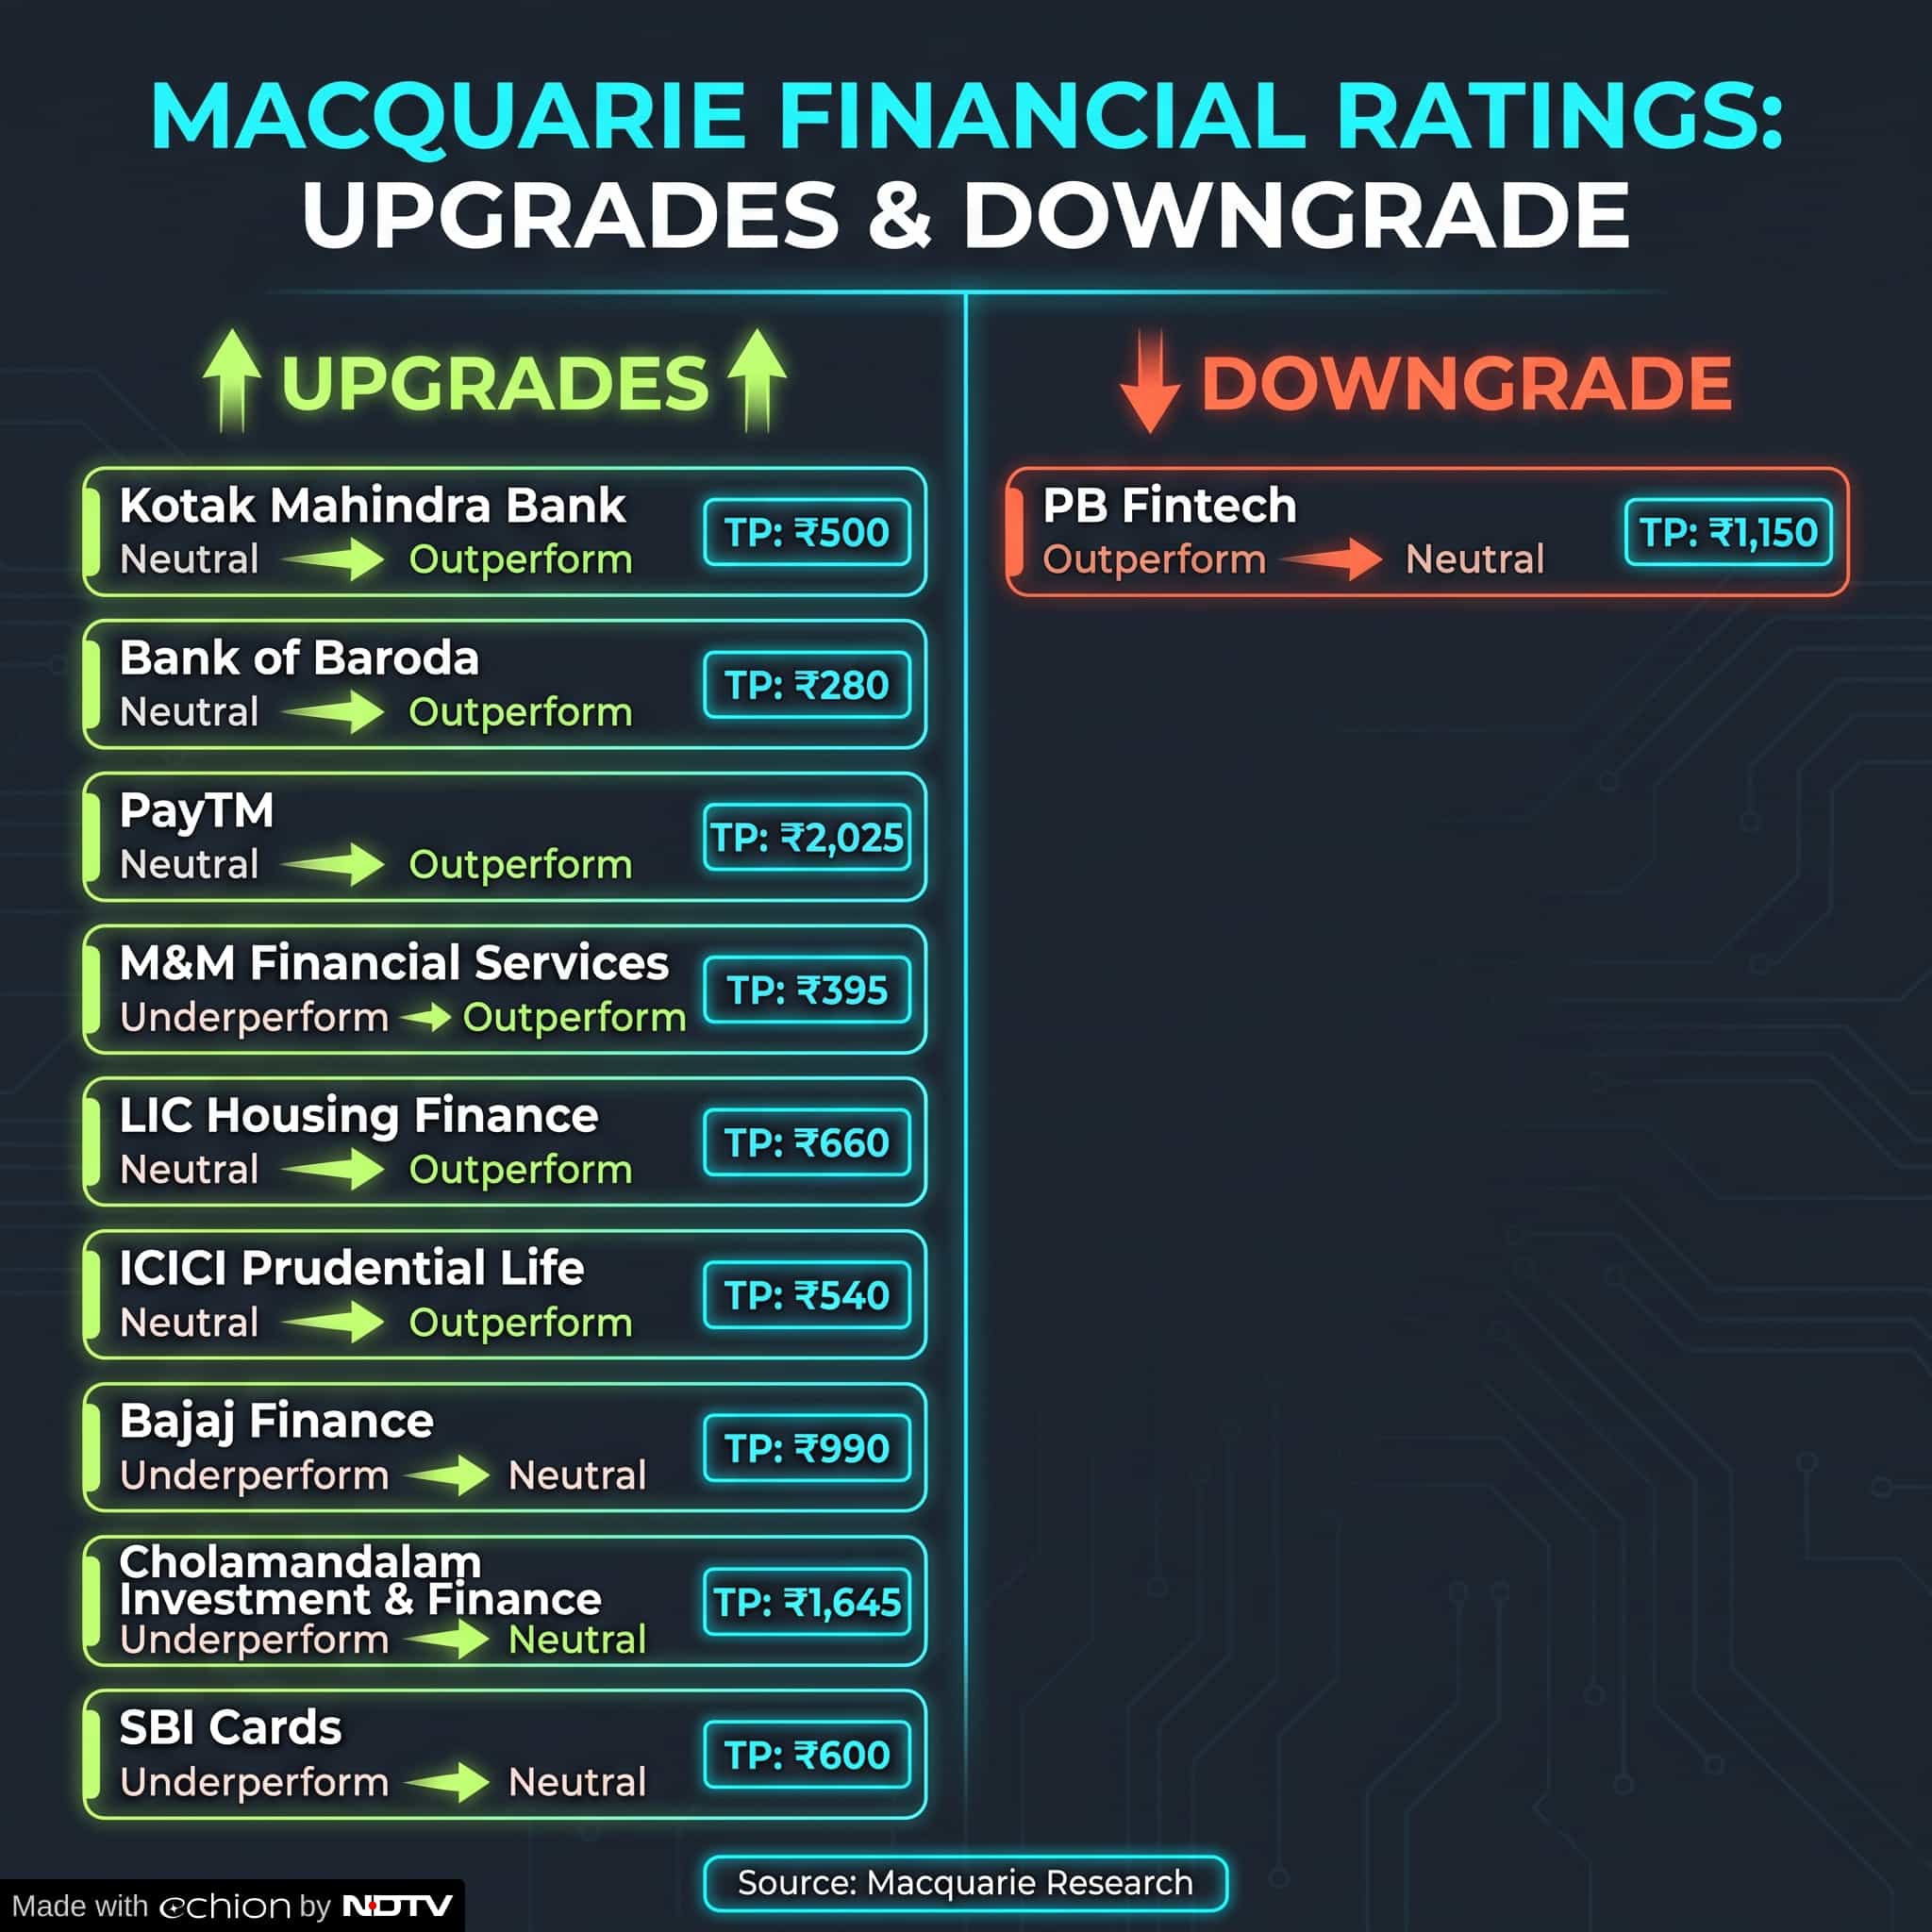
Kotak Mahindra Bank, Bank of Baroda, PayTM, Mahindra & Mahindra Financial Services, LIC Housing Finance and ICICI Prudential Life are among the financial stocks that received recommendation upgrades from Macquarie in its latest India Financials strategy note. The brokerage expects FY28 to be a strong year for banks, with around 18% EPS growth, supported by an estimated 15 basis-point expansion in margins.
Macquarie upgraded Kotak Mahindra Bank and Bank of Baroda to Outperform from Neutral, while PayTM, M&M Financial Services, LIC Housing Finance and ICICI Prudential Life were also moved to Outperform. Bajaj Finance, SBI Cards and Cholamandalam Investment & Finance were upgraded to Neutral from Underperform. At the same time, PB Fintech was downgraded to Neutral from Outperform.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Why Macquarie Favors These Stocks
For banks, Macquarie sees a combination of improving margins, falling operating expenses and lower credit costs supporting earnings over the next two years. It estimates around 75 basis points of rate hikes over the next 9-12 months, with FCNR deposits also helping margin expansion. The brokerage expects around 15 bps year-on-year margin expansion in FY28.
Among individual banks, Macquarie's current top picks are ICICI Bank, Kotak Mahindra Bank, SBI and City Union Bank. It has an Outperform rating on all four, with target prices of Rs 1,730, Rs 500, Rs 1,220 and Rs 265, respectively.
Bank of Baroda, upgraded to Outperform, has a target of Rs 280. Macquarie said the bank's core profitability remains resilient and sees around 1% ROA as sustainable in FY28-29.
NBFCs, Insurance Also In Focus
Macquarie expects NBFC loan growth to remain healthy, but warned that a rate increase and higher bond yields could lift borrowing costs and pressure near-term margins. It prefers L&T Finance, AB Capital, Shriram Housing Finance and M&M Finance among NBFCs.
The brokerage upgraded M&M Finance to Outperform after its asset-quality turnaround, cutting FY27-28 credit-cost estimates to 1.4% from 1.7% and raising its sustainable ROA expectation above 2%. Its target price is Rs 395.
Insurance stocks have underperformed, but Macquarie said regulatory concerns are now largely reflected in valuations. It prefers LIC and SBI Life, with LIC carrying a Rs 550 target and SBI Life Rs 2,120.
For fintechs, PayTM remains an Outperform with a Rs 2,025 target, while PB Fintech was downgraded to Neutral with a target of Rs 1,150 after sharp earnings estimate cuts linked to proposed insurance commission changes.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.