Goldman Sachs Sees Earnings Turnaround For India’s Financial Firms
International broking firm Goldman Sachs expects to see an earnings turnaround for the Indian banking and financial services industry as their “confidence in green shoots” rises.
“We revise FY18-19E earnings per share estimates by 1-6 percent on average (as banks recover from downgrade cycle) driven by better NIMs/operating efficiency,” it said in a research note.
Goldman cited four key reasons for its bullish view.
- Expectations of credit growth improvement
- Most large NPL being already recognised
- Better fee income
- Gains in operating efficiency
Goldman's View
On ICICI Bank
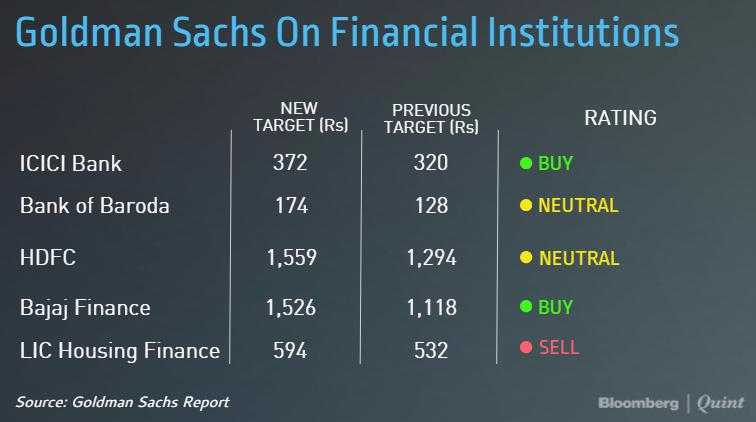
- Rating: Buy
- Price Target: Raised to Rs 372 from Rs 320
- Expect non-performing loans (NPLs) to improve.
- See gradual recovery in the credit growth.
- Expect earnings to improve by FY19 as large part of the corporate stress has been recognised.
- Expect 16 percent compounded annual growth rate in earnings over the FY17-20 period.
- ICICI Bank better positioned compared to peers from capital standpoint.
On Bajaj Finance
- Rating: Buy
- Target Price: Raised to Rs 1,526 from Rs 1,118
- Raised FY19 earnings per share estimate by 10 percent on the back of higher growth and fee income estimates
- Expect 31 percent compounded annual growth rate in earnings over the FY17-20 period.
- Rising credit card transactions is a key positive.
- Diversified product portfolio with limited competition beneficial for the company.
- Expect Bajaj Finance to deliver in FY19 on operating efficiency and stable credit costs.
On Bank Of Baroda
- Rating: Neutral
- Target Price: Raised to Rs 174 from Rs 128
- Expect 12 percent compounded annual growth rate in earnings over the FY17-20 period.
- Capital raising in Q4 likey to strengthen the balance sheet.
- Expect operating performance and loan growth to pick up in FY19-20
- Weaker profitability remains concern.
- Expect impaired loan ratio to drop 7.8 percent by FY19.
On HDFC
- Rating: Neutral
- Target Price: Raised to Rs 1,559 from Rs 1,294
- Expect core earnings trajectory to improve in double-digits in near-term.
- Improvement in housing affordability would lead to rebound in loan growth.
- Expect lending spreads to remain tight over FY18-20
- Expect 16 percent compounded annual growth rate in earnings over the FY17-20 period.
- Marginally raised earnings per share estimates by 2-4 percent for FY18-19.
On LIC Housing Finance
- Rating: Sell
- Target Price: Raised to Rs 594 from Rs 532
- Expect 17 percent compounded annual growth rate in earnings over the FY17-20 period.
- Expect 10 basis points decline in NIMs to 2.5 percent in FY19
- Margins likely to remain capped due to intense competitiveness.
- Operating profit likely to decline 15 percent over FY17-20
- Higher than expected volumes on affordable housing could turn negative for the finance company.

-
Navigating Energy Crossroads: S Jaishankar's Call For Diversified Supply Chains At G20 Ministerial Meeting

As geopolitical fault lines continue to test maritime trade routes and commodity flows, Jaishankar's message remains pertinent: true economic resilience requires open markets, protected transit lines, and a genuine commitment to multilateral cooperation rather than coercion.
-
Indians Are Travelling, But Not Every Journey Is A Holiday | The Week In Whys
Pilgrims, patients and working women are the real travellers, and the system hasn't quite caught up with them.
-
Getting To Work Costs Women More | The Reason Why
It is not just about women paying more than men. It is about women paying much more in cities than in villages.
-
AI Bias In Investing Cannot Be Eliminated, But It Can Be Governed
Framing is a particularly important example as identical financial information presented in terms of gains rather than losses can lead an LLM to reach a different assessment.
-
Joining The Dots | Dark Skies, Steady Diya: Why Hope Holds This Diwali
With war, a weak rupee and foreign outflows weighing on sentiment, policymakers at the NDTV World Summit and market veterans at NDTV Profit Ignite: Diwali Edition offered the same advice: stay invested and filter out the noise.
-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock
PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.










