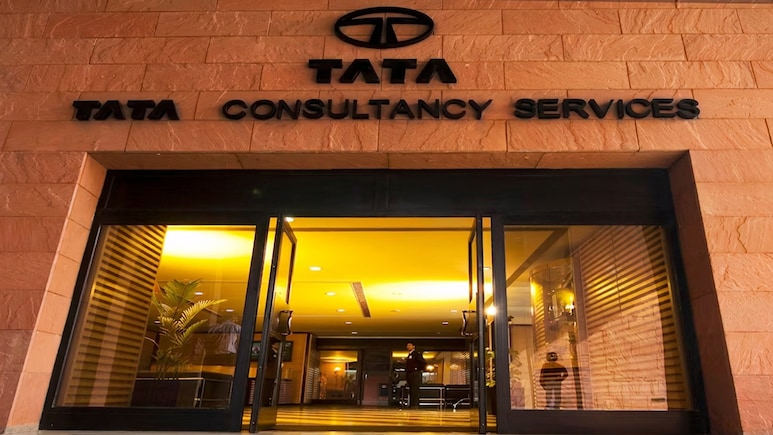
TCS Q2 Results In Focus: TCS will announce its Q2 FY27 results on Thursday, October 8, 2026, with investors looking for signs that India's largest IT services company is finally seeing a meaningful pickup in global technology spending.
But expectations remain measured, with brokerages forecasting only modest sequential growth as cautious client spending, macro uncertainty and AI-led pricing pressure continue to weigh on the business.
According to Bloomberg Estimates, TCS is expected to report 1.04% quarter-on-quarter (Q-o-Q) revenue growth in Q2 FY27, while EBIT and net income are seen rising 2.82% and 3.29%, respectively. The estimates suggest that while profitability could improve, the recovery in demand remains far from convincing.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The bigger question for investors, therefore, is whether TCS can provide enough evidence of an improving demand environment through its deal wins, AI-led opportunities and management commentary on the second half of FY27.
TCS Q2 Results: Brokerages See Muted Growth
The TCS-specific brokerage estimates point to a subdued quarter.
IDBI Capital expects TCS' revenue to increase 0.5% Q-o-Q, despite strong momentum in AI-led services. However, macro headwinds affecting mega deals are expected to limit overall growth.
ALSO READ: TCS Q2 Performance: How The IT Giant Has Fared Over The Last Five Years
The brokerage expects EBIT margin to expand by 44 basis points Q-o-Q, primarily due to the reversal of the impact of wage hikes. This benefit is expected to be partly offset by investments in AI capabilities and partnerships.
For investors, IDBI Capital said key areas to watch include the impact of global capability centres (GCCs), which could be both a competitive threat and a growth opportunity for IT services companies.
The brokerage will also be watching TCS' ability to defend margins, details around the Porsche partnership and acquisition deal, currency movement, cost optimisation and progress on data-centre investments.
Nuvama Institutional Equities expects TCS to deliver 0.6% Q-o-Q constant-currency revenue growth and 0.5% Q-o-Q growth in US dollar terms.
However, the brokerage said growth is likely to remain modest because of a slower-than-expected pickup during the second half of the quarter amid heightened geopolitical uncertainty.
Nuvama expects margins to expand by 20 bps Q-o-Q, while deal wins are expected to remain solid, supported by large deals from MHP, BSNL and Metro.
The brokerage will particularly watch the BFSI and developed-market growth outlook, as these remain critical to any sustained recovery in TCS' business.
Choice Institutional Equities has the most cautious view among the TCS-specific brokerages, expecting flat Q-o-Q US dollar revenue growth.
According to Choice, macro headwinds, AI-driven cost pressure and a slower-than-expected H2 pickup are likely to constrain growth. This could be partly offset by steady execution in BFSI and continued deal momentum.
Choice expects TCS' EBIT margin to expand 25 bps Q-o-Q to 24.1%, helped by productivity gains and operational efficiency, although currency headwinds could partly offset the improvement.
The brokerage will also track AI revenue traction and deal scalability, the outlook across verticals, data-centre investments, inorganic growth priorities, margin resilience and pricing pressure.
Weak Client Spending, AI Pricing Pressure Keep IT Sector Under Pressure
The cautious TCS outlook comes against a broader IT sector backdrop where the traditional seasonal boost has failed to translate into a strong growth print.
HDFC Securities, in its IT sector outlook, expects Q2 FY27 to remain a muted quarter despite being seasonally strong for Indian IT companies.
The brokerage expects Tier-1 IT companies to deliver between -0.4% and +2.0% Q-o-Q constant-currency growth, with client decision-making remaining cautious and discretionary spending curtailed amid macroeconomic uncertainty.
Pricing pressure is also becoming an increasingly important issue as AI-led productivity gains are passed on to clients through renewals and new deals.
For TCS, HDFC Securities expects 0.5% Q-o-Q constant-currency revenue growth, putting it behind some of the better-performing Tier-1 names expected in the quarter.
The brokerage expects HCLTech and Tech Mahindra to deliver the strongest Tier-1 prints, while TCS, Infosys and Wipro are expected to see relatively weaker growth.
The broader recovery is also being pushed further into the second half of FY27, with HDFC Securities noting that H1 has tracked below expectations.
TCS Q2 Results: Can AI Offset Weak Discretionary Demand?
This is likely to be one of the biggest questions for TCS during the earnings call.
AI is creating new opportunities for Indian IT companies, but it is also putting pressure on pricing as productivity gains are increasingly being passed on to clients.
HDFC Securities expects the IT sector to face around 6-7% deflationary impact from AI, although this is being partly offset by new AI-centric deal wins.
The challenge is that conversion of these opportunities into meaningful revenue remains slow.
For TCS, investors will therefore be looking beyond the headline revenue number for commentary on AI revenue traction, scalability of AI-led deals, pricing, large-deal conversion and client spending.
The company's data-centre investments will also remain on the radar as demand for AI infrastructure continues to develop.
TCS Q2 Results: Q1 Profit, Margins Under Pressure
TCS' Q2 performance will also be measured against a mixed Q1 FY27 showing.
In the June quarter, TCS' consolidated net profit fell 2.7% Q-o-Q to Rs 13,349 crore, compared with Rs 13,718 crore in the March quarter.
Revenue from operations, however, increased 2.2% sequentially to Rs 72,275 crore, from Rs 70,698 crore in Q4 FY26.
The pressure was more pronounced at the operating level. EBIT declined 3.1% Q-o-Q to Rs 17,317 crore, while EBIT margin contracted 130 bps to 24%, compared with 25.3% in the previous quarter.
TCS maintained a workforce of nearly 5.94 lakh employees, while attrition increased during the quarter.
The Q1 numbers highlighted the challenge facing TCS i.e. revenue was still growing, but profitability came under pressure. Q2 will therefore be closely watched for signs that margins are stabilising alongside a recovery in demand.
TCS Q2 Results: Management Commentary Could Hold The Key
For investors, the headline revenue and profit numbers may only tell part of the story.
The key question will be whether TCS sees enough improvement in client spending and decision-making to support a stronger second half of FY27.
Brokerages will be watching commentary on BFSI demand, developed markets, discretionary spending, large deals, AI-led revenue opportunities, pricing pressure, margins and data-centre investments.
HDFC Securities also expects management commentary on furlough intensity, CY27 client budgets, AI's deflationary impact and large-deal conversion to be closely monitored.
For TCS, the earnings question is therefore becoming increasingly clear i.e. Can new AI-led opportunities and large deals finally overcome weak discretionary spending, or will global demand continue to keep growth in check? That answer could be more important for the stock than the Q2 headline numbers themselves.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.