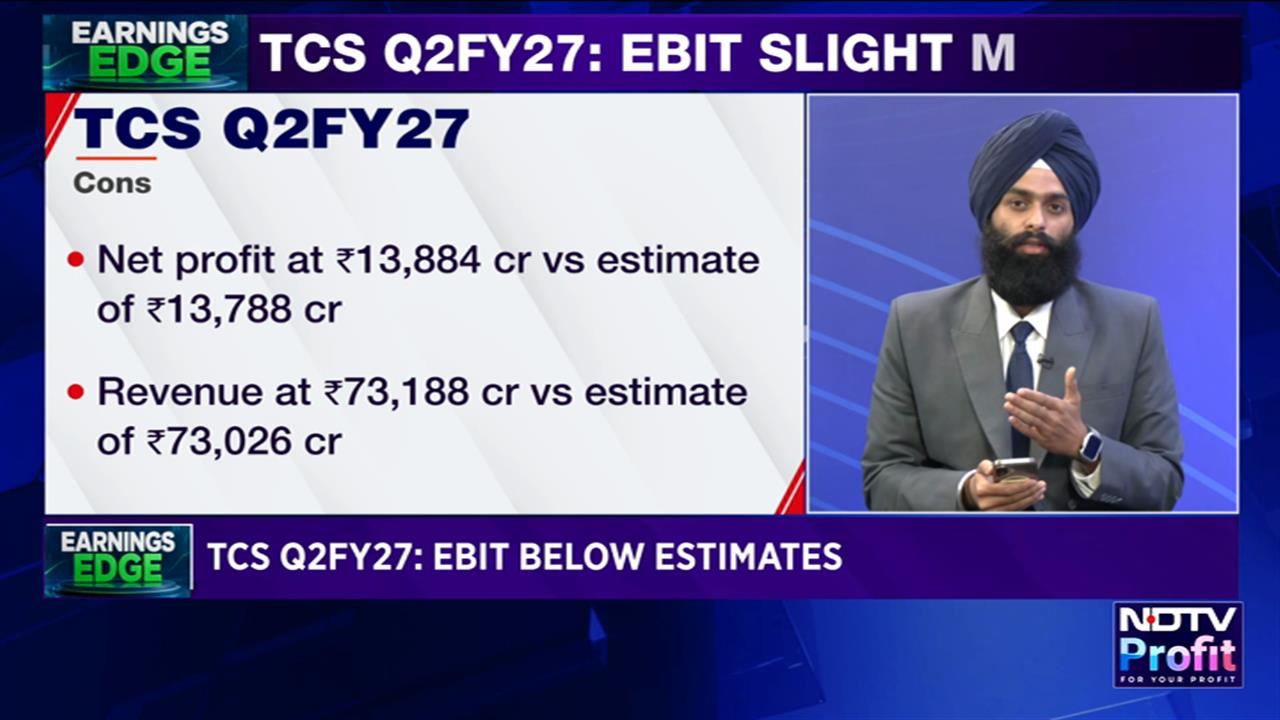
TCS reported Q2 FY27 revenue of Rs 73,188 crore, up 1.3% sequentially and 11.2% YoY. Constant-currency revenue grew 0.5% QoQ, while international markets expanded 1.2%, led by the UK. Growth also broadened across key verticals, with BFSI rising 2.5% sequentially and manufacturing and technology services growing 3.1% each.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
IDBI Capital Report
IDBI Capital has maintained its 'Buy' rating on Tata Consultancy Services Ltd. with a target price of Rs 2,400, implying around 16% upside from the brokerage's cited market price of Rs 2,075. The brokerage believes earnings risk has increasingly shifted towards margins rather than demand, with much of the near-term pressure already reflected in valuations.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
TCS reported Q2 FY27 revenue of Rs 73,188 crore, up 1.3% sequentially and 11.2% YoY. Constant-currency revenue grew 0.5% QoQ, while international markets expanded 1.2%, led by the UK. Growth also broadened across key verticals, with BFSI rising 2.5% sequentially and manufacturing and technology services growing 3.1% each.
Ebit margin held at 24.0%, but gross margin slipped on higher subcontractor costs and bench investment. The proposed MHP acquisition adds roughly 50 basis points of dilution in H2, and CFO called any further improvement an "uphill task" which makes 25% FY27 exit target as at risk.
ALSO READ | TCS Shares Jump Over 2% As Q2 Cheer Outweighs US Green Card Action Jitters
Management kept the 26-28% long-term aspiration unchanged, but offered no timeline. Offsetting this, demand quality is improving. TCV was $9.6 billion, excluding the Porsche and Best Buy wins, and win rate have also improved.
AI-led deflation, weak consumer demand, volatile regional markets and a delayed margin recovery are the key risk to the brokerage call.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.