NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Motilal Oswal Report
Solar Industries shares could remain in focus after domestic brokerage firm Motilal Oswal Financial Services initiated coverage on the stock with a 'Buy' rating and a target price of Rs 23,000, implying a potential upside of about 24% from the reports current market price of Rs 18,555.
ALSO READ: JSW Cement In Focus As Motilal Oswal Upgrades Rating; Sees Up To 25% Upside — Check Target Price
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
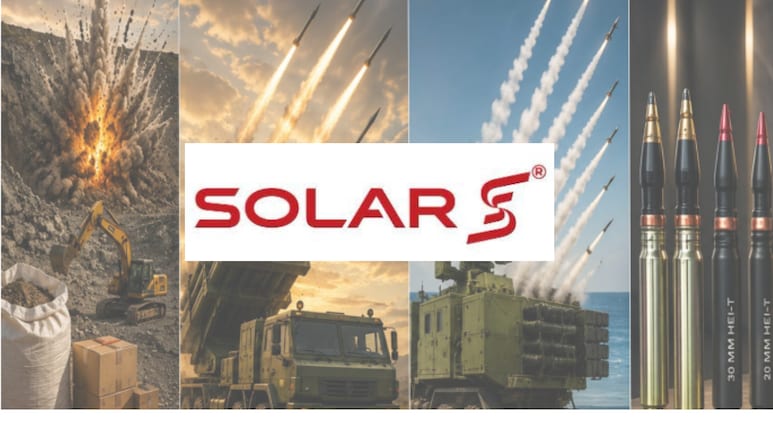
According to the report, Solar Industries has transformed from a supplier of high-energy explosive materials into an integrated defense manufacturer with offerings spanning ammunition, rockets, drones, loitering munitions and counter-drone systems. The company has a defense order book of around Rs 18,000 crore, including international orders worth Rs 11,000 crore and a Pinaka rocket order worth Rs 6,000 crore.
Motilal Oswal expects the defense segment to benefit from additional Pinaka orders, demand for ammunition, follow-on orders for Nagastra drones, potential orders for Bhargavastra counter-drone systems and opportunities under Project Kusha. The brokerage estimates defense revenue to rise from Rs 2,630 crore in FY26 to nearly Rs 9,900 crore by FY30.
The brokerage also highlighted Solar Industries' proposed acquisition of South Africa-based Omnia Holdings, which is expected to strengthen its global presence and provide backward integration in ammonium nitrate, a key raw material used in explosives. Post acquisition, the company's distribution network is expected to expand to over 110 countries.
Motilal Oswal forecasts Solar Industries to deliver a CAGR of 43%, 36% and 34% in revenue, EBITDA and profit after tax, respectively, over FY26-FY30. The brokerage believes strong defense execution, expanding global operations and new product launches will support the company's next phase of growth.
Key risks and concerns
Key risks to our estimates and rating would emerge from delays in order inflows and in the finalization of a large platform order pipeline or country-specific risks due to high exposure to the African market. Poor performance of subsidiaries and sharp currency fluctuations can also impact overall margin performance.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.