NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Motilal Oswal Report
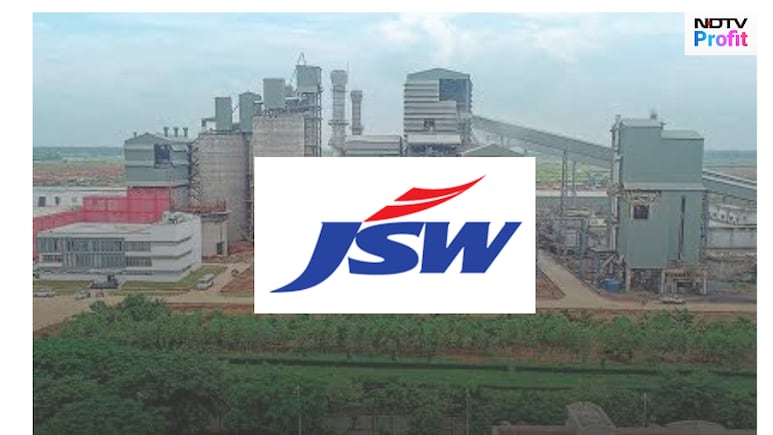
Considering JSW Cement Ltd.'s successful entry into the northern region, its ability to maintain leverage discipline, and earnings stability from exposure in ground granulated blast furnace slag, domestic brokerage firm Motilal Oswal upgrades its rating to Buy from Neutral, and values the company at 14 times FY28E EV/Ebitda to arrive at a target price of Rs 146. implying a potential upside of 25% from the reports current market price of Rs 117.
At current market price, the stock is trading at 12x FY28E EV/Ebitda as compared to 14x FY28E EV/Ebitda at its listing price.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
According to the brokerage JSW Cement is moving from a predominantly south/ground granulated blast furnace slag-led franchise toward a more diversified, integrated and geographically balanced cement company. The north India plant is key growth driver, providing both incremental capacity and access to a more profitable/balanced market.
Motilal Oswal also highlighted that there would be near-term margin pressure due to higher input costs and weak pricing, which will be faced by all cement players.
The company's variable cost to decline meaningfully over a medium term, led by stabilisation of its north India plant and other key initiatives for cost reductions (AFR, renewable and logistics efficiency), believes the brokerage.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.