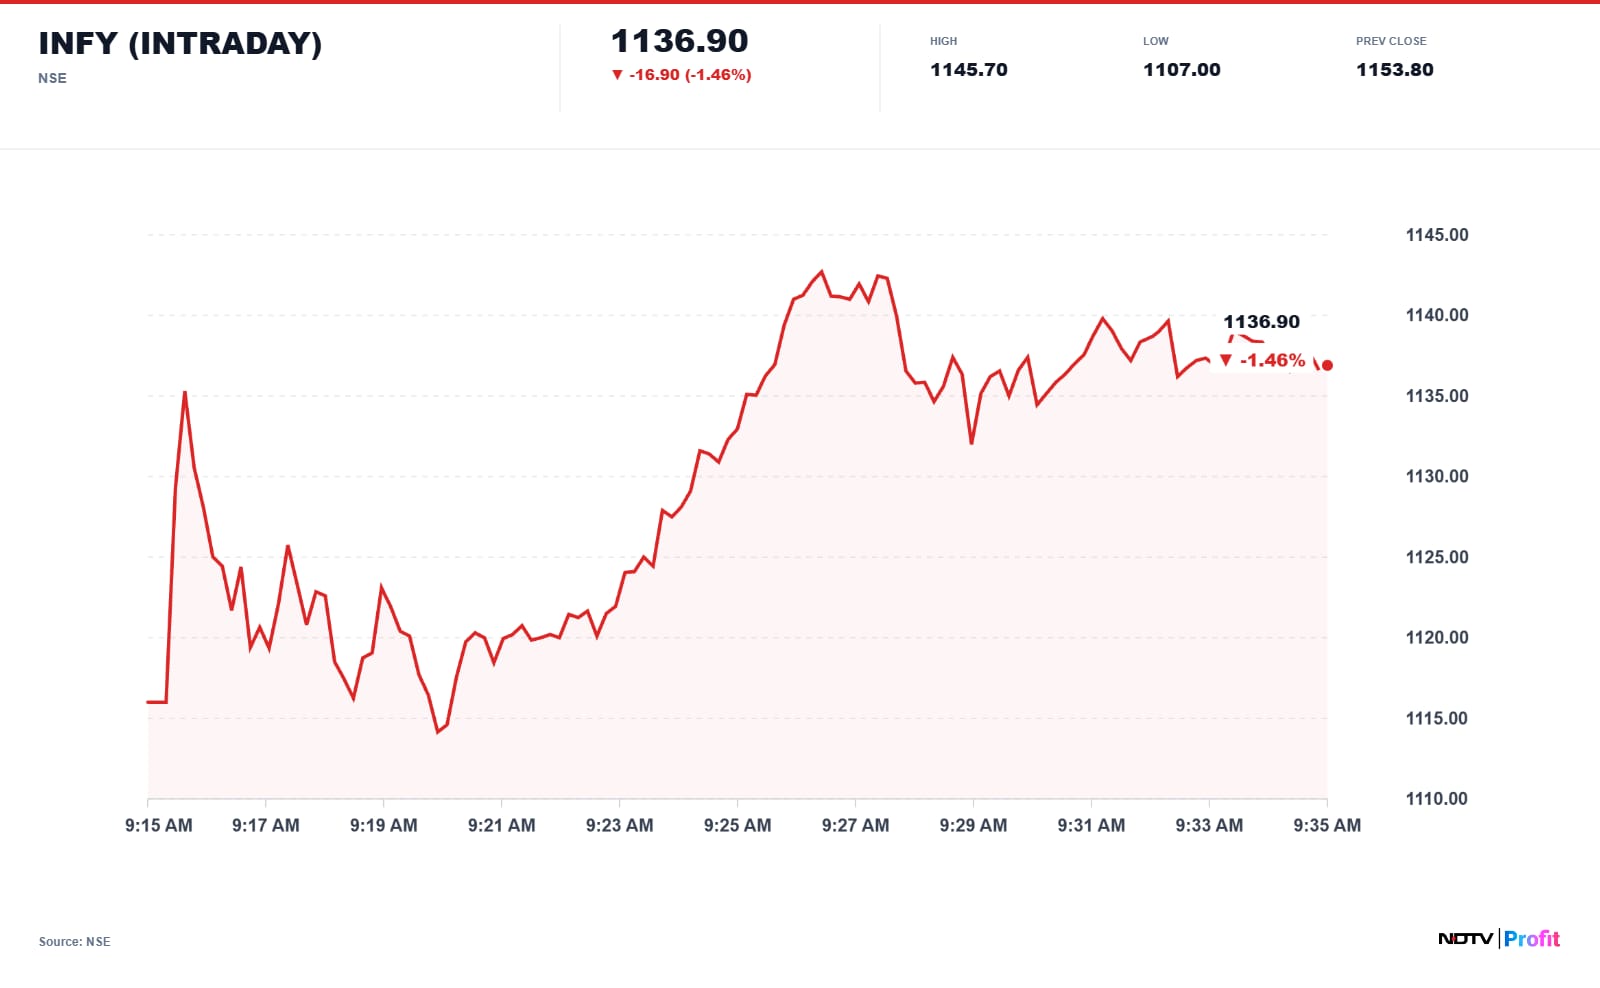
Infosys share price fell over 3% in early trade on Monday after the IT major reported softer Q2 earnings. The IT stock declined as much as 3.88% to Rs 1,109.70 apiece on the BSE.
The second largest IT services company, Infosys, reported 0.7% rise consolidated net profit to Rs 7,823 crore in the September quarter from Rs 7,769 crore in the June quarter.
The company's revenue in Q2FY27 rose 2.1% to Rs 49,244 crore from Rs 48,211 crore, quarter-on-quarter (QoQ). In US Dollar terms, revenue grew 1.3% sequentially of to $5,145 million. Infosys reported constant currency revenue growth of 1.2%. AI now formed 10.5% of the overall topline.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
At the operational front, EBIT was up 1.6% QoQ to Rs 10,330 crore, while EBIT margin stood at 21% from 21.1% in the June quarter.
The Bengaluru-based IT services provider cut its revenue growth guidance. Infosys now expects its full year revenue growth to be between 1% to 2% from the earlier projection of 1.5% to 3%. EBIT margin guidance has been maintained between 20% to 22%.
ALSO READ: Infosys Q2 Review: Motilal Oswal Sees 13% Upside Despite Guidance Cut; Check Revised Target Price
Should you buy, sell or hold Infosys shares after Q2 results?
JP Morgan maintained its ‘Neutral' rating on Infosys shares with a target price of Rs 1,050 apiece after the IT firm's softer print than peers. The brokerage firm expects Infosys to face challenges in H2, with organic growth slowing to laggard levels in FY27. It expects growth likely to be soft from a contract loss in FY28.
The brokerage cut margins estimates by 30 bps for FY27, driving 3% EPS cut while FY28-29E EPS cuts of 1% are mainly driven by forex. It believes Infosys' multiples are likely to remain at a discount to TCS and HCL Technologies.
Jefferies maintained ‘Hold' and cut the target price to Rs 1,140 per share from Rs 1,160 earlier, noting that Infosys Q2 results missed estimates, with softer margins and a 75 bps cut to organic growth guidance.
It cut earnings estimates by 1.5% and expects the company to deliver 4.5% recurring EPS CAGR. It sees limited downside for the stock, but believes growth concerns to limit scope for PE re-rating.
Citi maintained a ‘Neutral' call and slashed Infosys share price target to Rs 1,105 share from Rs 1,030 earlier.
At 9:25 AM, Infosys share price was trading 3.05% lower at Rs 1,119.30 apiece on the BSE.
ALSO READ: Nifty, Sensex Open Lower, Extending Declines For Fifth Day
Disclaimer: The views and opinions expressed by the investment advisers on NDTV Profit are of their own and not of NDTV Profit. NDTV Profit advises users to consult with their own financial or investment adviser before taking any investment decision.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.