Maruti Suzuki Q1 Results Review: New Launches To Help Gain Market Share, Boost Margin
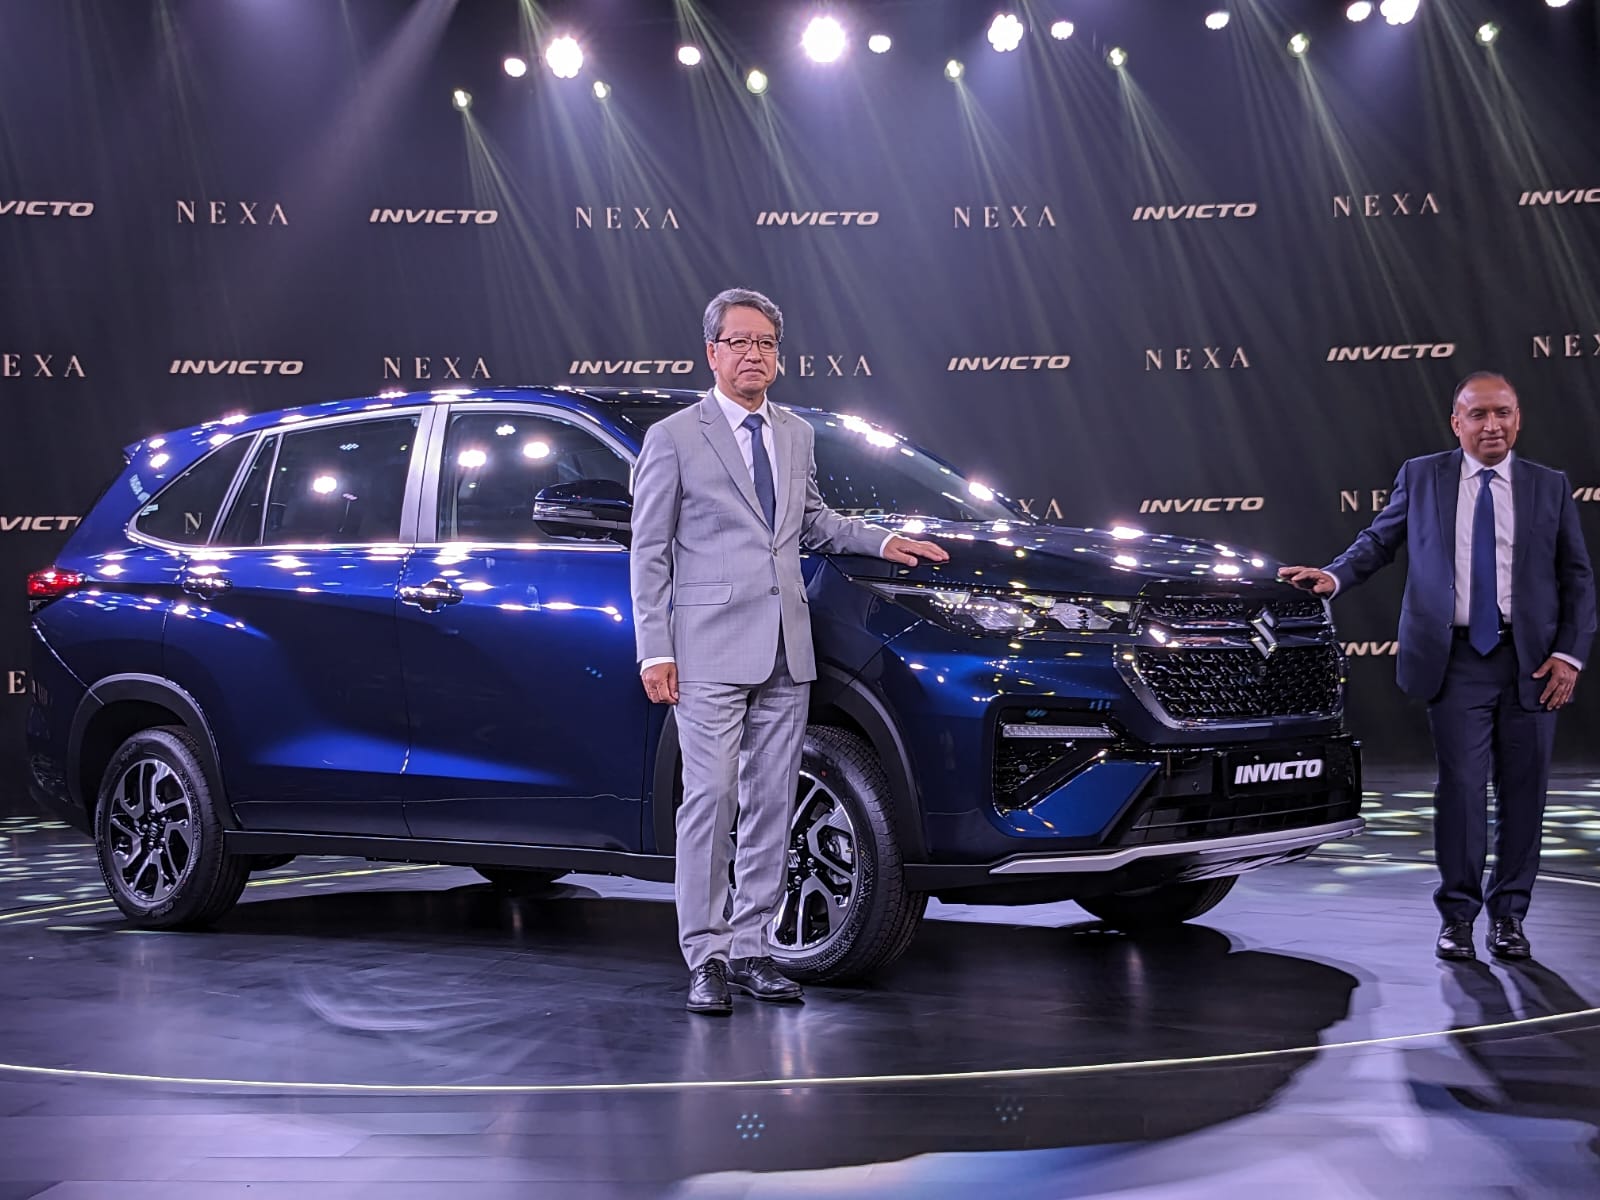
Maruti Suzuki India Ltd. will increase its market share in the sport utility vehicle segment with new launches, boosting margins, analysts said.
The company has launched the Grand Vitara, Jimny, Fronx and now the Invicto in a span of a year to gain back the market share lost due to its limited presence in the SUV segment.
The rising share of SUVs in overall sales has pushed the average selling price to over Rs 5 lakh per unit, leading to a surge in profit in the June quarter amid a low base.
"The company's passenger vehicle market share slipped from 51% in FY20 to 41% in FY23, led by a demand shift to SUVs. With an expanded portfolio, its SUV market share has improved from 18% in FY23 to 23% in 1QFY24," Jefferies said in a report.
Maruti Suzuki Q1 FY24 Highlights (Standalone, YoY)
Revenue rose 22% to Rs 32,327 crore. (Bloomberg estimate: Rs 31,833 crore).
Ebitda rose 56% to Rs 2,983 crore. (Bloomberg estimate: Rs 3,241 crore).
Ebitda margin was 9.2% versus 7.2% last year. (Bloomberg estimate: 10.2%).
Net profit rose 145% to Rs 2,485 crore. (Bloomberg estimate: Rs 2,466 crore).
The company also announced that it will acquire the Gujarat manufacturing plant from its Japanese parent, Suzuki Motor Corp., at book value.
The book value stood at Rs 12,700 crore as of March 31, but the amount is likely to change at the time of acquisition, analysts said.
However, brokerages lowered earnings-per-share estimates for Maruti Suzuki due to the limited efficiency benefits of the takeover.
Here's what brokerages made of Maruti Suzuki's performance in the first quarter:
Jefferies
Maintain 'buy' with a target price of Rs 11,500 a share, implying an upside of 17%.
An expanded portfolio is helping regain market share in SUVs.
Sees demand, product, and margin cycles favourably aligned for volume growth.
The acquisition of the Suzuki Gujarat plant may result in a 3-4% downside to earnings per share estimates for FY25–FY26.
Nomura
Remain 'neutral' with a higher target price of Rs 10,422 per share, a potential upside of 6.1%.
Expect overall market share to be stable at 42% as SUV gains may offset weakness in small cars.
As industry inventory rises and growth slows, a rise in advertising and promotional spends may offset operating leverage and commodity benefits.
Dilution of nearly 4% was factored into the valuation due to the Gujarat plant acquisition.
Motilal Oswal
Maintain 'buy' with a target price of Rs 11,150 a share, implying a potential profit of 14%.
Maruti Suzuki will outperform the industry with new launches leading to market share gains and margin recovery.
Stable growth in domestic PVs and a favourable product lifecycle augur well for Maruti Suzuki.
Cut FY25 earnings per share estimates by 1%, as the benefits of a higher average selling price and higher other income are more than offset by the SMG acquisition.
Nirmal Bang
Reiterate 'buy' with a target price of Rs 11,503 per share, implying an upside of 17%.
Production expansion to increase market share and increase SUV share to boost margins.
Expect sales momentum to continue in the coming quarters and SUV market share to increase.
Gujarat plant acquisitions will happen at book value, which as of March 2023 stood at Rs 12,700 crore and may vary at the time of acquisition.

-
Signature Play: The Classic Cocktail Is Dead. Or Is It?

Classic cocktails are disappearing from India's cocktail menus. But they're still being ordered, taught to bartenders and borrowed from. So, who's really having the last drink?
-
A New Samvat Wishlist: Inclusive Prosperity And Human Development
India has strengthened its economic foundations through infrastructure, digital access and enterprise. Its next growth chapter must deepen productivity, create better livelihoods and widen participation in prosperity.
-
Love, Sex Aur Dhokha: The Audacious Plot To Spy On Jensen Huang
A Taipei dinner, a Singapore chip buyer and a suspected Chinese asset: inside the alleged spy operation that got close to NVIDIA's Jensen Huang.
-
Ten Things I Learnt This Samvat
Patience can be a trap. Cheap stocks can stay cheap. Leverage can wipe you out. What did Samvat 2082 teach us? Niraj Shah writes on 10 lessons from the year gone by.
-
Talking Points This Week: Tech Nerves, FII Buying, And A Faraway Banking Shock
The global markets are not shining this Diwali. The exception in the large markets is, India.
-
Midterm Rally Lasted A Day. The Hard Reality Of A Divided US May Last Two Years | Opinion
Between a contested AI boom, a debt ceiling that arrives in 2027 and a president with every incentive to act alone, the next two years may prove more volatile than the first day's rally suggests.
-
Blue Wave Will Derail the AI Trade but Won't Dismantle the AI Era | Unhedged Position
The Democrats' sweep of the US Congress will see politics collide with economic forces both over the long and short term.
-
It's Time To Take The GST Council's Bet On Trust Global
Payment records can prove India's services exports, and clear, proportionate rules can bring foreign digital sellers into the tax net.
-
Opinion | India at 38: From Innovation Overperformer to Innovation Powerhouse
India now has 453 VC-backed deep science startups, 18 of them late-stage, after 117 percent growth since 2020. Laurus Labs, at USD 9.3 billion, is the most valuable deep science company in any middle-income economy outside China.









