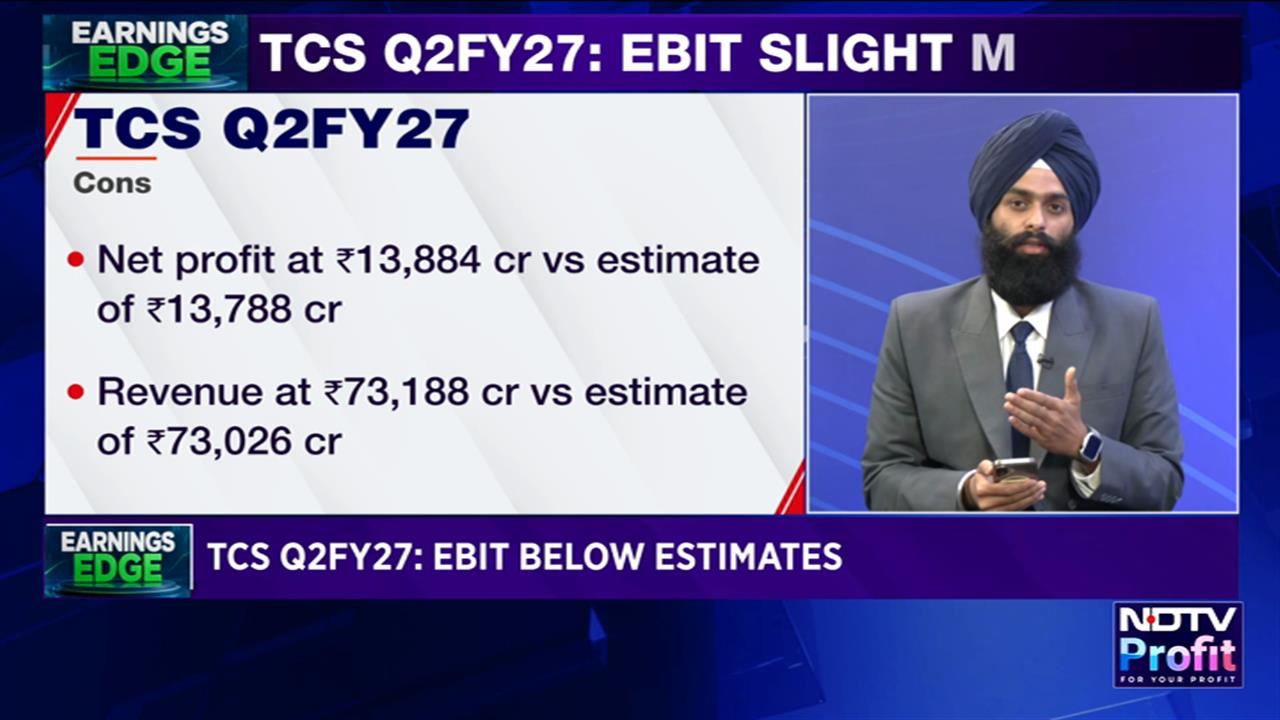
HDFC Securities highlighted that AI has emerged as the key growth driver for TCS, with annualised AI revenue surpassing $3 billion, 19.2% QoQ and 72% YoY, and contributing ~10% of revenue vs 8.6% in Q1. Non-AI revenue declined ~3% YoY, reflecting the deflationary impact of AIled productivity gains on traditional services. Adoption is broadening across AInative solutions, autonomous systems and AI-led business-process transformation, with BFSI, Manufacturing and Life Sciences leading.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
HDFC Securities Institutional Equities
HDFC Securities has retained its Add rating on Tata Consultancy Services, setting a target price of Rs 2,470 target price.
The brokerage expects TCS' growth momentum to improve gradually as international business strengthens and AI adoption accelerates, though elevated subcontracting costs and continued investments could keep near-term margins under pressure.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The brokerage highlighted that AI has emerged as the key growth driver, with annualized AI revenue surpassing $3 billion, 19.2% QoQ and 72% YoY, and contributing ~10% of revenue vs 8.6% in Q1.
Non-AI revenue declined ~3% YoY, reflecting the deflationary impact of AIled productivity gains on traditional services. Adoption is broadening across AInative solutions, autonomous systems and AI-led business-process transformation, with BFSI, Manufacturing and Life Sciences leading.
TCS also launched its AI Agent Hub and is strengthening agent governance, token-cost management and cybersecurity capabilities. Management indicated AI revenues carry better margins than the company average.
ALSO READ | Hexaware Technologies Share Price Jumps Over 12% After Partnership With Anthropic Claude For AI Services
The brokerage also adds that margins remain a key monitorable as elevated subcontracting costs, which are likely to rise further given the recent tightening of US immigration rules, and sustained investments in talent, partnerships and highgrowth areas are expected to weigh on near-term profitability.
MHP consolidation adds a further ~50 basis points headwind. Nevertheless, management reiterated its longterm margin aspiration of 26-28%, backed by growth, subcontractor optimisation and operating leverage.
Hiring momentum remains robust, with ~10,000 freshers added in the quarter and further hiring planned in H2, signalling confidence in the pipeline.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.