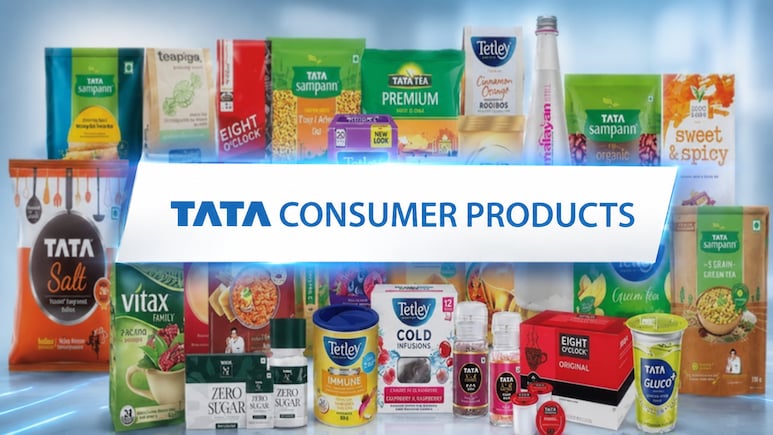
With the moderation in tea prices from its peak and strategic price hikes in the tea business, Motilal Oswal expect Tata Consumer Products' standalone gross margins to remain resilient in FY27. The company is expected to sustain its growth momentum, aided by the mid-tolong-term triggers such as strengthening and accelerating its growth business, expanding its product portfolio and innovation, enhancing its focus on premiumisation and health and wellness products, and higher innovation-tosales ratio.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Motilal Oswal Report
Domestic brokerage firm Motilal Oswal has reiterated its 'Buy' rating on Tata Consumer Products Ltd. with a Rs 1,230 target price, implying around 27% upside from the report current market price of Rs 969.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
It sees the company's growth portfolio as the next major growth engine, while the tea business remains resilient despite weather-related production disruptions.
The brokerage highlights that the company's growth portfolio has scaled up significantly, increasing its contribution to India business from ~8% in FY21 to ~31% in FY26, driven by the rapid expansion of Tata Sampann, Tata Soulfull, Capital Foods, Organic India and RTD beverages.
In contrast, the tea business' contribution declined from ~38%/63% in FY21 to ~24%/39% of the consolidated/India business in FY26, highlighting the company's growing diversification beyond its core tea franchise.
The portfolio has expanded across multiple high-growth categories, broadening Tata Consumer's presence beyond its traditional tea-led business.
The growth portfolio is expected to emerge as the next key growth driver, gradually reducing the company's dependence on its core tea business while reshaping the product mix and tapping into new and large market opportunities.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.