- EIH Ltd initiated with Buy rating by Axis Capital, target price Rs 385 per share
- EIH trades at 12-year low valuation, around 13x one-year forward EV/EBITDA
- Room additions expected to grow 9% CAGR from FY26 to FY31, mainly managed rooms
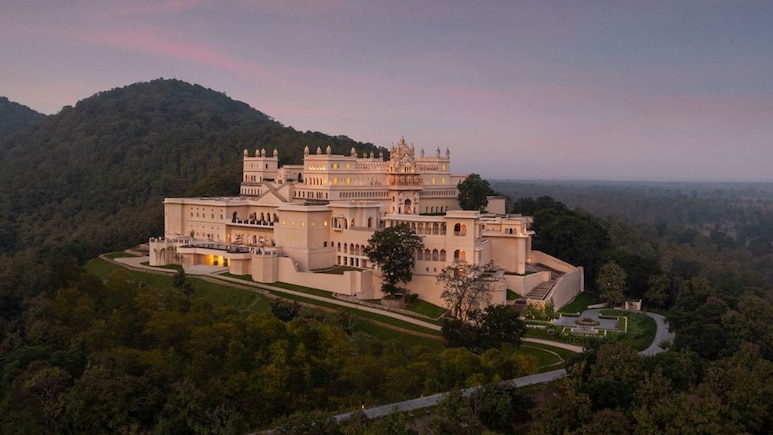
EIH Ltd, the company behind Oberoi and Trident, has been initiated with a Buy rating by Axis Capital, which has set a target price of Rs 385 per share, implying around 27% potential upside from the current price of Rs 303. The brokerage said the hotel company's attractive valuations, improving room-rate and Revenue Per Available Room (RevPAR) performance, and a reviving development pipeline could support a re-rating over the medium term.
Axis Capital said EIH's valuation has fallen to a 12-year low, with the stock trading at around 13x one-year forward EV/EBITDA, which it described as the lowest valuation in its history. The brokerage said EIH trades at a substantial discount to premium peers, including around 35% to Leela, 38% to ITC Hotels and 55% to IHCL.
The brokerage's target is based on valuing EIH at 17x September 2028E EV/EBITDA, a 15% discount to Leela. Axis Capital cited EIH's better return on capital employed as a factor supporting its valuation framework.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
EIH Pipeline Makes A Comeback
After a prolonged period of limited expansion, Axis Capital expects total room additions to grow at a 9% CAGR between FY26 and FY31, broadly in line with peers. The pipeline is increasingly focused on managed rooms, while international keys are expected to grow at a much faster 16% CAGR over the same period.
However, most of the new rooms are back-ended, meaning the larger earnings contribution is expected only after FY29. Axis Capital therefore expects near-term growth to be driven primarily by EIH's existing portfolio rather than new inventory.
Axis Capital expects EIH's recent ARR and RevPAR outperformance to continue, with near-term ARR growth estimated at 8-9%. It expects EBITDA to grow at an 11% CAGR over FY26-29, helped by EIH's high food-and-beverage contribution and rising management fees.
The company also has a strong balance sheet, with around Rs 9 billion of net cash. Axis Capital estimates FY26-29 capex at Rs 22 billion versus operating cash flow of around Rs 38 billion, leaving scope for further expansion.
ALSO READ: PB Fintech Target Price Cut 53% — Bernstein Calls Next 18 Months 'Do-Or-Die'
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.