Brokerages Expect Emami To Recover After Hit-And-Miss Quarter
.jpg?downsize=1010:568 "Brokerages Expect Emami To Recover After Hit-And-Miss Quarter")
Consumer goods maker Emami Ltd. reported a slight improvement in profit and operating margins, but missed analyst expectations in the fourth quarter.
Net profit in the March-ended quarter grew 1.5 percent to Rs 83.3 crore, compared to the same quarter last year. Revenue fell 4.1 percent to Rs 577.6 crore. The topline and bottomline both missed the consensus of analyst estimates tracked by Bloomberg.
Operational profit fell 2.1 percent, but operating margin expanded 70 basis points to 30.8 percent over the corresponding quarter of last year.
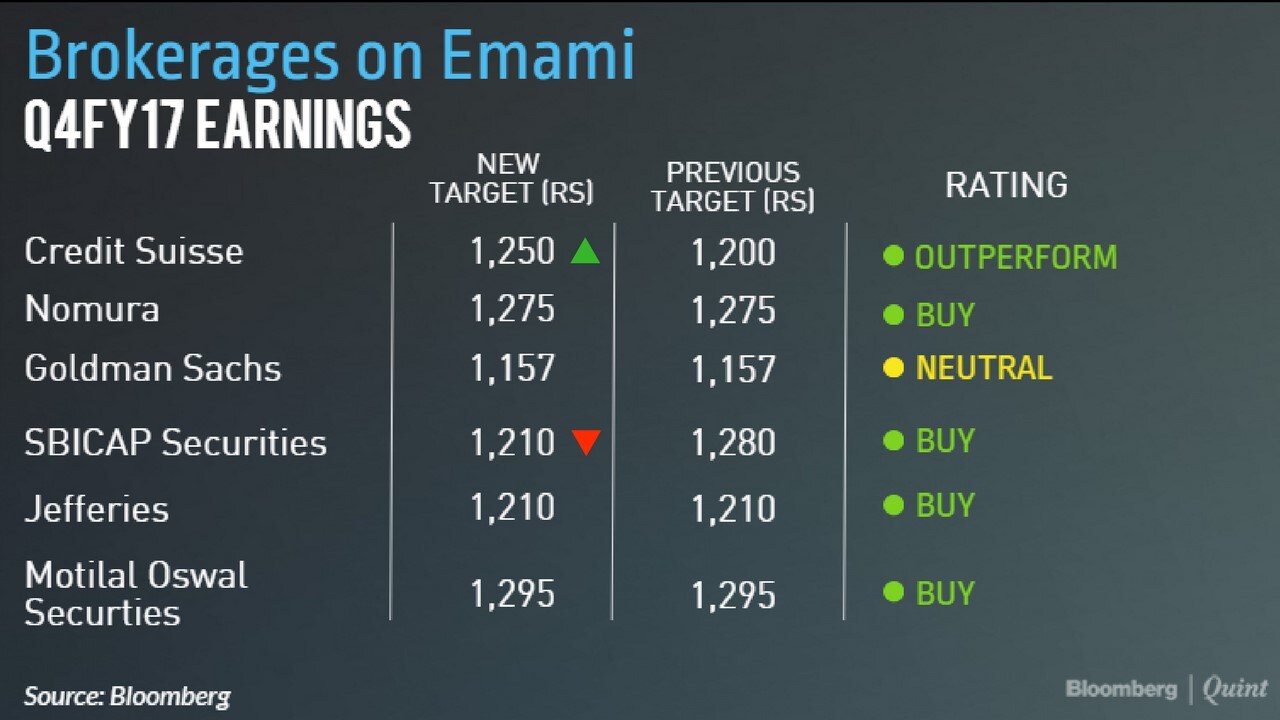
Here's what brokerages are saying about Emami post earnings
CLSA
Rating: Underperform
Target price: Will revisit after management concall on May 8.
- Impact of demonetisation continued to impact business in India.
- Overall, volumes down over 6 percent due to severe pressure in the Middle East, North Africa, Afghanistan, and Pakistan (MENAP) region.
- Emami reported a decline in gross margin after a long time, but hefty cuts in advertising and promotional spends helped maintain EBITDA margin
- Emami commissioned a new unit at Guwahati with an investment of Rs 300 crore in February. It should help the company keep its fiscal outflow low in the medium term.
Credit Suisse
Rating: Maintain Outperform
Target Price: Rs 1,250
- Steep decline in the Middle East were initially due to weakness in consumer demand but have now led to significant drop in stocks with traders.
- Demonetisation hurt company more due to its higher dependence on the wholesale channel than other FMCG peers.
- Expect recovery to kick in starting second quarter of FY18 post GST disruption.
- Key drivers: 1) New launches like Zandu gel and spray, 2) Recovery in international business (which declined 38 percent in Q4FY17) and 3) normalisation of wholesale channel.
- The company is looking to significantly increase its distribution reach by 1,00,000 outlets in FY18 to take up direct coverage to 8,00,000.
Goldman Sachs
Rating: Neutral
Target Price: Rs 1,157
- FMCG firm's earnings were below expectations on weak sales performance
- Key takeaway: Domestic growth at 3 percent was at similar levels as previous quarter due to channel disruption in wholesale and rural business.
- Brands like BoroPlus (-2 percent), healthcare range (-11 percent) and Kesh King (1 percent) reported weak growth.
- Will look for more details on gross margin performance on the earnings conference call.
- Upside risks: Faster new product growth, benefits from low commodity prices
- Downside risks: Failure of new product launches, higher competition
Nomura
Rating: Maintain Buy
Target Price: Rs 1,275
- Earnings were below expectations at the revenue and EBITDA level
- Core Naratna brand performed in line with expectations
- Growth prospects remain strong; expect bounce back in Q1 FY18
- Valuations look reasonable at 32 times FY19F price to earnings.

-
Medicine Pricing: Where Must Profit Stop?

India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.
-
Why Amazon And Flipkart Are Struggling To Beat Meesho In India's Smaller Cities
With 274 million users and lowest-cost logistics, Meesho is defending its value commerce crown against giants like Amazon and Flipkart.
-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families
The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.
-
You May Inherit The Business. You Must Earn Its Credibility.
Succession tests the founder's ability to share authority as much as it tests the next generation's readiness to assume it.










