TCS Q2 Results: Tata Consultancy Services' artificial intelligence (AI) business is growing, but brokerages remain divided on whether it can drive a meaningful acceleration in overall revenue and earnings.
While Jefferies expects just 4% earnings per share (EPS) compound annual growth (CAGR) over FY27-FY29, Citi has cut its target price on the stock, on the back of persistent growth challenges and further margin pressure.
The outlook is not uniformly bearish. Kotak Securities and Emkay retain ‘Add' ratings, Motilal Oswal maintains ‘Buy', and JPMorgan remains ‘Overweight'. UBS, meanwhile, sees healthy AI revenue growth and an uptick in hiring as encouraging signs for the IT services sector.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Jefferies retained ‘Underperform' with a target price of Rs 1,800, while Citi maintained ‘Sell' and cut its target to Rs 1,840 from Rs 1,875. Kotak Securities lowered its target to Rs 2,320 from Rs 2,450 but retained ‘Add'. Emkay retained ‘Add' with a Rs 2,600 target, Motilal Oswal maintained ‘Buy' with a Rs 2,400 target, JPMorgan retained ‘Overweight' with a Rs 2,300 target, and UBS maintained ‘Neutral' with a Rs 2,565 target.
The key question for the coming quarters is whether AI-led demand, new growth businesses and improving overseas performance can lift revenue growth without further eroding margins.
Jefferies, Citi See Growth Challenges Persisting
Jefferies expects TCS's earnings growth to remain subdued, forecasting a 4% EPS compound annual growth rate over FY27-FY29. It cut its earnings estimates by 1-2%, citing uninspiring growth and rising margin pressures.
ALSO READ: 10 Biggest Takeaways From TCS Q2 Results, Earnings Call: AI, Margins, Growth And What's Next
Although growth in the UK surprised positively, performance across other key regions remained weak. Jefferies believes these challenges will continue to constrain earnings.
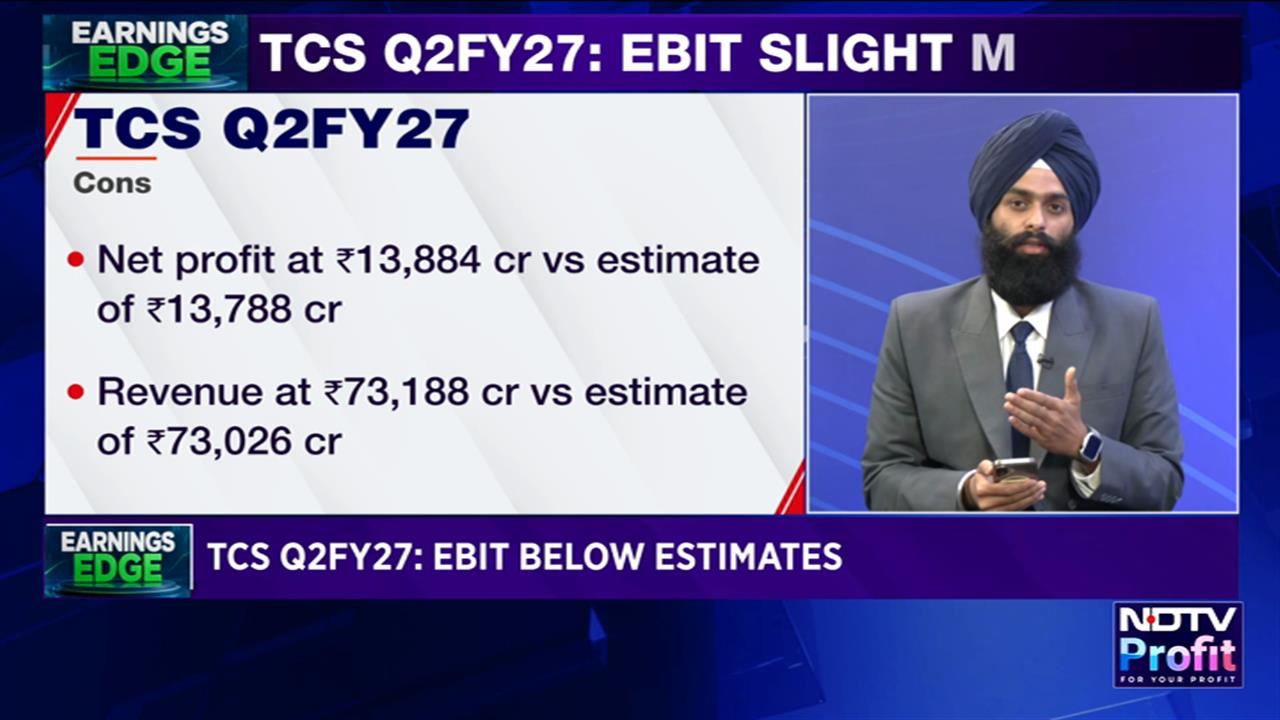
Citi also expects muted, low-single-digit revenue growth to persist. It described Q2 as largely in line but warned of further margin pressure, with FY27 margins likely to be lower than previously indicated. The brokerage believes growth challenges will continue weighing on TCS and sector valuation multiples.
Kotak Securities, Emkay Flag The Cost Of Chasing Growth
Kotak Securities retained Add but cut its target price to Rs 2,320 from Rs 2,450, arguing that TCS's growth push risks margin stability.
The brokerage considered Q2 growth and margins broadly in line, with reasonable growth in overseas business, but said muted deal wins disappointed somewhat. It also cautioned that the acceleration in AI revenue growth may be difficult to extrapolate and that investments to support growth are hurting the margin profile.
Emkay retained Add with a Rs 2,600 target price, despite describing the operating performance as softer than expected. Revenue grew 0.5% QoQ in constant currency terms to $7.6 billion, while the EBIT margin remained flat at 24%, largely due to higher investments.
Emkay said TCS continues to invest in frontier AI partnerships, talent and new growth engines, including data centre services, global capability centres, mid-market clients and sovereign cloud. These investments are likely to weigh on margins in the near term.
The brokerage cut its earnings estimates by 0.6–1.6% for FY27–FY29. However, it retained its target, citing the potential for a growing share of AI revenue, operating leverage from stronger growth and cost optimisation to support TCS's longer-term aspiration of 26–28% margins.
Motilal Oswal Retains Buy, JPMorgan Sees Cautious Demand
Motilal Oswal reiterated Buy with a target price of Rs 2,400, implying a potential upside of 16%. It said the growth outlook remained unchanged, although margins were under pressure and AI-led deflation concerns persisted.
Manufacturing, Hi-Tech and BFSI led Q2 growth, while regional markets and consumer business declined QoQ in constant currency terms. The brokerage expects revenue, EBIT and adjusted PAT to grow 6.5%, 4.3% and 4.9%, respectively, year-on-year in the second half of FY27.
JPMorgan maintained Overweight with a Rs 2,300 target price. It described Q2 growth and margins as broadly in line and expressed cautious optimism despite continuing demand uncertainty.
Management intends to raise margins from current levels in the second half, but JPMorgan cautioned that the outcome will depend on how growth evolves, particularly amid seasonal weakness.
UBS Sees AI Growth And Hiring As Positives
UBS maintained Neutral with a target price of Rs 2,565. The brokerage said the overall Q2 performance was broadly in line, while healthy AI revenue growth and an uptick in hiring were encouraging signs for the wider IT services sector.
TCS's annualised AI revenue had reached $2.6 billion in Q1FY27, up 13.6% quarter-on-quarter (QoQ), following growth of 27.7% in Q4FY26. While that provides a positive signal for AI demand, the broader brokerage commentary suggests that converting this momentum into stronger company-wide growth remains a challenge.
TCS Q2 Outlook Hinges On Growth And Margins
The brokerage views point to three key factors to watch over the coming quarters, including deal wins, discretionary client spending and margin delivery as TCS invests in AI and other growth areas.
For Jefferies and Citi, muted growth and pressure on profitability remain key concerns. Kotak Securities and Emkay also see near-term margin challenges, although both retain Add ratings. Motilal Oswal and JPMorgan remain constructive, while UBS sees AI growth and hiring as encouraging signs.
The central issue, for investors, is whether TCS can turn AI demand and its investments in new businesses into faster revenue growth and better operating leverage. Until that becomes clearer, the gap between AI momentum and overall earnings growth is likely to remain at the middle of the stock debate.
ALSO READ: What TCS Q2 Results Mean For Infosys, Wipro, HCLTech And Tech Mahindra
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.