Brokerages have highlighted opportunities across banks, IT, pharma, consumer electricals, housing finance and realty sector issuing fresh calls on ICICI Bank, Axis Bank, HDFC Bank, Federal Bank, Interglobe Aviation, Bajaj Housing Finance, Crompton Greaves Consumer Electricals, Punjab National Bank, Mankind Pharma, DLF, Ujjivan Small Finance Bank, while also sharing their outlook on ports and logistics and auto sector.
Bernstein on Axis Bank
- Maintain Outperform with TP of Rs 1600
- Lower credit cost drives EPS growth despite weaker core trends
- Loan growth remained robust and corporate-led, although strong borrowings growth pushed LDR sharply higher to ~95%
- NIM compression driven by FCNR deposits; Net operating income trends remain weak
- Improving asset quality offsets higher opex.
Kotak Securities on Axis Bank
- Maintain Buy with TP of Rs 1600
- A gradual recovery is taking shape
- Earnings beat driven by lower credit costs
- FCNR headwind is temporary; earnings trajectory set to improve from Q3
- The engine is yet to fire on all cylinders
- Operating environment remains supportive of earnings growth
- Valuation upside is likely to be constrained as the stock now trades close to HDFC Bank's valuation multiple.
JPMorgan on Axis Bank
- Maintain Overweight; Hike TP to Rs 1620 from Rs 1590
- Q2 review: PAT beats on NII, credit costs
- Attractive valuations underpin positive view
- Growth momentum healthy; Core NIMs (ex-FCNR NIM) report marginal recovery
- Improving asset quality.
Jefferies on Axis Bank
- Maintain Buy with TP of Rs 1700
- Q2: Core Ahead; Rebalancing of Loan Mix to Aid ROE Rise
- Q2 was ahead of estimates aided by better topline and lower provisions
- QoQ stable core NIMs was positive, but drag from FCNR-B was a tad more than estimate
- Asset quality continues to improve
- Better NIMs & lower credit cost can lift ROE next year
- Valuation is attractive
- Axis stays among top picks
Citi on Axis Bank
- Maintain Buy with TP of Rs 1620
- Headline NIM Distorted by FCNR Drag; Core Margins Stable
- Slippages and Credit Costs Moderate Sequentially
- Underlying Asset Quality Resilient
- Broad-Based Credit Momentum Across Segments; Outpacing Industry growth
- Opex Elevated Due to One-offs Driving PPOP Down.
ALSO READ | Five Stocks To Buy Today: Dr. Reddy's, Indian Hotels, Shyam Metalics, And More | October 19, 2026
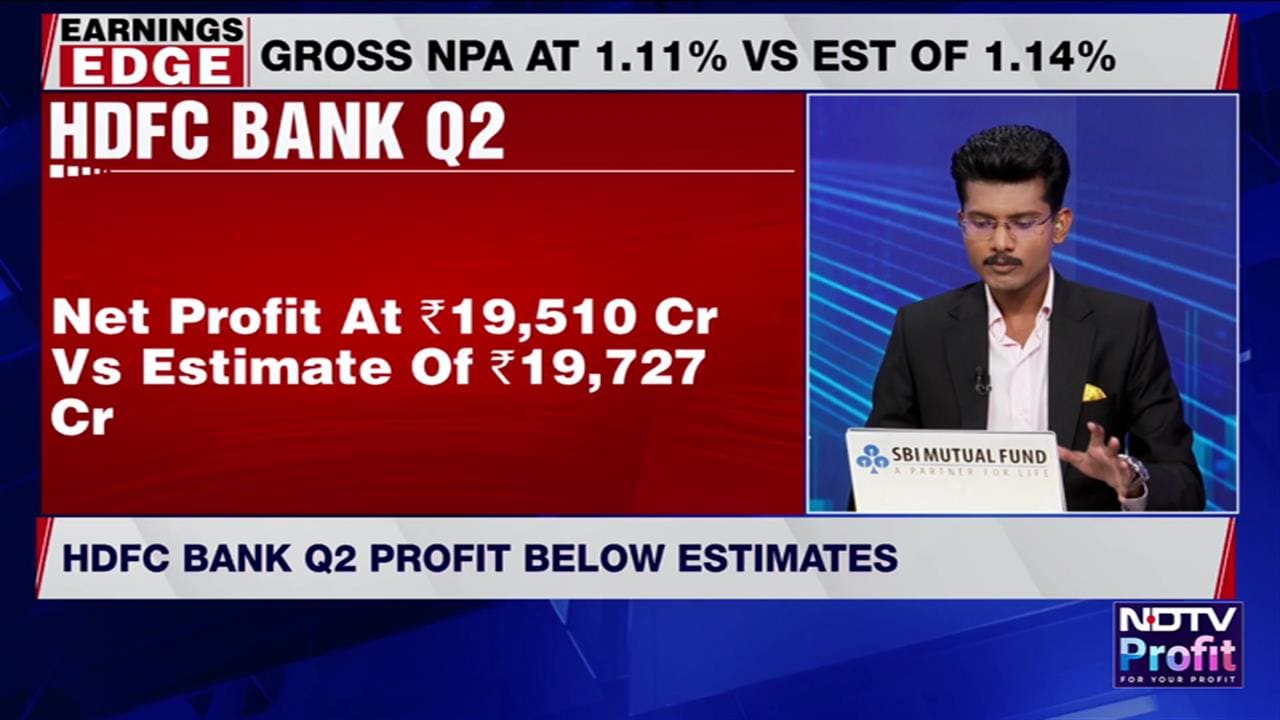
Citi on HDFC Bank
- Maintain Buy; Cut TP to Rs 880 from Rs 970
- NIMs Compress, Growth Trail System, Fees Shield PPoP
- Constrained Buffer to Cap Relative Growth Trajectory
- Asset Quality Resilient; Seasonal Agri Pressures Wane; Credit Costs Maintained at 46bps
- Execution Key Amid Leadership Transition
Jefferies on HDFC Bank
- Maintain Buy with TP of Rs 880
- Core NIMs hold-up better; reallocation of assets to aid NIMs
- Asset quality strong
- Improvement in retail deposit growth and re-risking loans can aid profitability
- New CEO & exit of DMD may lead to more changes in mgt-team
JPMorgan on HDFC Bank
- Maintain Overweight; Cut TP to Rs 970 from Rs 990
- Q2 review: Steady quarter, NIM outlook positive;
- Advances growth healthy, retail growth picking up
- FCNR drives strong deposit growth; CASA growth muted
- Healthy asset quality provides earnings support:
- Await details on strategic priorities.
Bernstein on HDFC Bank
- Maintain Outperform with TP of Rs 1150
- Weak earnings growth story continues
- Loan growth led by corporate and mid-market segments
- Healthy NII growth despite modest margin pressure
- Opex remains contained; asset quality stays resilient.
Kotak Securities on HDFC Bank
- Maintain Buy with TP of Rs 1050
- A new chapter begins, but the challenges remain familiar
- Weak treasury income limits earnings growth
- Q2, broadly in line with operating profit growth
- NII growth continued to improve, NIM contracted by 10 bps QoQ, primarily due to the impact of FCNR deposit mobilization
- Attractive valuations, but execution remains the missing piece
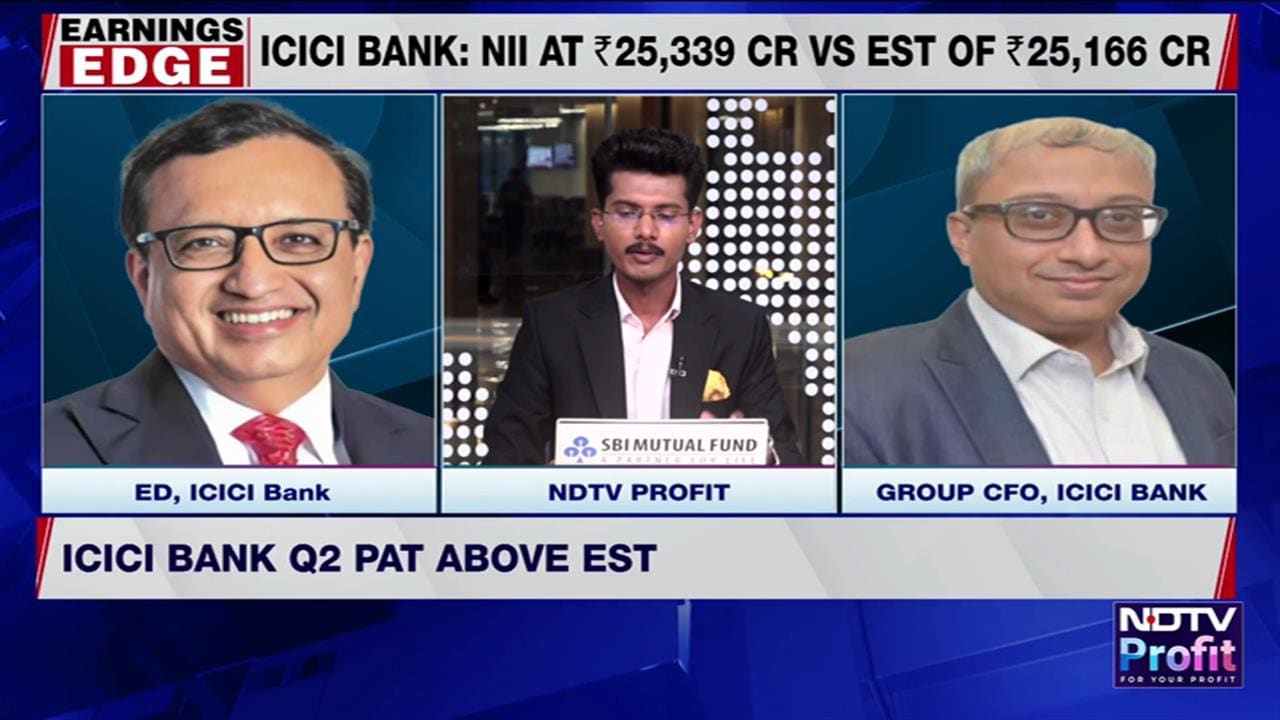
Citi on ICICI Bank
- Maintain Buy with TP of Rs 1770
- NII Up 4% QoQ; NIM to Trough in 3Q Before Recovery
- Asset Quality Pristine; Robust Recoveries Anchor Modest Credit Costs
- FCNR Surge Outpaces Market Share Gains, Lifts NII but Dilutes NIM
- Clearly Emerging as a Growth Leader; Wholesale & Business Banking Propel Growth
Jefferies on ICICI Bank
- Maintain Buy with TP of Rs 1750
- Stronger NII growth; normalisation of asset mix will aid margins
- Asset quality is strong & lower credit cost aided profits
- ICICI stays among top-picks.
JPMorgan on ICICI Bank
- Maintain Overweight; Hike TP to Rs 1800 from Rs 1735
- Q2 review: Broad-based beat; NIMs to expand in Q4
- Balance sheet growth strong, retail mix improving
- Asset quality delivery strong; no impact of geopolitical uncertainty visible
- Weak CASA growth key negative.
Kotak Securities on ICICI Bank
- Maintain Buy with TP of Rs 1800
- Exceptional results, exceptional execution
- Strong earnings driven by growth, cost discipline and credit quality
- Strong foundation with fewer issues gives headroom for superior execution
- Bank continued to generate healthy CASA growth and low credit costs thanks to lower slippages, resulting in a solid RoE print of 17%
- Anchored by relative valuations but deserves a higher premium
Bernstein on ICICI Bank
- Maintain Outperform with TP of Rs 1800
- Delivered another standout quarter, reinforcing its position as the fastest-growing large private bank
- Industry-leading growth, best-in-class profitability
- NIM compression in line with peers; treasury losses weigh on net operating income
- Contained opex and lower credit costs support profitability
Citi on Bajaj Housing Finance
- Maintain Sell; TP cut to Rs 82 from Rs 85
- AUM growth healthy; driven by strong traction in LRD and LAP
- Disbursement growth robust YoY; QoQ growth softer due to moderation in core housing demand.
- NIMs remained largely stable; lower funding Costs offset yield pressure in prime housing segment.
- Asset quality remained comfortable with GNPA/NNPA stable
- Credit cost normalized but remains within a benign range.
- Mgmt retained strong growth outlook with 21-23% AUM growth guidance
- Some pressure on margins expected.
- Sambhav continues to scale rapidly and is emerging as a key growth driver
- Mix shift towards LRD and Sambhav is supporting growth
- Increasing competitive intensity in prime housing remains a key overhang.
- Proposed insurance regulations could trim PBT by 6-7%
- Investments in Sambhav and expansion to keep employee costs elevated over the next year.
HSBC on Bajaj Housing Finance
- Maintain Reduce; TP at Rs 76
- Profit beat estimates driven by better-than-expected NIM.
- AUM growth remained healthy led by LRD, LAP and affordable housing loans.
- NIM improved QoQ aided by lower borrowing costs.
- Mgmt expects NIM compression in FY27 due to rising funding costs and portfolio mix.
- Sambhav affordable housing portfolio expected to become a meaningful part of AUM.
- Employee costs to remain elevated due to invest. in distribution and expansion.
- Insurance commission regulations, if implemented, could impact fee income.
ALSO READ | Stock Market Today: All You Need To Know Before Going Into Trade On October 19
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Citi on Crompton Greaves Consumer Electricals
- Maintain Buy; TP Rs 400
- Broad-based beat across segments with revenue, Ebitda and PAT ahead of estimates.
- ECD remained the key growth driver with strong growth and margin expansion.
- Lighting growth improved as Q1 supply-chain disruptions eased
- Subsidiary BGAL delivered strong revenue growth; margins remained under pressure.
- 11-15% pump price hikes underway; most cost inflation already passed through.
- Demand remained healthy with positive volume growth across categories.
- Solar business scaling up well; growth in newer categories.
- Growth outlook strong aided by product launches, brand spends and channel expansion.
- Lighting margins impacted by execution of legacy B2B orders at lower contracted prices.
Jefferies on Crompton Greaves Consumer Electricals
- Maintain Buy; TP cut to Rs 305 from Rs 330
- Q2 performance was in line; double-digit sales growth led by South and West markets.
- ECD remained the key growth driver aided by fans, pumps and new product launches.
- Pump demand stayed strong; aided by market share gains and price hikes.
- Domestic Appliances delivered healthy growth led by mixer grinders and kitchen appliances.
- Rooftop solar execution on track; aiding growth in emerging segments.
- Lighting margins remained under pressure due to B2B mix and Outdoor Lighting weakness.
- Input cost inflation continues to be a monitorable despite recent price increases.
- Butterfly delivered healthy growth; margins remained subdued.
- Mgmt remains constructive on growth; aided by product launches and market share gains.
- Valuations remain attractive despite near-term margin pressure.
HSBC on Crompton Greaves Consumer Electricals
- Maintain Buy; TP at Rs 330
- Revenue and margin beat estimates; Ebitda margin expanding despite commodity inflation.
- Broad-based double-digit growth across ECD, Lighting and Butterfly.
- ECD remained the key growth driver, led by fans and pumps.
- 80% of cost inflation has already been passed on through price hikes.
- Exports grew over 70% supported by Africa, Middle East and Southeast Asia.
- Lighting delivered healthy growth aided by operating leverage and cost control.
- Butterfly growth remained strong; Restructuring efforts expected to improve profitability.
- Solar business continued to scale up aided by rooftop solar and solar pumps.
- Attractive valuations and long-term growth opportunities in solar and adjacent categories.
Kotak Institutional Equities on Crompton Greaves Consumer Electricals
- Maintain Buy; TP revised at Rs 350
- Revenue growth beat estimates.
- Growth led by strong performance across ECD, Lighting and Butterfly.
- ECD remained the key growth driver led by fans, pumps and improving exports.
- Ebitda margin expanded despite commodity inflation
- Margins aided by price hikes, operating leverage and cost savings.
- 80% of raw material inflation passed on through price increases.
- Pump demand remained healthy; BLDC fans continued to gain traction.
- Butterfly delivered strong growth led by mixer grinders and kitchen appliances.
- Exports grew over 70%; strong demand from Africa and Intl markets.
- Solar pumps saw temporary moderation due to PM-KUSUM tender slowdown.
Citi on Federal Bank
- Maintain Neutral; TP Rs 360
- Loan growth accelerated driven by retail, gold loans and corporate banking.
- FCNR-linked lending contributed meaningfully to growth
- NIMs resilient as lower deposit costs offset pressure from overseas leveraged-loan exposure.
- Mgmt expects margin support from repo rate transmission and a shift towards higher-yielding segments.
- Asset quality remained healthy with slippages under control and credit costs below 50 bps.
- Retail and business banking drove slippages
- CASA moderated slightly despite strong deposit mobilisation.
- FCNR mobilisation aided deposit growth
- Fee income momentum remained strong, aided by distribution income and insurance fees.
- Treasury gains boosted other income;
- Operating expenses remained elevated due to ESOP-related costs.
- Mgmt expects further NIM improvement over the medium term.
- Key monitorable remains inorganic acquisition opportunities and execution.
Kotak Institutional Equities on Federal Bank
- Maintain Add; TP at Rs 375
- Loan growth remained strong driven by healthy retail and business banking traction.
- NIM moderated due to lower policy rates; fee income remained healthy.
- Asset quality stayed stable; slippages contained
- RoA improved QoQ; Profitability to improve on back of lower funding costs.
- Fee and other income supported by insurance distribution and treasury gains.
- Proposed acquisition a key overhang; awaits clarity
Citi on Punjab National Bank
- Maintain Sell; TP raised to Rs 110 from Rs 103
- Loan growth exceeded guidance driven by retail, agri and overseas book growth.
- FCNR-funded overseas lending a key growth driver
- NIM expanded as lower funding costs
- Run-off of low-yield corporate exposure lifted yields.
- Mgmt reiterated loan growth and NIM guidance; further margin accretion expected.
- Asset quality remained resilient with GNPA improvement and manageable slippages.
- Provision buffers strengthened further
- Credit cost was near zero due to provision reversals; no material stress
- Deposit growth aided by FCNR inflows and replacement of high-cost bulk deposits.
- Cost of funds is on a declining trajectory
JP Morgan on Mankind Pharma
- Maintain Neutral; TP Rs 2,700
- ACTx acquisition gives entry into next-gen CAR-T therapies & advanced cell therapy platforms.
- Acquisition expands innovation pipeline beyond core branded generics franchise.
- CAR-T platform improves durability, reduces antigen escape & targets multi-antigen.
- ACTx remains an early-stage, pre-revenue asset;
- CAR-T market offers a large long-term opportunity
- Development timelines and commercialization remain uncertain.
- Near-term financial impact is expected to be manageable
- Investment spending likely to be phased over time.
- Operating expenses to remain elevated due to product development and platform expansion.
- Key monitorable remains capital allocation discipline and execution of innovation strategy.
Jefferies on Mankind Pharma
- Maintain Buy; TP Rs 3,220
- ACTx acquisition provides access to next-gen CAR-T therapies
- Strengthens Mankind's innovation portfolio.
- ACTx's pipeline targets non-Hodgkin lymphoma and small-cell lung cancer
- ACTx remains an early-stage biotech platform
- Asset portfolio is largely preclinical, delaying revenue visibility and monetisation prospects.
- Sees strategic merit in expanding beyond the core domestic formulations business.
- Near-term impact manageable; Development spending could remain elevated.
- Uncertainty on commercialisation timelines and monetisation of the assets.
- Visibility on capital allocation, development and strategy execution remains a key monitorable.
Citi on LTM
- Maintain Sell; TP cut to Rs 3,590 from Rs 3,620
- Q2 performance was largely in-line; margins slightly ahead of estimates.
- TTM TCV declined YoY; a shift towards shorter-tenure AI-centric deals.
- Financial Services key growth driver; Production grew on recovery in large deals.
- Deal TCV fell to a two-year low; Top client revenue declined
- Client concentration remains a monitorable.
- Subcontracting costs remained elevated
- Tech & Services segment impacted by seasonal renewals and softness in the Saudi business.
- Management constructive on growth momentum; stronger H2 expected versus Q1.
- AI revenues continued to scale
Jefferies on LTM
- Maintain Underperform; TP raised to Rs 3,480 from Rs 3,360
- Q2 revenue was largely in line; profitability missed estimates due to lower other income.
- Growth impacted by weakness in the Saudi biz and seasonal client-specific headwinds.
- Financial Services is key growth driver; Tech & Services saw softness.
- Order inflows declined sharply due to a higher mix of shorter-tenure AI-led deals.
- Deal wins remained weak; TCV falling below recent run-rate levels.
- Headcount addition remained modest despite elevated fresher hiring
- Mgmt expects stronger H2 growth; AI-led work continues to see lower pricing
- Margins to remain range-bound as pricing pressure in traditional services offsets efficiency gains.
- Jefferies cut FY27-29 estimates and remains cautious on growth outlook
Jefferies on Ports & Logistics
- Major ports drove industry growth in Sep-26; non-major port volumes declined.
- Adani Ports' domestic port growth likely moderated due to temporary disruption at Mundra port.
- Container volumes at ports outperformed rail led by resilient transshipment traffic.
- EXIM trade rose 13% YoY, led by container, coal, POL, gems and jewellery cargo.
- Freight rates rebounded sharply amid Middle East tensions and shipping route disruptions.
- Port volumes grew 6% YoY led by strong growth at major ports.
- Adani Ports reported double-digit volume growth, excluding international operations.
- Freight costs remain elevated; fuel accounts for a significant portion of trucking costs.
- Medium and Heavy CV registrations remain healthy
- Prefers Adani Ports and JSW Infrastructure on volume growth, operational efficiencies.
- Concor is a key beneficiary of the Dedicated Freight Corridor connectivity to JNPT
HSBC on Ujjivan Small Finance Bank
- Maintain Buy; TP raised to Rs 90 from Rs 83
- Q2 PAT beat estimates driven by strong fee income, lower opex and lower credit costs.
- Mgmt remains confident of exceeding FY27 RoA guidance.
- AUM growth remained strong led by healthy traction in secured loans.
- Secured loan mix continued to improve supporting portfolio diversification.
- Credit costs declined sharply; asset quality remained stable.
- NIM moderated due to lower yields; profitability remained healthy.
- Mgmt expects NIM improvement in H2FY27.
- Cost-to-assets to remain lower than earlier guidance
- Proposed preferential issue will aid in growth capital & future expansion.
- Raised FY27-29 estimates on stronger growth, better efficiency and lower credit costs.
Jefferies on DLF
- Maintain Buy; Hike TP to Rs 830 from Rs 825
- Strong Cash Generation, Launch Momentum Revived
- New launch revival after 4 quarters, and continued luxury property demand, should help DLF meet its pre-sales guidance for FY27E
- Only 22% of the Rs 20000 cr pre-sales guidance has been met in H1
- Launch of Aureva though, we believe, marks a positive turn in new project momentum
- Lease business remains steady with strong 95%+ occupancies
- FY27 P&L performance should stay patchy though Q2 was a beat on other income
- Cash generation remains strong with Rs 61/share net cash on development company
CLSA on Auto Sector
- Auto pulse check: All eyes on festive
- On street demand momentum remains stable
- Auto retail registrations in H1 Oct-26 remained broadly stable MoM; however, YoY registrations declined sharply
- High base from last year and inauspicious buying period impacted
- Channel checks and interactions with dealers and OEMs suggest they continue to expect mid- to high-single-digit volume growth
- Dealers across brands highlighted that inquiry levels were healthy and higher YoY during Dussehra
- Inventory levels are largely at normal levels, while discounting has also remained broadly stable
- M&M remains top pick followed by Bajaj Auto and ATHER ENERGY
Nomura on IndiGo
- Maintain Buy with TP of Rs 6000
- Government to notify airfare rules within two weeks
- Think visibility remains low on the new rules
- Nevertheless, base case is higher oversight/ transparency on the margin on airfares
- Expect stronger disclosures related to fares/ancillary components rather than direct government intervention.
Jefferies on IndiGo
- Maintain Buy; TP at Rs 5,840
- West Asia conflict continues to keep fuel costs elevated, delaying earnings recovery.
- Airline is using disciplined capacity deployment and higher fares to protect profitability.
- Fare hikes are helping offset cost pressures but weighing on passenger growth.
- Fleet additions a key growth driver despite ongoing aircraft grounding issues.
- Winter schedule should support capacity growth and stronger ASK growth in H2FY27.
- Industry-wide focus on cost control is helping airlines manage inflationary pressures.
- Potential fare regulation changes could provide greater pricing flexibility.
- Earnings recovery depends on easing geopolitical tensions and lower fuel costs.
- Remains positive on long-term growth but sees near-term profitability pressure from elevated fuel prices.
Disclaimer: The views and opinions expressed by the investment advisers on NDTV Profit are of their own and not of NDTV Profit. NDTV Profit advises users to consult with their own financial or investment adviser before taking any investment decision.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.