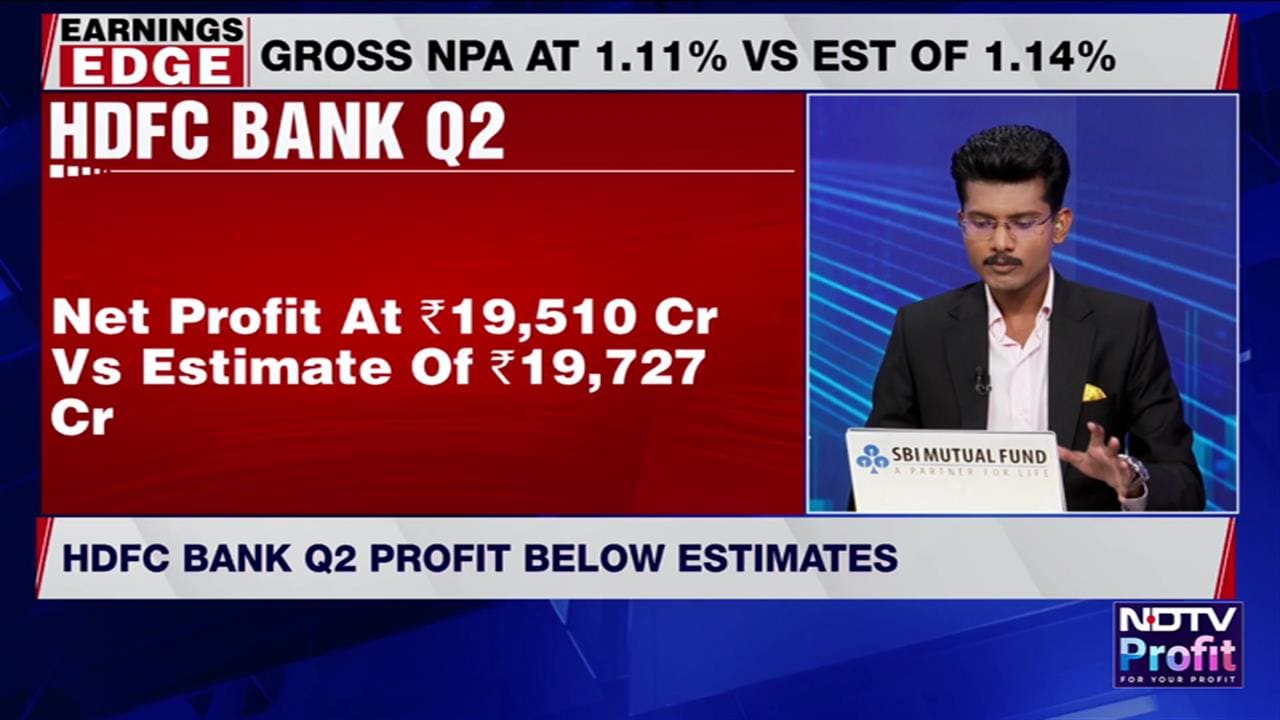
HDFC Bank Ltd. may explore ways to reduce the pressure to raise corporate deposits as incoming Managing Director and Chief Executive Officer Anup Bagchi prepares to set out his priorities for the lender. Outgoing CEO Sashidhar Jagdishan said the bank could consider alternative balance-sheet strategies, including some non-deposit funding, to increase the share of retail deposits over time.
“Now, as I am sure Anup in the next weeks or a couple of months' time will unveil his strategy, and one of the things is how do we create less pressure on the system to minimize the intake or inflow of corporate liabilities and then ensure— so these are some of the things that will be a part and parcel of his thought process as he unveils to the world at large, including yourselves, in probably a month's time or so," Jagdishan said during the second-quesrter earnings call on Saturday.
Jagdishan's comments point to a possible change in emphasis in the bank's funding strategy, rather than a formal decision to reduce corporate deposits. He said the bank would continue to need non-retail liabilities because demand remained strong across its corporate, micro, small and medium enterprise (MSME) and retail businesses. He did not specify a target for reducing corporate deposits or detail the alternative funding strategies under consideration.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
A Possible Shift In Funding Strategy
Jagdishan said the bank wanted to reduce the pressure on the system by minimising the need to bring in corporate liabilities. He added that alternative balance-sheet strategies, including some non-deposit options, could help increase the proportion of retail deposits over time.
The comments come as HDFC Bank continues to build its retail deposit franchise while managing funding requirements arising from its large balance sheet. Jagdishan said the bank had doubled its distribution network over the previous five years and expected that network to mature over the next five years. The bank has also been working to improve customer engagement, account acquisition and digital journeys, including the bundling of products and services.
READ | HDFC Bank Expects NIM To Improve From Q3 As Loan Repricing Kicks In
He said exceptional outflows across several deposit categories had obscured the underlying momentum. These included deposits from small MSME customers, government deposits, deposits inherited from erstwhile HDFC Ltd. and some older leveraged FCNR(B) deposits. Jagdishan said the impact of these outflows could ease over time, allowing the bank's underlying deposit momentum to become more visible.
The bank's Q2 FY27 performance showed growth in deposits and customer acquisition. Deposits increased 18.8% year on year on a reported basis, including a four-percentage-point contribution from the special FCNR(B) window. Overall CASA grew about 10.8%, while retail CASA grew 11.2% year on year, compared with 9% a year earlier.
HDFC Bank added about 1.7 million liability relationships during the quarter, 25% more than in Q1 FY27 and 33% more than in Q4 FY26. Core incremental deposits per branch per day were 2.3 times the Q1 level, according to management.
READ | Exit Of The Anchor: Kaizad Bharucha's Three-Decade Run Inside India's Largest Private Bank
How The Commentary Has Evolved
In the Q1 FY27 earnings call, management said it wanted to move the CASA ratio towards pre-merger levels over time. It described this as an endeavour rather than a near-term target, referring to a ratio of about 38% around the time of the merger and 40% before it.
Management also acknowledged that the bank could not ignore corporate and wholesale customers. It said wholesale deposits accounted for a larger share of the deposit mix than before and that corporate relationships remained important for deposits, cash management and other banking services. The bank's focus on retail deposits reflected their funding-cost advantage, but it still needed to serve corporate customers across their banking requirements.
The Q4 FY26 call had highlighted the bank's effort to build a more granular deposit base. Management said deposits below Rs 3 crore accounted for 47% of annual net deposit accretion in FY26, compared with 31% in FY25. It presented the increase as evidence of its focus on deposits it considered more stable and sustainable.
The latest comments add another possible lever to that effort: adjusting the balance sheet and considering alternatives to relying as heavily on corporate liabilities to meet funding needs. However, Jagdishan did not announce a new deposit-mix target or a timetable for any change.
Bagchi said he would engage with regulators, customers, shareholders and other stakeholders before setting the bank's organisational priorities. The direction of any changes to HDFC Bank's funding strategy will therefore depend on the priorities he sets out after those consultations.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.