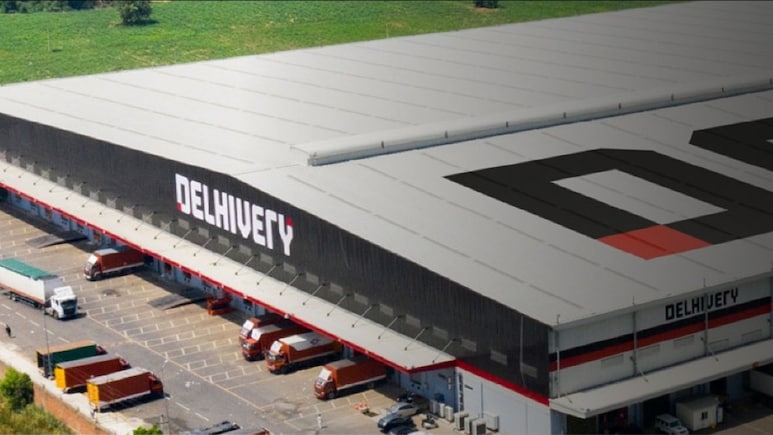
Morgan Stanley has reiterated its equal‑weight rating on Delhivery Ltd. while raising its target price to Rs 470 from Rs 445, reflecting growing confidence in the logistics firm's medium‑term growth prospects. The brokerage cites rising numbers amid an improving industry environment. The current market price of the stock is Rs 429.
According to Morgan Stanley, the broader logistics and third‑party logistics (3PL) industry continues to experience favourable conditions, with volume momentum expected to remain robust in the coming quarters. Industry volumes are projected to grow 15–20% year‑on‑year, and Delhivery is expected to outpace this expansion as stronger players gain market share amid improving volume growth numbers.

-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
-
 "I Am A Material Man In A Material World': Quantum Advisors' Ajit Dayal On NDTV Profit Ignite
The brokerage firm is now estimating Delhivery's volume growth at a 19% CAGR over FY26–28. This adjustment incorporates expectations of the company sustaining a market share above 50% within the 3PL segment. Correspondingly, revenue is projected to grow at 16%+ CAGR over the next two years as compared to the roughly 9–10% CAGR seen between FY23 and FY26 estimates.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
ALSO READ: Stock Picks: Brokers, AMCs, Paytm, Delhivery, BSE And More On Brokerages' Radar
On Delhivery's strong operating leverage, Morgan Stanley says that the firm is seen to benefit from Ebitda margin expansion from an estimate of 14.2% in FY26 to approximately 17% by FY28—aided by declining corporate overheads and narrowing losses in newer business lines. Adjusted Ebitda margins are forecast to almost double from 4.2% to 8.3% over the same period, implying a 63% adjusted EBITDA CAGR across FY26–28.
In line with these revisions, Morgan Stanley has raised its adjusted Ebitda forecasts by 4.4–6.8% for FY27–28. While the brokerage maintains its 'equal‑weight' stance on valuation grounds, it acknowledges the company's improving fundamentals and its strengthening position within the industry.
Out of 23 analysts tracking the company, 19 maintain a 'buy' rating, while three maintain a "hold" and one maintains a "sell" rating, according to Bloomberg data. The average 12-month consensus price target of Rs 522.55 implies an upside of 22.1%
ALSO READ: Delhivery's Q3 Has Brokerages Buzzing — Is The Turnaround Finally Happening?
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.