Eicher Motors Q1 Result Review: New Entrants May Dent Market Share, Say Analysts
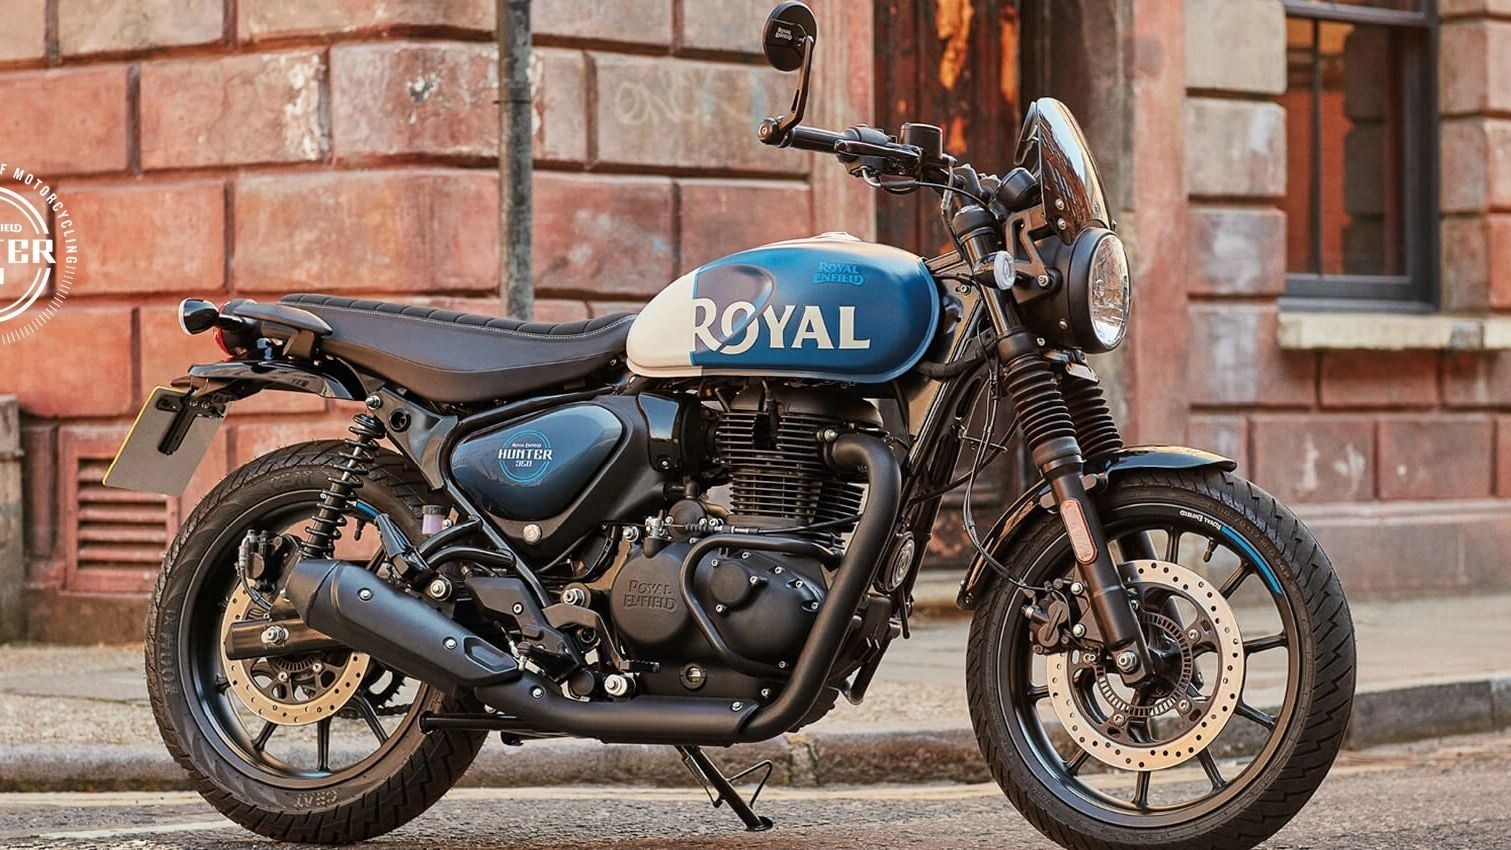
Eicher Motors Ltd.'s dominance in the middle-weight motorcycle segment may be hit as price competitive launches by competitors impact the Royal Enfield's market share.
The company posted its highest-ever quarterly revenue and profits for the fourth consecutive quarter and currently enjoys over 90% market share in the segment.
"We believe these bikes offer an attractive proposition for customers, especially if the vehicles perform well on the roads. We assume RE's market share in 250cc+ bikes will fall from 93% in FY23 to 75% in FY25," Jefferies said in a report.
Triumph-Bajaj brought the Triumph Speed 400 and the Scrambler 400X to an ex-showroom price starting at Rs 2.33 lakh for the former. Harley-Hero MotoCorp unveiled the X440, starting at Rs 2.29 lakh. The new entrants command more than a 20% premium over Royal Enfield's one of the best selling models, the Classic 350, which is priced at Rs 1.93 lakh.
Dolat Capital Market Pvt. expects that increasing competitive intensity will restrict volume growth and pricing power for Royal Enfield.
Eicher Motors Q1 FY24 Highlights (Consolidated, Year-on-Year)
Revenue rose 17% to Rs 3,986 crore (Bloomberg estimate: Rs 4,029.5 crore).
Ebitda grew 23% to Rs 1,021 crore (Bloomberg estimate: Rs 968.5 crore).
Ebitda margin was at 25.6% versus 24.5% last year (Bloomberg estimate: 24%).
Net profit jumped 50% to Rs 918 crore (Bloomberg estimate: Rs 848 crore).
The entry of new players is likely to expand the market, and when a company dominates a market, there's only one way for the market share to go, Siddhartha Lal, managing director at Eicher Motors, told the media in a call.
However, he sounded confident of maintaining a market share of 80–85% of a larger market in the medium term and said the brand is a fortress that will not be easy to penetrate.
Here's what analysts made of the company's Q1 performance:
Jefferies
Retains 'buy' rating with a target price of Rs 4,000 a share, implying an upside of 18%.
Expects tailwinds for the company, but keeps the stock lower in pecking order amid fresh wave of competition.
Demand recovery, industry premiumisation and potential to grow exports will drive the stock.
New bikes from competition offer attractive proposition for customers, especially if the vehicles perform well on the roads
Motilal Oswal Financial Services
Reiterates 'neutral' rating with target price of Rs 3,600 per share, a potential upside of 7%.
Sees Ebitda margin range-bound over the next few quarters, with limited scope of price hikes due to stable costs, rising competition and the impact of weak mix.
Improving supply side, new product launches, and ramp-up in exports are expected to drive the next phase of growth for RE.
Valuations reflect the volume recovery expectations, but not the potential risk from competition.
Nirmal Bang Securities Pvt.
Maintains 'buy' with target price of Rs 3,904, implying a potential growth of 16%.
Expects demand to remain strong during the upcoming festive season and drive volume growth, going ahead, in the domestic market.
Market share expected to decline with entry of competition.
Factor in margin recovery of 300 basis points over FY23-25.
Dolat Capital Market Pvt.
Recommends 'sell' with target price of Rs 3,072, implying a potential profit of 9%.
Increase in competitive intensity has changed the business dynamics unfavorably for RE for near-to-medium term, which will lead to de- rating of target multiple.
Rising contribution of Hunter in overall volume and increased branding and marketing expenses (to counter competition) to restrict margin expansion.
Expects increasing competitive intensity to restrict volume growth and pricing power.

-
Signature Play: The Classic Cocktail Is Dead. Or Is It?

Classic cocktails are disappearing from India's cocktail menus. But they're still being ordered, taught to bartenders and borrowed from. So, who's really having the last drink?
-
A New Samvat Wishlist: Inclusive Prosperity And Human Development
India has strengthened its economic foundations through infrastructure, digital access and enterprise. Its next growth chapter must deepen productivity, create better livelihoods and widen participation in prosperity.
-
Love, Sex Aur Dhokha: The Audacious Plot To Spy On Jensen Huang
A Taipei dinner, a Singapore chip buyer and a suspected Chinese asset: inside the alleged spy operation that got close to NVIDIA's Jensen Huang.
-
Ten Things I Learnt This Samvat
Patience can be a trap. Cheap stocks can stay cheap. Leverage can wipe you out. What did Samvat 2082 teach us? Niraj Shah writes on 10 lessons from the year gone by.
-
Talking Points This Week: Tech Nerves, FII Buying, And A Faraway Banking Shock
The global markets are not shining this Diwali. The exception in the large markets is, India.
-
Midterm Rally Lasted A Day. The Hard Reality Of A Divided US May Last Two Years | Opinion
Between a contested AI boom, a debt ceiling that arrives in 2027 and a president with every incentive to act alone, the next two years may prove more volatile than the first day's rally suggests.
-
Blue Wave Will Derail the AI Trade but Won't Dismantle the AI Era | Unhedged Position
The Democrats' sweep of the US Congress will see politics collide with economic forces both over the long and short term.
-
It's Time To Take The GST Council's Bet On Trust Global
Payment records can prove India's services exports, and clear, proportionate rules can bring foreign digital sellers into the tax net.
-
Opinion | India at 38: From Innovation Overperformer to Innovation Powerhouse
India now has 453 VC-backed deep science startups, 18 of them late-stage, after 117 percent growth since 2020. Laurus Labs, at USD 9.3 billion, is the most valuable deep science company in any middle-income economy outside China.









