'Buy' United Spirits Shares Maintains Nirmal Bang; Says Price Correction Leads To Attractive Entry Points
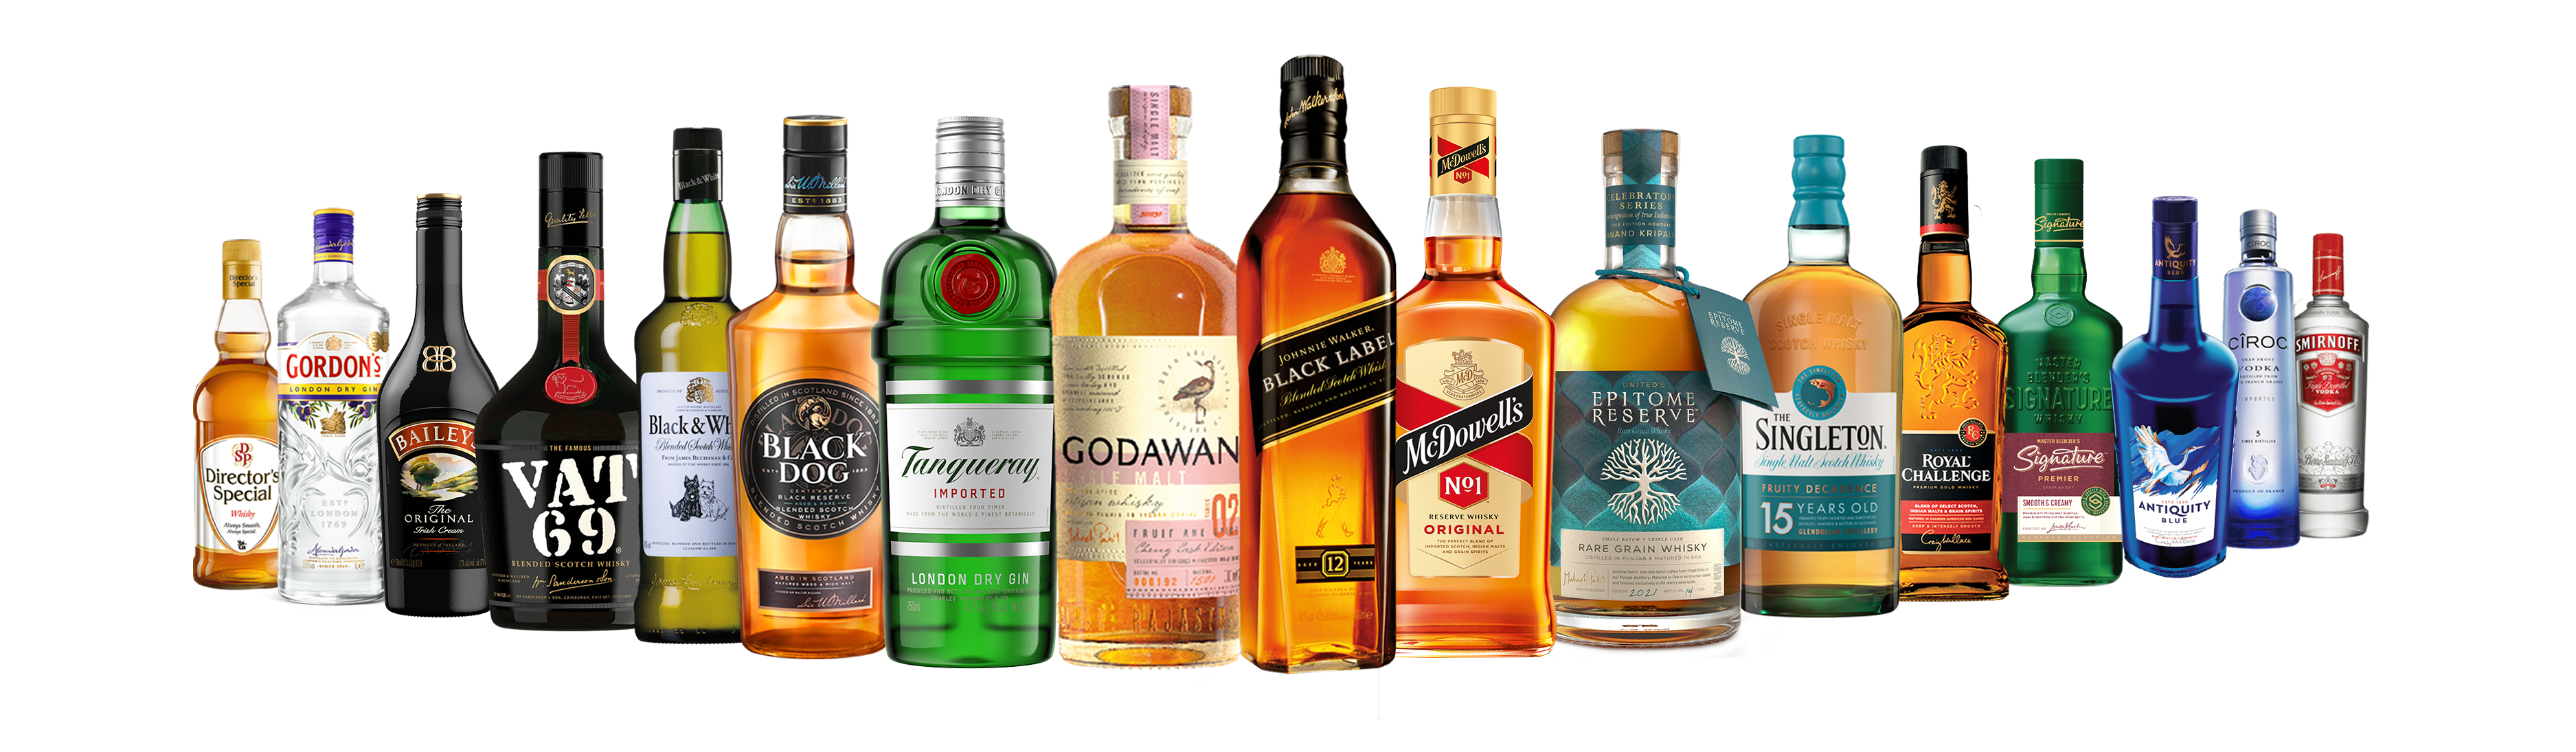
In FY25, United Spirits expanded and diversified its portfolio with Royal Challenge American Pride and JW Blonde each contributing 7% to their respective trademarks by NSV, McDowell's X Series entering multiple new spirit categories, Smirnoff launching Indian-inspired flavors, and a focus on the fast-growing white spirits segment (16% 3-year CAGR) across price points to capture the evolving consumer demand.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Nirmal Bang Report
United Spirits Ltd. has done extremely well on operating parameters over the last decade with PAT CAGR of ~24% over this period and an extremely healthy PAT CAGR of ~15% over the last five years as well. A combination of factors like:
focus on the high growth and high margin prestige and above segment,
better execution on brand building compared to the past,
exiting commoditized popular business in most states,
significantly better operating efficiency,
relatively favorable operating environment in the last five years, and
significant deleveraging has meant not only robust earnings growth but phenomenal improvement in return ratios from mid-single digits at the end of FY15 to over 20% at the end of FY25.
Consequently, the stock has generated formidable returns of ~17% CAGR in the last five years. The sharp increase in excise in Maharashtra in Jun-25 has been a setback, and therefore, as part of our Q1 FY26 preview, we had assumed that EPS growth is likely to be flat in FY26 (we are assuming Ebitda from Maharashtra will halve over FY25 levels in the current year); the 20% stock price correction following the excise increase announcement provides as attractive entry point as:
the above factors which led to strong earnings growth over the last decade are still very much at play,
demand environment for alcobev outside Maharashtra remains strong,
recent policy changes in Andhra, Uttar Pradesh, and Karnataka are actually providing a tailwind for spirits category growth,
material cost outlook is favorable, and
benefits of India UK FTA on volume growth and raw material savings are likely in FY27.
Consequently, robust earnings growth trajectory should be back from FY27. We continue to value United Spirits at 55x Jun-27E standalone EPS (5-year average ~53 times, 10-year average ~65 times) and attribute Rs 170 per share value to its 100% stake in RCB giving us a target price of Rs 1,665, ~28% upside to the CMP.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.

-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families

The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.
-
You May Inherit The Business. You Must Earn Its Credibility.
Succession tests the founder's ability to share authority as much as it tests the next generation's readiness to assume it.
-
Signing Deals Is One Thing; Making Them Work Is Another | The Week In Whys
Sometimes, things don't turn out as planned. Indian companies have lost some bids to rivals, some projects won't produce until 2030.
-
FOMC Wall, PERM Suspension, Hospital Stocks | Talking Points This Week
A PERM suspension would directly affect green-card sponsorship rather than H-1B visas, so the near-term earnings impact could remain relatively limited. The key question is whether this marks a new phase in US scrutiny of Indian IT.









