Zomato Pips Swiggy To Bag Up To 28% Upside From Analysts
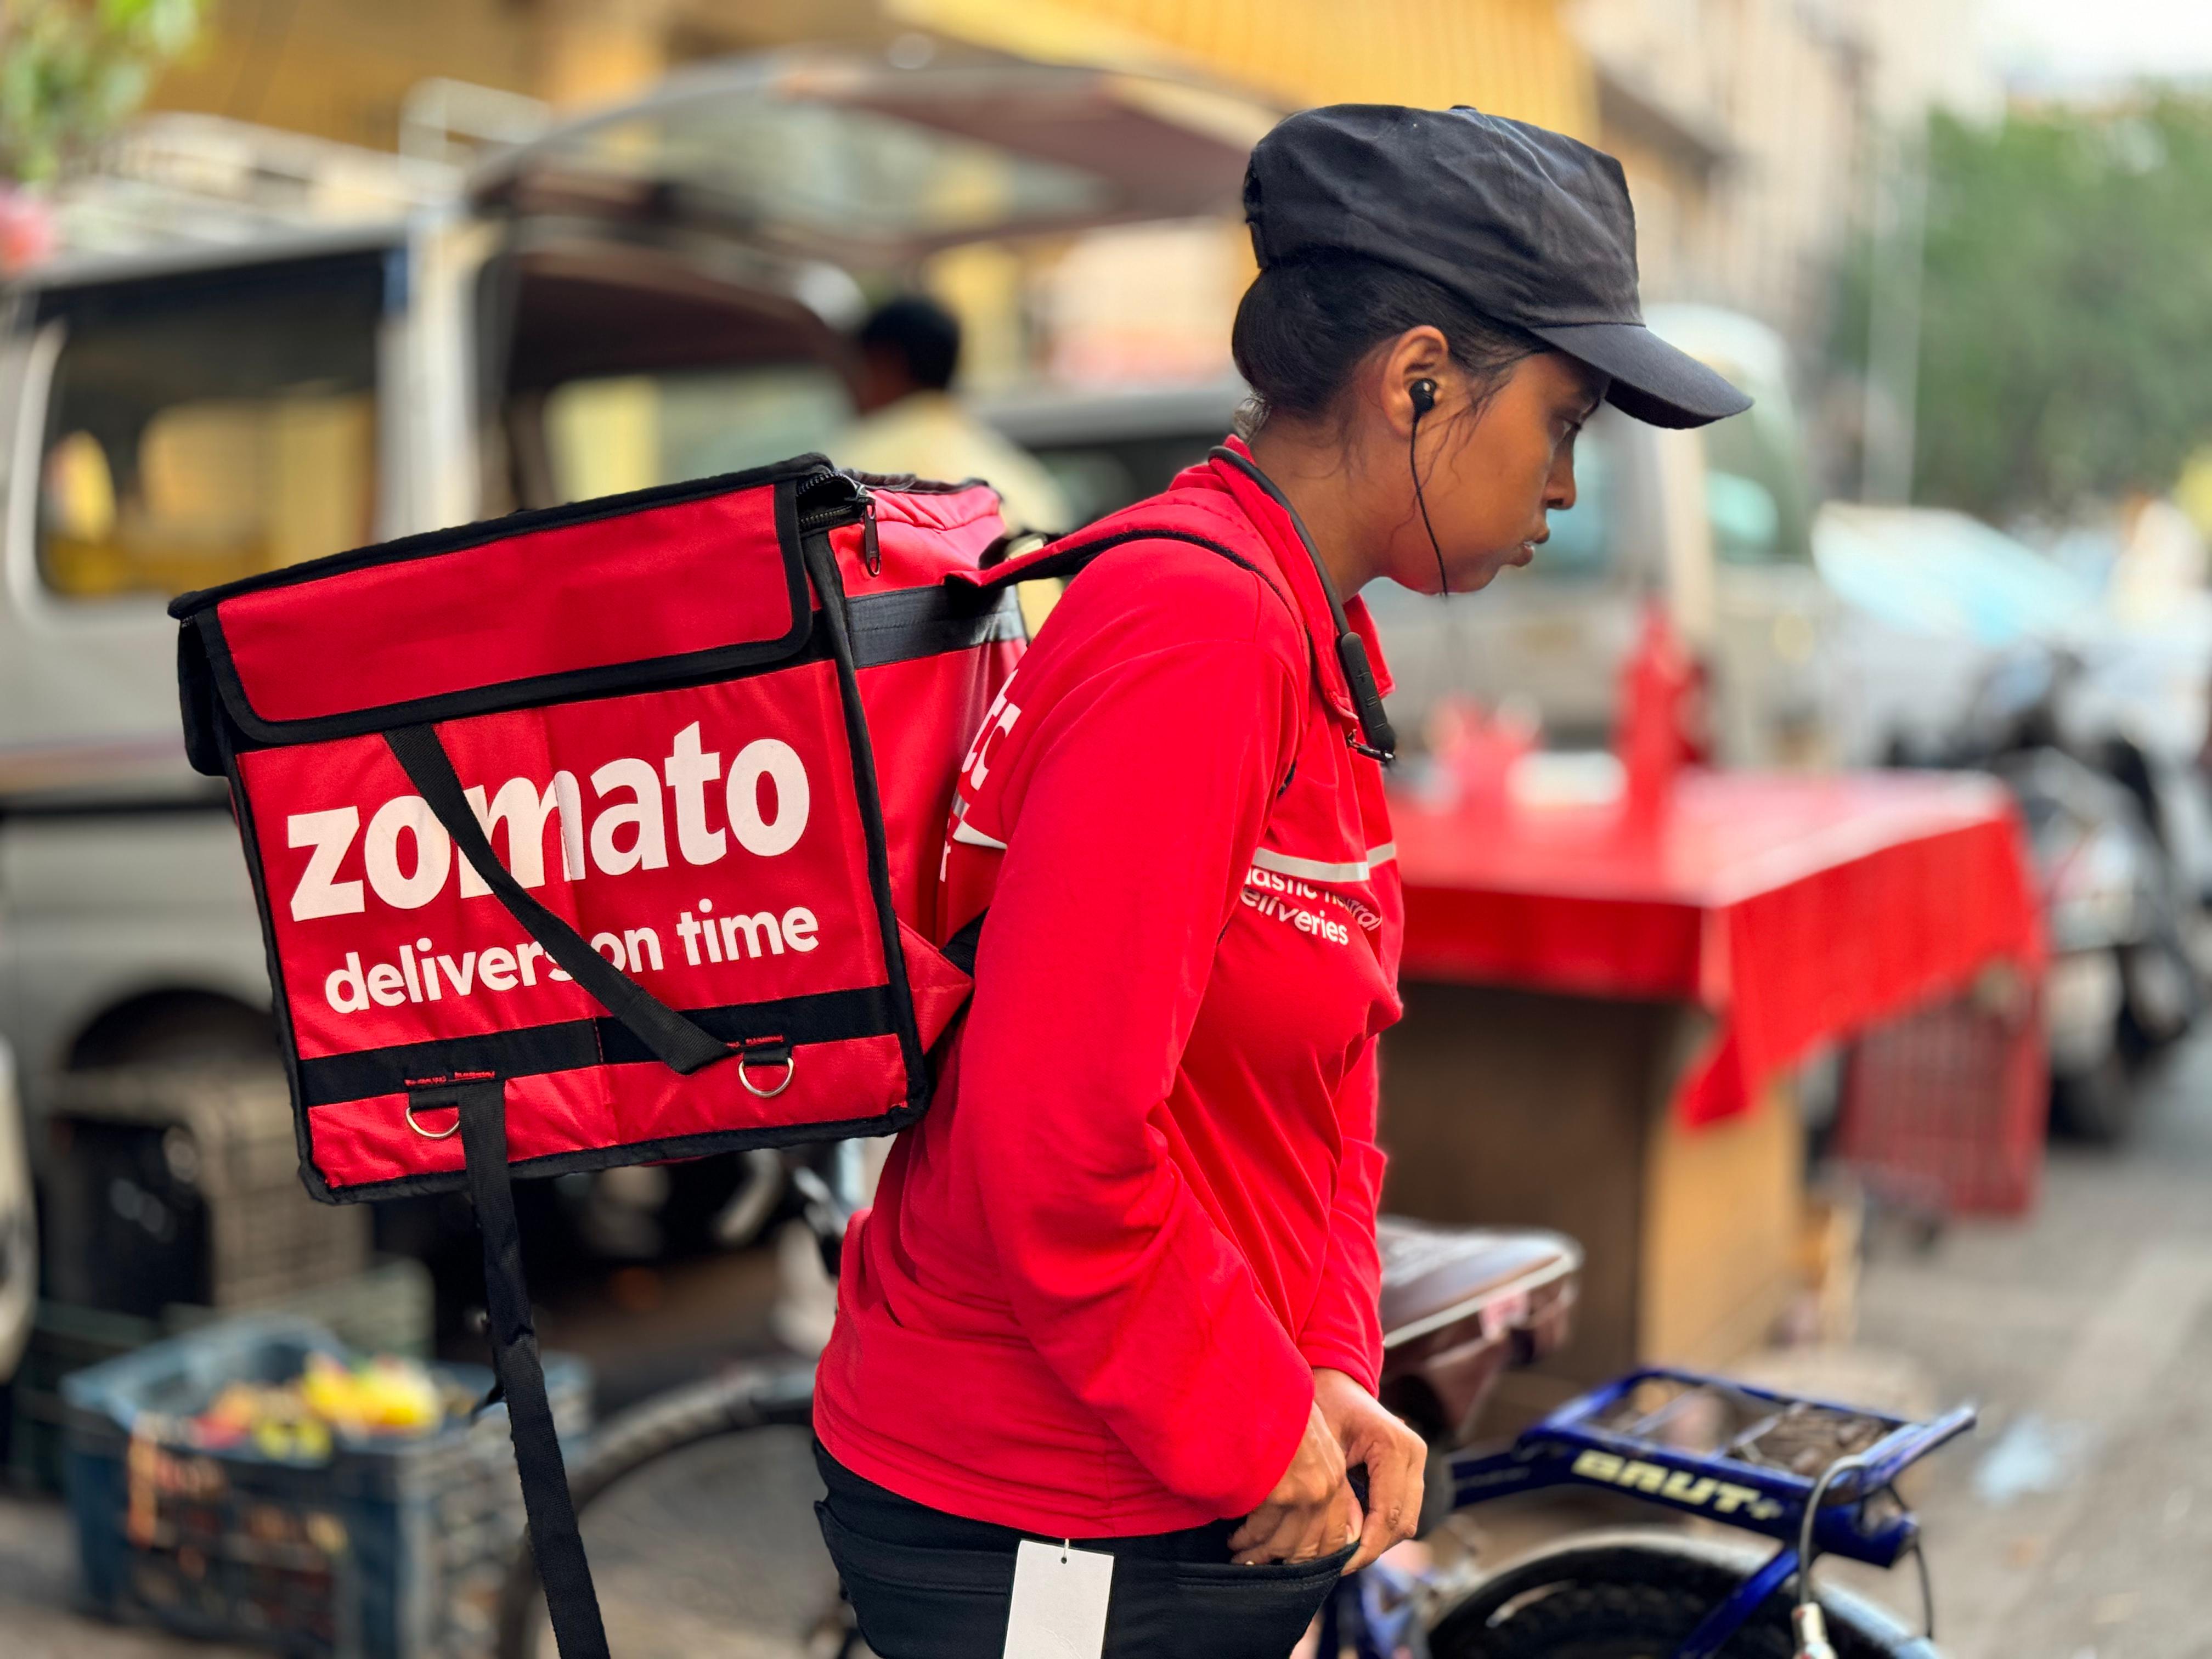
Brokerages are bullish on Zomato Ltd. as it is outperforming Swiggy with higher revenue growth and profitability.
Being ahead of its peers on profitability, Zomato will continue to provide opportunities to further gain market share and improve profitability, Goldman Sachs said in a note.
The comments come after Prosus, which holds a 32.7% stake in Swiggy, has disclosed key data points on Swiggy's operating performance, highlighting improvements but it is still lagging behind Zomato.
Here's What Brokerages Say
CLSA
Maintains a ‘buy' rating on the stock and a target price of Rs 248 apiece, implying a potential upside of 28% from the previous close.
Zomato reported positive earnings before interest, taxes, depreciation, and amortisation of $5 million, while Swiggy's trading losses reduced to $158 million.
Zomato's overall gross order value growth is 36% as compared to Swiggy, which is at 26%.
Zomato's revenue grew at 56% versus Swiggy, which is at 24%.
Zomato is growing faster than Swiggy.
Zomato's Blinkit has 526 dark stores as compared to Swiggy Instamart's 487 dark stores.
Emkay
Maintains a ‘buy' rating on the stock and a target price of Rs 230 apiece, implying a potential upside of 16% from the previous close.
Zomato's higher growth has been aided by the superior performance of its quick commerce section Blinkit.
Swiggy's overall losses narrowed to $261 million from $531 million in 2022.
Swiggy's IPO is now a key milestone, with valuation being the main monitorable.
Steady improvement in operational performance and the planned IPO of Swiggy are likely to keep investor interest high in the space.
Goldman Sachs
Maintains a 'buy' rating on the stock and a target price of Rs 240 apiece, implying a potential upside of 21% from the previous close.
Prosus' Swiggy disclosure suggests further share gains for Zomato.
The GOV scale of Zomato is more than 30% larger than that of Swiggy.
Zomato's market share is now at 56–57%, with a 200 bps expansion as compared to the previous period.
Quick commerce Zomato scale is likely 50% larger than its nearest competitor.
Zomato being ahead of its peers on profitability will continue to provide opportunities to further gain market share and improve profitability.
Online grocery delivery expects competition to be consistent.
Kotak
Maintains a 'buy' rating on Zomato and a target price of Rs 225 apiece, implying a potential upside of 13.6% from the previous close.
Zomato's overall gross-merchandise-value growth came in at 32% year-on-year, compared with Swiggy's 26% year-on-year growth.
Prosus, which holds a 32.7% stake in Swiggy, disclosed Swiggy's overall GMV growth in its annual results.
Swiggy's revenue closely trails gross merchandise value growth; losses came further in calendar year 2023.
Higher growth from Instamart could have diluted the overall take rate.
Swiggy's adjusted Ebitda loss came in at $261 million in 2023, substantially lower than $531 million reported in 2022. By comparison, Zomato reported adjusted Ebitda profit of $20 million in 2023.
Swiggy's food-delivery profitability improvement was aided by added revenue streams, such as restaurant advertising and platform fees.
Swiggy's quick commerce gross merchandise value growth was much ahead of peers.
Blinkit had 487 dark stores as of March 2024, whereas Zepto currently has 350 stores. This makes Swiggy number two among quick commerce players from the perspective of dark store count.

-
Love, Sex Aur Dhokha: The Audacious Plot To Spy On Jensen Huang

A Taipei dinner, a Singapore chip buyer and a suspected Chinese asset: inside the alleged spy operation that got close to NVIDIA's Jensen Huang.
-
Ten Things I Learnt This Samvat
Patience can be a trap. Cheap stocks can stay cheap. Leverage can wipe you out. What did Samvat 2082 teach us? Niraj Shah writes on 10 lessons from the year gone by.
-
Talking Points This Week: Tech Nerves, FII Buying, And A Faraway Banking Shock
The global markets are not shining this Diwali. The exception in the large markets is, India.
-
Midterm Rally Lasted A Day. The Hard Reality Of A Divided US May Last Two Years | Opinion
Between a contested AI boom, a debt ceiling that arrives in 2027 and a president with every incentive to act alone, the next two years may prove more volatile than the first day's rally suggests.
-
Blue Wave Will Derail the AI Trade but Won't Dismantle the AI Era | Unhedged Position
The Democrats' sweep of the US Congress will see politics collide with economic forces both over the long and short term.
-
It's Time To Take The GST Council's Bet On Trust Global
Payment records can prove India's services exports, and clear, proportionate rules can bring foreign digital sellers into the tax net.
-
Opinion | India at 38: From Innovation Overperformer to Innovation Powerhouse
India now has 453 VC-backed deep science startups, 18 of them late-stage, after 117 percent growth since 2020. Laurus Labs, at USD 9.3 billion, is the most valuable deep science company in any middle-income economy outside China.
-
Navigating Energy Crossroads: S Jaishankar's Call For Diversified Supply Chains At G20 Ministerial Meeting
As geopolitical fault lines continue to test maritime trade routes and commodity flows, Jaishankar's message remains pertinent: true economic resilience requires open markets, protected transit lines, and a genuine commitment to multilateral cooperation rather than coercion.
-
Indians Are Travelling, But Not Every Journey Is A Holiday | The Week In Whys
Pilgrims, patients and working women are the real travellers, and the system hasn't quite caught up with them.









