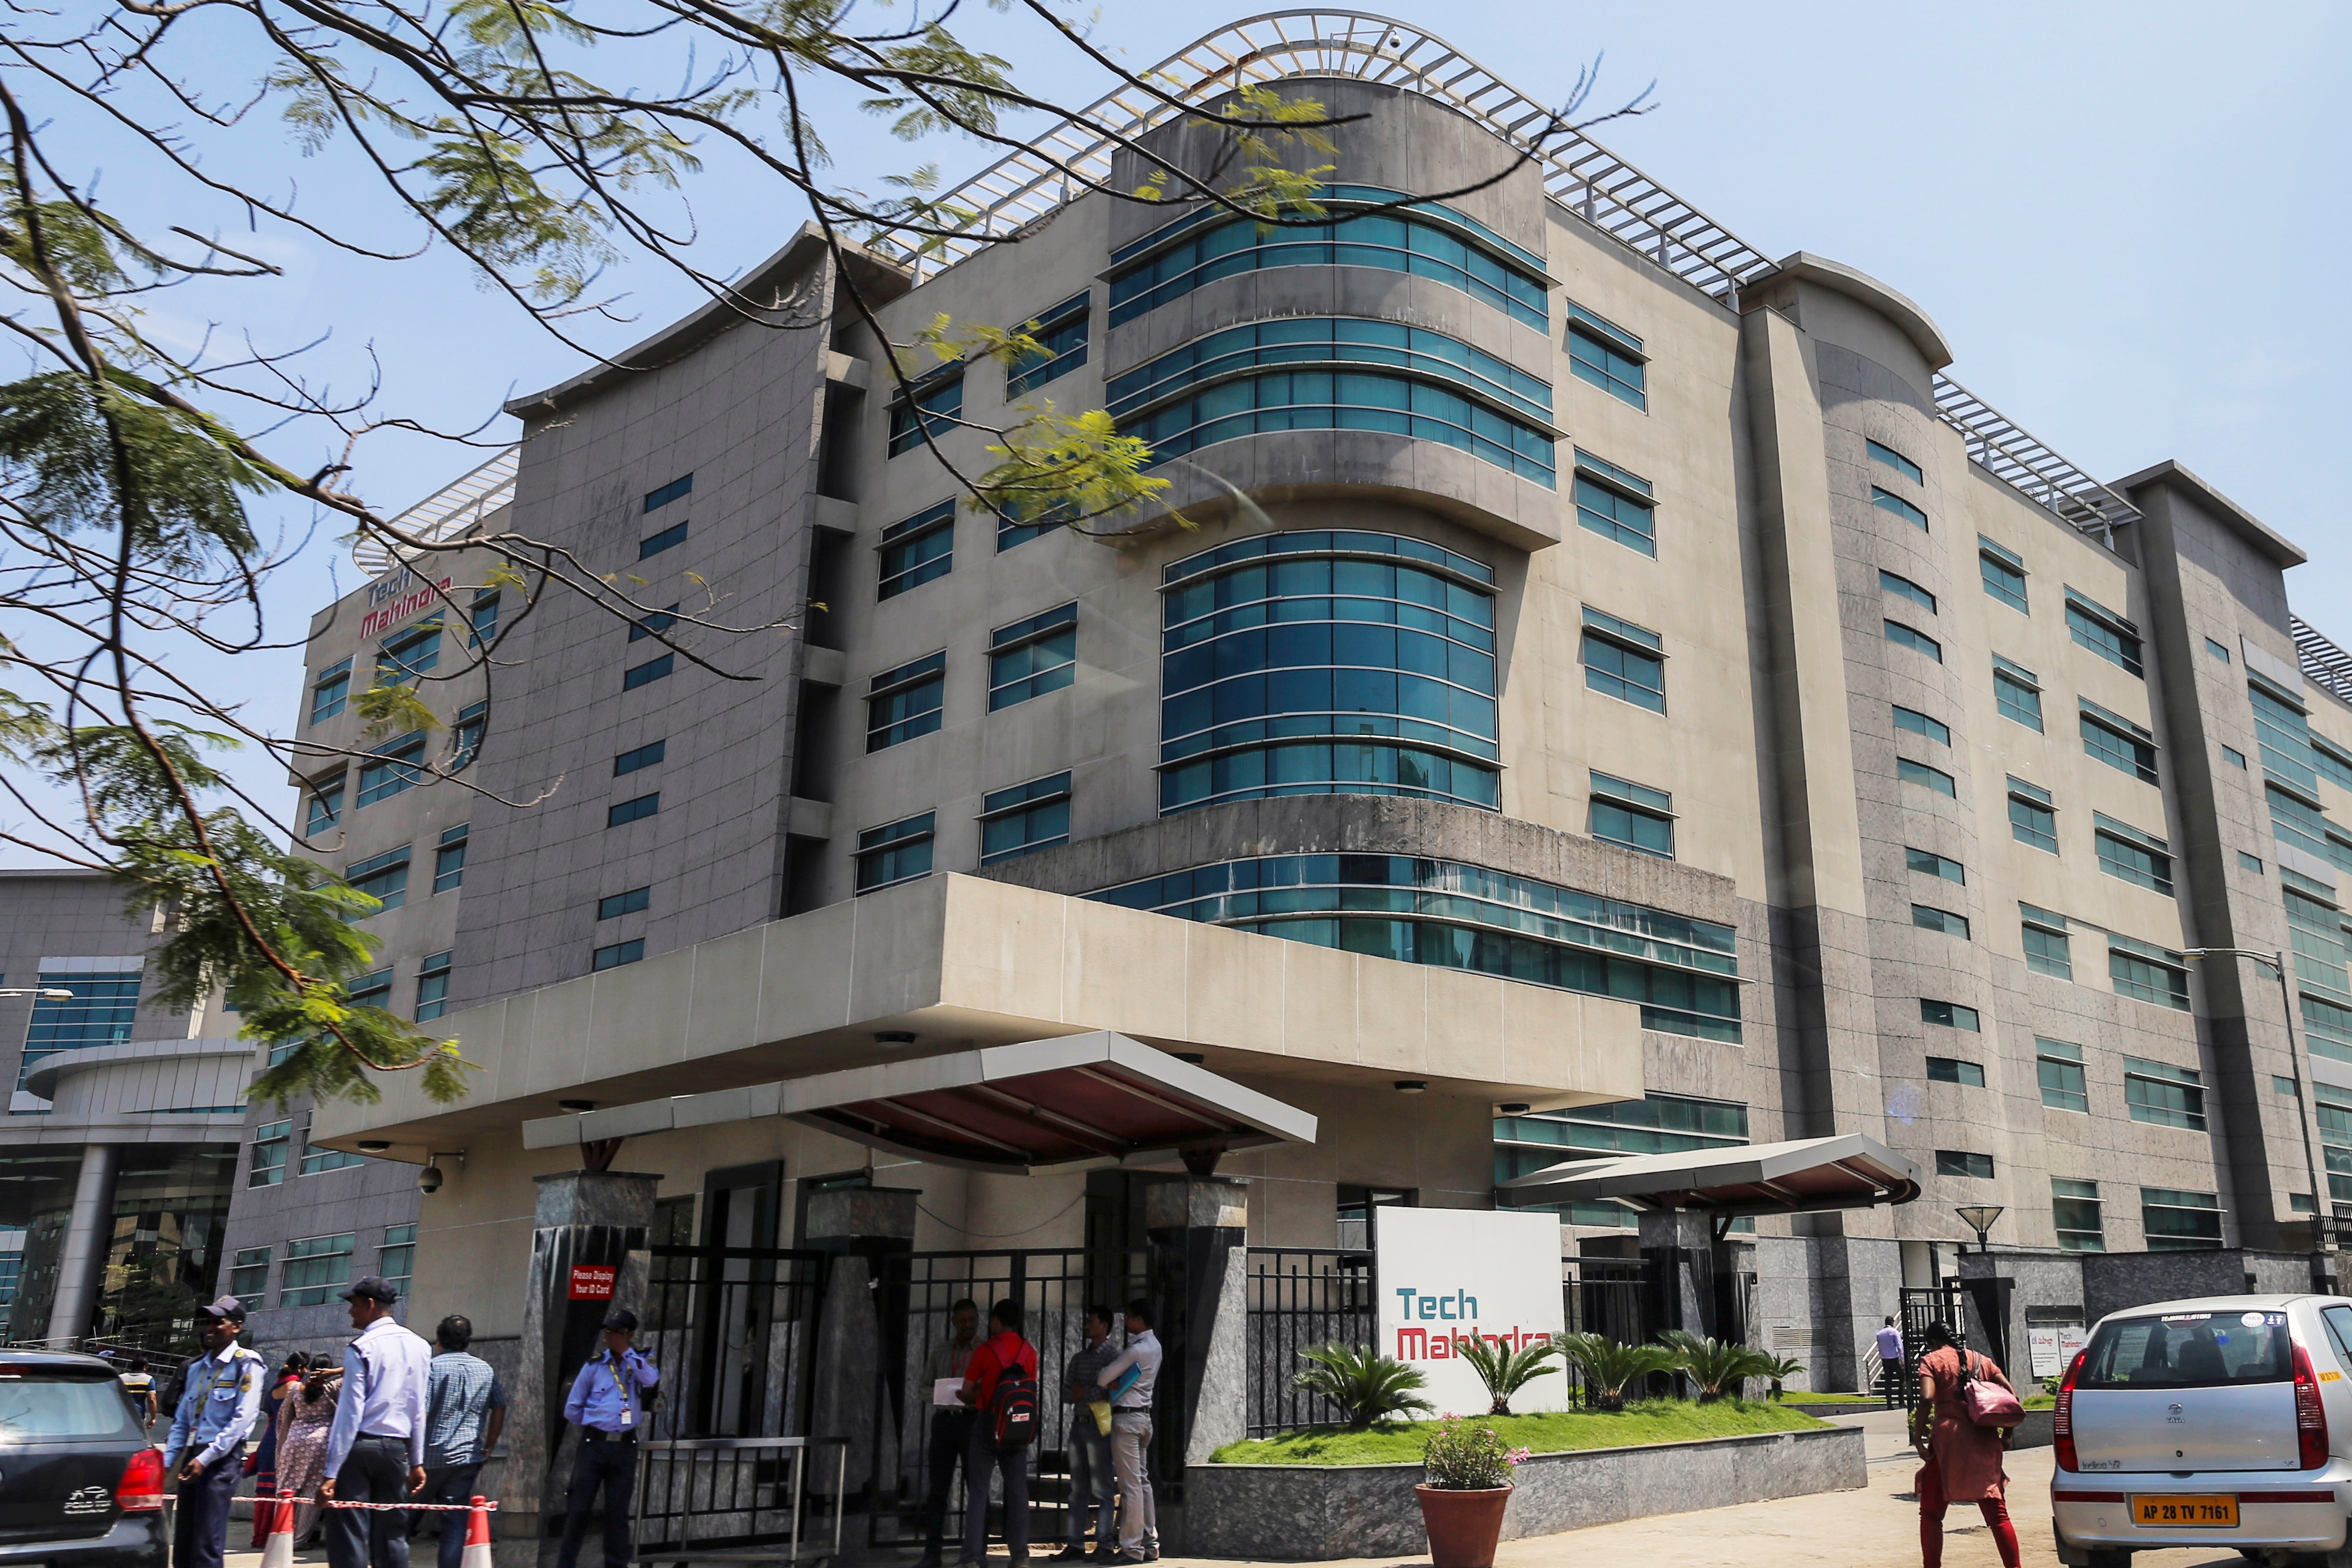
Shares of Tech Mahindra Ltd. snapped their four-day gaining streak after the software services provider's revenue and profit declined and margin contracted in the quarter ended March on disruptions caused by the new coronavirus pandemic.
Net profit of the company tumbled nearly 30 percent sequentially to Rs 804 crore in the January-March period, according to an exchange filing. While its revenue in rupee terms fell 1.7 percent to Rs 9,490 crore, in dollar terms the top line dropped 4.3 percent to $1,294.6 million. The company's margin narrowed 450 basis points to 7.7 percent.
Yet, most analysts maintained their bullish investment recommendations on the company's “attractive” valuations and expectations of a recovery by the financial year ended March 2022.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Of the 47 analysts tracking the stock, 36 recommend a ‘buy', six suggest ‘hold' and five have a ‘sell' rating. The average of 12-month price targets tracked by Bloomberg implies an upside of 25 percent.
Shares of Tech Mahindra fell as much as 7.8 percent in early trade to Rs 503.5 apiece. That compares with 4.92 percent drop in the benchmark Nifty 50 Index.
Here's what the brokerages have to say about Tech Mahindra's fourth-quarter results…
Ambit Capital
- Retains ‘buy' with a target price of Rs 635 apiece
- Growth disappoints, margins likely to improve
- Some BPO, network services issues are temporary
- Half of margin fall led by non-recurring items
- Expects to see cost cut aggression
- Forte in cost efficiency focused telecom vertical
Kotak Institutional Equities
- Retains ‘buy' but cuts target price to Rs 630 from Rs 680 a share
- Covid-19 impact advanced
- Expects normalisation of growth in FY22
- Retains positive stance on attractive valuations
Investec
- Retains ‘buy' with a target price of Rs 630 apiece
- Covid-19 strikes hard earlier than expected
- Expects recovery to come through in the long term
- Provisions made unlikely to recur in subsequent quarters
- Cuts FY21 EPS by 4.3 percent but retains FY22 EPS projection
Centrum Broking
- Downgrades to ‘add' from ‘buy' and cuts target price to Rs 595 from Rs 680 a share
- Earnings were below expectations
- Expects some margin volatility
- Goodwill write-off hurts profit
- Company has high exposure to project-based work
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.