Tata Consumer Q4 Preview: Volume Growth Expected To Be Stagnant; Margin Likely To Face Inflation Pressures
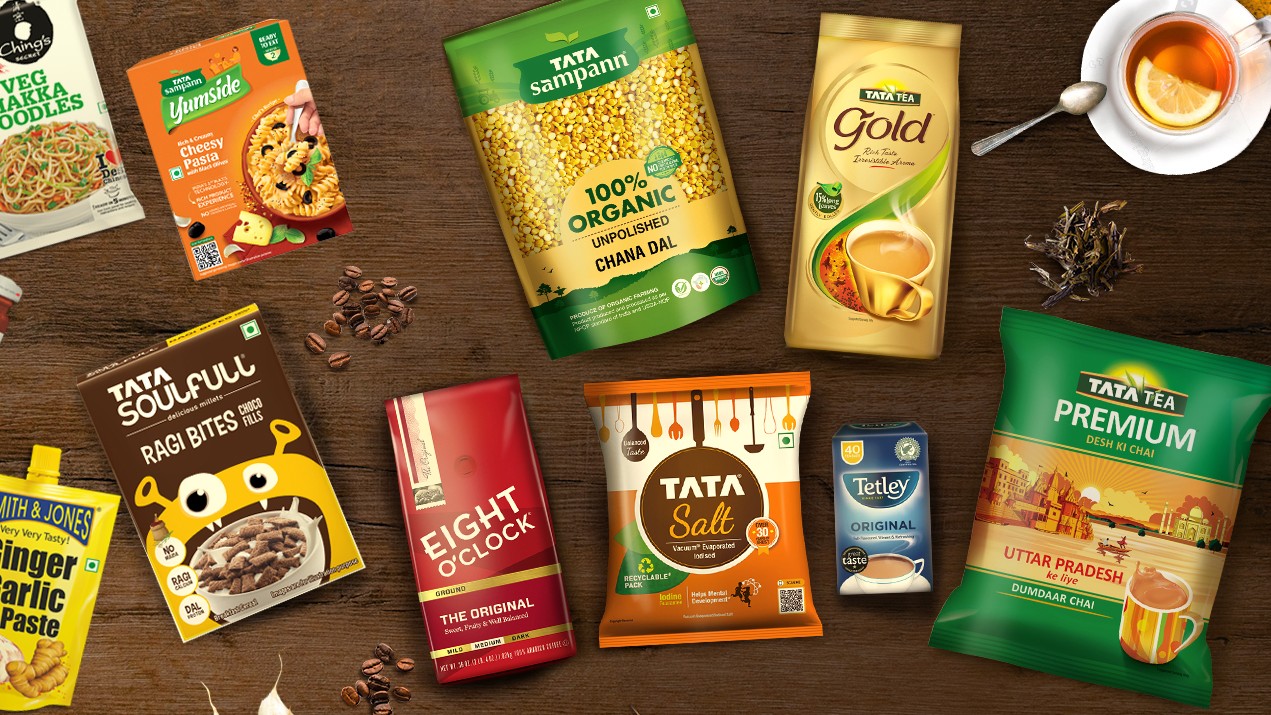
Tata Consumer Products Ltd. will kick off the March quarter earnings season for the fast-moving consumer goods sector on Wednesday, with brokerages expecting a mixed bag for the company.
While revenue is projected to rise, analysts expect Ebitda to decline, largely due to margin pressures and high input costs. Across the sector, brokerages expect steady revenue growth supported by pricing actions, but however, expect volume growth to be muted. Tata Consumer is among the few FMCG firms expected to clock double-digit revenue growth this quarter.
According to Bloomberg's consensus estimates, revenue for Tata Consumer Products is expected to rise 16% year-on-year to Rs 4,656 crore.
Tata Consumer Q4 Preview (Consolidated, YoY)
Revenue seen 20% higher at Rs 4,556 crore versus 3,927 crore.
Ebitda seen 3% lower at Rs 612 crore versus 630 crore.
Margin seen at 13.43% versus 16.04%.
Profit seen 49% higher at Rs 225 crore versus 217 crore.
Brokerage Views
Jefferies | Target Price: Rs 1,069.25 | Rating: Buy
Jefferies notes that demand trends in the FMCG sector for the March quarter are broadly similar to the previous quarter, with rural demand showing gradual recovery while urban demand remains subdued.
The brokerage expects Tata Consumer's revenue to rise 17% yoy and Ebitda to fall 3%, calling the company an outlier due to recent acquisitions.
Volume growth is seen at 4% versus 2% a year ago and flat sequentially.
Jefferies expects 11% like-for-like growth in India, with both food and beverage categories contributing equally.
NourishCo is projected to grow 5%, while Sampann continues to perform well.
Consolidated Ebitda margin is expected to contract by over 250 basis points YoY.
Summer beverages such as Tata Gluco Plus, Tata Fruski, and Himalayan mineral water are likely to benefit from early seasonal demand.
JPMorgan | Target Price: Rs 1,001.90 | Rating: Neutral
The brokerage expects revenue trends for the March quarter to remain stable for most staples companies, with urban markets still sluggish and rural recovery slow. High raw material inflation is likely to weigh on gross margins, although sequential improvement is expected.
Tata Consumer is expected to report 17% yoy revenue growth, a 4% decline in Ebitda, and a 26% drop in net profit.
JPMorgan forecasts low- to mid-single-digit volume growth for the tea and salt portfolio due to price hikes.
The brokerage sees Tata Consumer as one of the four firms in its coverage expected to post double-digit revenue growth.
However, rising costs for edible oils, tea, cocoa, and coffee are expected to squeeze margins significantly.
Morgan Stanley | Target Price: Rs 1,001.90 | Rating: Overweight
Morgan Stanley expects subdued urban demand to continue, with price increases driving growth in categories such as copra, tea, and palm oil.
The brokerage sees Tata Consumer's revenue growing 14% yoy, with Ebitda down 8% and profit declining by 40%.
Tea volumes are expected to rise, and the NourishCo segment is expected to show sequential improvement. Margins are expected to decline on a yearly basis due to inflation but improve sequentially.
Bank of America | Rating: Neutral
Broader trends remain stable, but a meaningful recovery is still elusive, according to BofA. It expects the Indian consumer space to witness similar trends as last quarter, pointing to largely unchanged year-on-year trends across staples and discretionary segments.
Bank of America expects revenue growth for Tata Consumer to rise 16% yoy, while Ebitda may remain flat or decline, and profit is likely to fall 10%.
It sees the company among the top four FMCG names in terms of revenue performance. However, input cost pressures and heightened competitive intensity are expected to limit Ebitda margin expansion.
Citi | Target Price: Rs 1,200 | Rating: Buy
Citi expects Tata Consumer to report 16% yoy revenue growth, flat Ebitda compared to a 24% rise a year ago, and an 11% decline in profit.
The brokerage notes that subdued urban demand, high competition, and input cost inflation continue to weigh on FMCG earnings. While rural markets are holding up, urban demand remains muted.
Citi expects the sectors' earnings growth to remain under pressure due to negative operating leverage and higher trade promotions.
Goldman Sachs | Target Price: Rs 1,040 | Rating: Neutral
Goldman Sachs forecasts 16.1% revenue growth for Tata Consumer, driven by both organic momentum and recent acquisitions. Ebitda is seen falling 4.7%, while profit is expected to rise 17% YoY..
The brokerage expects the company to outperform peers on the top topline due to premiumisation and the scale-up of new categories.
Volume growth is projected to be in the mid-single digits. However, it does not expect Ebitda margin recovery before the first half of the financial year 2026 due to steep cost inflation in tea, coffee, palm oil, and copra.
Nomura | Target Price: Rs 1,250 | Rating: Buy
Nomura expects Tata Consumer to report 13.5% yoy revenue growth, a 7.2% decline in Ebitda, and a 3.1% drop in net profit.
The brokerage forecasts one of the highest quarter-on-quarter price hikes in the sector for the company. Growth in tea and salt is seen in double digits, with NourishCo expected to return to growth.
Nuvama | Target Price: Rs 4,050 | Rating: Buy
Nuvama expects Tata Consumer to deliver 15.4% yoy revenue growth, a 5% decline in Ebitda, and a 20.5% fall in profit.
The brokerage notes sequential improvement in volume trends, though margins are likely to be hit due to inflation in tea, palm oil, and coconut oil. Rural growth is outpacing urban markets, which continue to face cost-related headwinds.
Capital Foods and Organic India, both recent acquisitions, are expected to post a combined revenue of around Rs 3,207 crore in the March quarter, with improved performance from Capital Foods.
Motilal Oswal Financial Services | Target Price: Rs 1,150 | Rating: Buy
Motilal Oswal expects Tata Consumer to report a 17% rise in revenue, a 6% drop in Ebitda, and an 18% decline in profit for the March quarter.
Higher tea prices and volume growth are expected to drive value growth, though margin pressures persist. The salt segment is expected to post a strong quarter on the back of successive price hikes.

-
Navigating Energy Crossroads: S Jaishankar's Call For Diversified Supply Chains At G20 Ministerial Meeting

As geopolitical fault lines continue to test maritime trade routes and commodity flows, Jaishankar's message remains pertinent: true economic resilience requires open markets, protected transit lines, and a genuine commitment to multilateral cooperation rather than coercion.
-
Indians Are Travelling, But Not Every Journey Is A Holiday | The Week In Whys
Pilgrims, patients and working women are the real travellers, and the system hasn't quite caught up with them.
-
Getting To Work Costs Women More | The Reason Why
It is not just about women paying more than men. It is about women paying much more in cities than in villages.
-
AI Bias In Investing Cannot Be Eliminated, But It Can Be Governed
Framing is a particularly important example as identical financial information presented in terms of gains rather than losses can lead an LLM to reach a different assessment.
-
Joining The Dots | Dark Skies, Steady Diya: Why Hope Holds This Diwali
With war, a weak rupee and foreign outflows weighing on sentiment, policymakers at the NDTV World Summit and market veterans at NDTV Profit Ignite: Diwali Edition offered the same advice: stay invested and filter out the noise.
-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock
PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.










