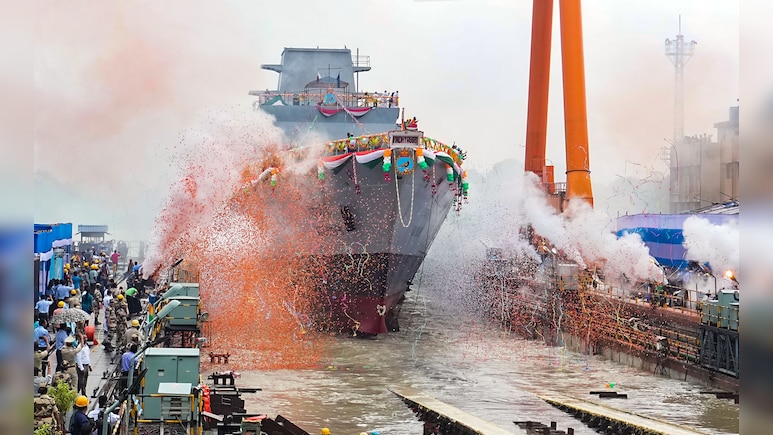
Mazagon Dock Shipbuilders Ltd. and Garden Reach Shipbuilders & Engineers Ltd. fell on Thursday after Goldman Sachs initiated coverage with Sell ratings, warning that low order replenishment and the end of major project deliveries could weigh on earnings.
Garden Reach shares dropped 4.33%, while Mazagon Dock declined 4.18%. Goldman Sachs set a 12-month price target of Rs 1,515 for Garden Reach and Rs 1,855 for Mazagon Dock, citing further downside risk as both companies approach a weaker phase of their earnings cycles.
The brokerage expects earnings before interest, taxes, depreciation and amortisation (Ebitda) at the two shipbuilders to contract through FY29, even as India's naval expansion plans point to longer-term demand. It sees a mismatch between the timing of potential orders and the revenue companies can generate from them.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Earnings pressure
Goldman Sachs expects Ebitda at Mazagon Dock and Garden Reach to decline at a compound annual growth rate of 19.3% between FY26 and FY29. That compares with projected growth of 26% for other aerospace and defence companies under its coverage.
For Mazagon Dock, the brokerage pointed to a low book-to-bill ratio and the long gestation period of shipbuilding contracts. It said major events that could drive a re-rating of the stock appear to have played out.
Garden Reach faces the risk of an earnings decline as delays in the next-generation corvette order push back the timing of new business, Goldman Sachs said.
READ | Mazagon Dock To Invest Rs 27,000 Crore For Shipbuilding Cluster To Generate 90,000 Jobs
Order concerns
Mazagon Dock's book-to-bill ratio stands at 1.37 times, while Garden Reach's is 1.87 times, both at cyclical lows, according to the brokerage. The companies are also nearing the end of major programme deliveries, raising the importance of fresh orders in sustaining future revenue.
India accounts for less than 1% of the global shipbuilding market. Defence and military vessels make up about 75% of India's domestic shipbuilding market, compared with around 22% globally, Goldman Sachs said.
The brokerage described Indian shipbuilding as a cyclical business in which long gaps between order placement and revenue recognition can cause earnings to fluctuate. Defence shipbuilders also work under fixed-price and cost-plus contracts, exposing profitability to cost variations.
Naval spending
Indian Navy capital expenditure has more than doubled from Rs 33,300 crore in FY22 to Rs 70,000 crore in the Union Budget for FY27, Goldman Sachs said. However, the brokerage expects incremental spending to be concentrated more on aircraft carriers and amphibious ships than on surface vessels, potentially delaying orders for other ship types.
The Indian Navy aims to expand its fleet to 200 ships by 2035. But programmes such as the P-17A frigates and P-75I submarines require multi-year tendering and gestation periods before they generate revenue, Goldman Sachs said.
The brokerage identified unmanned and autonomous platforms, ship repair and commercial shipbuilding as potential growth areas. It said private shipbuilders have an advantage in commercial shipbuilding because of their greater exposure to the segment.
Despite the longer-term opportunities, Mazagon Dock and Garden Reach trade at a premium to global shipbuilders on a market capitalisation-to-order book basis, Goldman Sachs said.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.