Mahindra & Mahindra's (M&M) recent stock correction offers an attractive entry point for investors, according to Kotak Neo (earlier known as Kotak Securities), which believes concerns around a tractor slowdown, SUV market share losses, new competition and commodity inflation have led to a disproportionate de-rating.
Analysts Rishi Vora and Apurva Desai retained their ‘Buy' rating on M&M, with a revised fair value of Rs 4,000 against Rs 4,175 earlier. The brokerage has cut its FY27-FY29 standalone earnings per share (EPS) estimates by 5-8%, factoring in lower tractor volume assumptions and margin pressures, but believes the company's long-term growth potential remains underappreciated.
At the current market price of Rs 2,864, the brokerage sees scope for a recovery as cyclical headwinds ease and new product launches support growth. It also considers M&M inexpensive at 15.5 times its FY28 estimated core EPS.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Why Kotak Neo Remains Bullish on M&M
M&M shares have declined around 10% over the past three months and 20% over the past year, despite earnings upgrades, as investors weighed several near-term concerns.
These include a cyclical slowdown in tractors, SUV market share losses as demand shifted towards hatchbacks and smaller SUVs, competition from new entrants such as JSW Motors, and commodity cost pressures.
Kotak Neo believes the stock's reaction has been disproportionate to the potential earnings impact. Its valuation framework places greater weight on the company's long-term growth runway than on near-term earnings, with cash flows over the next three years accounting for only 14% of the value under its discounted cash flow methodology.
The brokerage also highlighted M&M's leadership across SUVs, light commercial vehicles (LCVs) and tractors, alongside healthy return ratios and cash generation.
M&M Valuation Implies Just 3-3.5% Long-Term Volume Growth
Kotak Neo's reverse discounted cash flow analysis suggests that M&M's current market price implies a volume compound annual growth rate (CAGR) of just 3–3.5% over FY29–FY50. The brokerage considers this assumption conservative given the company's long-term growth opportunities.
In SUVs, low penetration in India, rising incomes and the continuing shift towards larger vehicles could support growth above the industry average. In LCVs, last-mile delivery demand, infrastructure spending and improved affordability following GST-related changes could support volumes.
The brokerage also expects farm mechanisation, rural labour shortages and increasing adoption of farm implements to underpin tractor demand beyond the current slowdown.
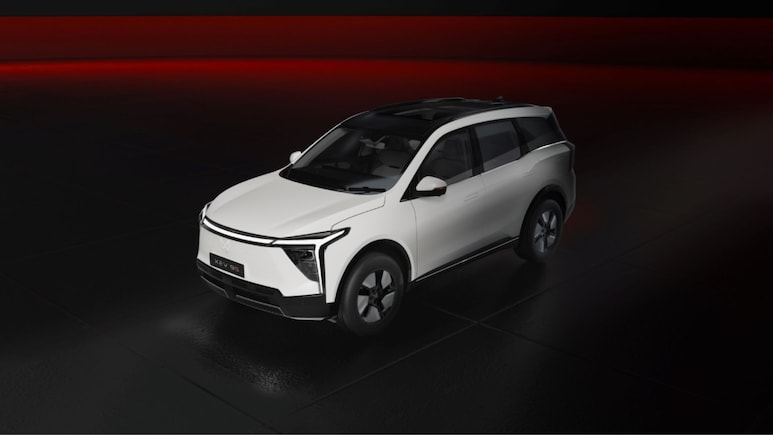
M&M's product pipeline adds to this outlook, with 16 new SUV launches and 10 new LCV launches planned by FY31, according to Kotak Neo.
Tractor Slowdown and Margin Pressures Weigh on Earnings Estimates
Despite retaining its Buy rating, Kotak Neo has lowered its FY27-FY29 standalone EPS estimates by 5-8%, citing weaker tractor volume assumptions and lower expected EBITDA margins amid multiple headwinds.
The brokerage expects tractor volumes to decline over the next four quarters, reflecting a weak monsoon and a high base. However, it views the slowdown as cyclical rather than a structural deterioration in the underlying drivers of mechanisation.
In SUVs, demand is expected to remain steady, while new launches in the calendar year 2027 could help M&M regain market share. The brokerage also expects new LCV launches based on the company's platform from the first half of calendar year 2027 to help reverse some of the recent market share losses.
Kotak Neo Cuts Fair Value To Rs 4,000, Retains Buy
Kotak Neo has reduced its fair value estimate for M&M to Rs 4,000 from Rs 4,175 earlier, using a sum-of-the-parts valuation methodology, while maintaining its Buy rating.
The brokerage's thesis rests on the view that near-term cyclical concerns have overshadowed M&M's longer-term growth potential. At 15.5 times estimated FY28 core EPS, it believes the stock's valuation does not fully reflect the growth opportunities across its SUV, LCV and tractor businesses.
The key factors to monitor are the trajectory of tractor demand, commodity costs, SUV market share and the execution of M&M's planned product launches.
READ | ICICI Life Insurance Q2 Review: Jefferies, Goldman Sachs Cut Targets Despite 22% VNB Growth
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.