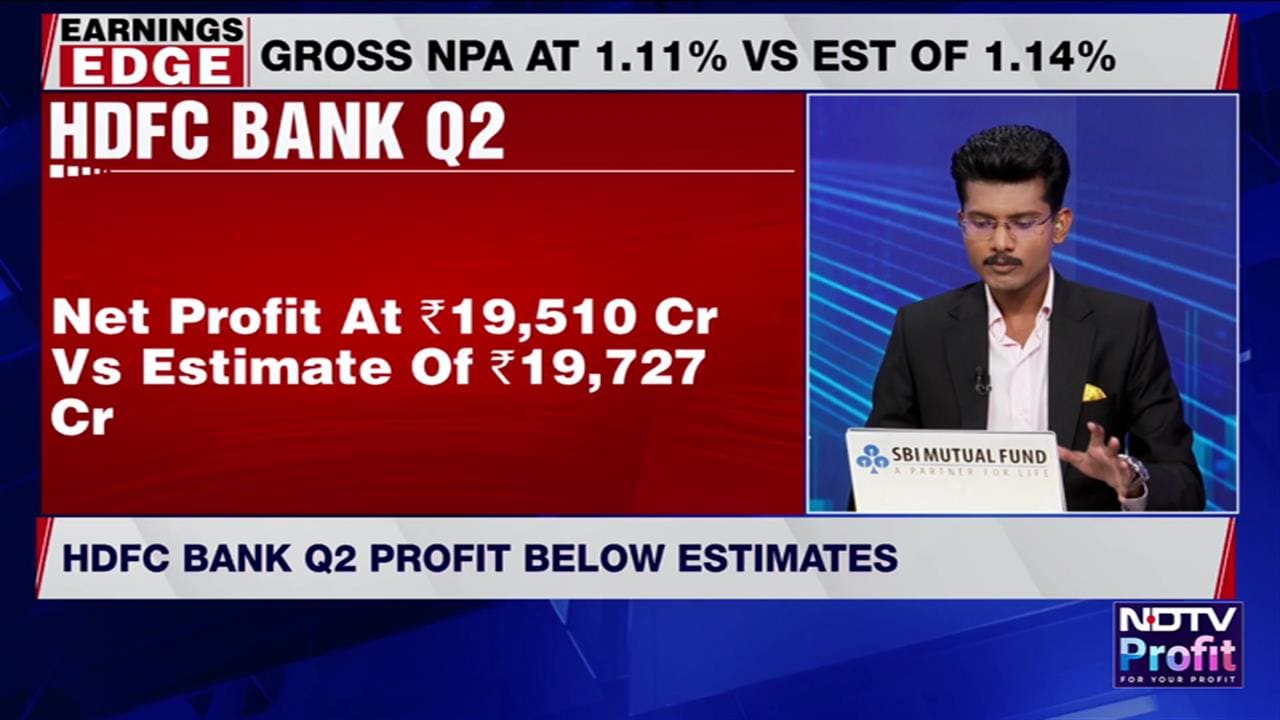
According to the brokearge HDFC Bank reported a largely in-line quarter, supported by healthy business growth and strong operating profits, although provisions were elevated. Net interest margins on total assets contracted by 10bp QoQ to 3.16%, while the bank has guided for NIMs to be on an upward trajectory from hereon. Healthy loan growth was driven by SME segment, while retail loan growth gathered some momentum. Deposit growth was healthy, with FCNR(B) mobilisation resulting in the CD ratio inching up to 96.0%.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Motilal Oswal Report
Following HDFC Bank Ltd.'s Septermber-quarter results, domestic brokerage firm Motilal Oswal has raisee its FY27/FY28 earnings estimates by 3.5% each and estimate the bank to deliver FY28E RoA/RoE of 1.74%/14.1%.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The brokerage has reiterated Buy rating, setting a target price of Rs 925, i.e. 1.8x timesFY28E adjusted book value + Rs 124 for subs.
According to the brokearge HDFC Bank reported a largely in-line quarter, supported by healthy business growth and strong operating profits, although provisions were elevated.
Net interest margins on total assets contracted by 10bp QoQ to 3.16%, while the bank has guided for NIMs to be on an upward trajectory from hereon.
Healthy loan growth was driven by SME segment, while retail loan growth gathered some momentum.
ALSO READ | HDFC Bank Q2 Review: Brokerages See Margin Support, But Execution Risks Remain
Deposit growth was healthy, with FCNR(B) mobilisation resulting in the CD ratio inching up to 96.0%.
Motilal Oswal expect the credit-deposit ratio to gradually moderate to ~93% by FY28E through calibrated balance sheet management. The bank maintains contingency and floating provisions of Rs 15,600 crore and Rs 21,400 crore, respectively.
Improvement in NIMs from retirement of highcost borrowings and operating leverage should support a gradual improvement in profitability and return ratios in the coming years.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.